








a16z's latest report: Technology has become the "everything cycle" in the global capital market, with 86% of VC funds flowing into AI. AI capital expenditures have pushed semiconductors, electricity, and defense back to the market's center stage, making hard infrastructure the new favorite
 Core Viewpoint

 The report reviews the market status from the perspectives of the stock market and technology for the year 2026 (at least the first two quarters) and provides insights for the future.
Author: Shou Ziwei, Investor Insider
Recently, the a16z Growth team released the second edition of "State of Markets II." The report reviews the market status for 2026 (at least the first two quarters) from the perspectives of the stock market and technology, and provides insights for the future.
Its core content can be summarized as follows: technology is no longer just a sector, but the "everything cycle" for profit growth in the capital market; within technology, the market focus has shifted from software to hardware and infrastructure; the argument of GPU obsolescence has been weakened by reality; the software industry has not reached its end, but has entered a phase of "proving itself"; AI adoption is still in its early stages.
Technology has become the "everything cycle," a substitute choice for high growth and capital-light
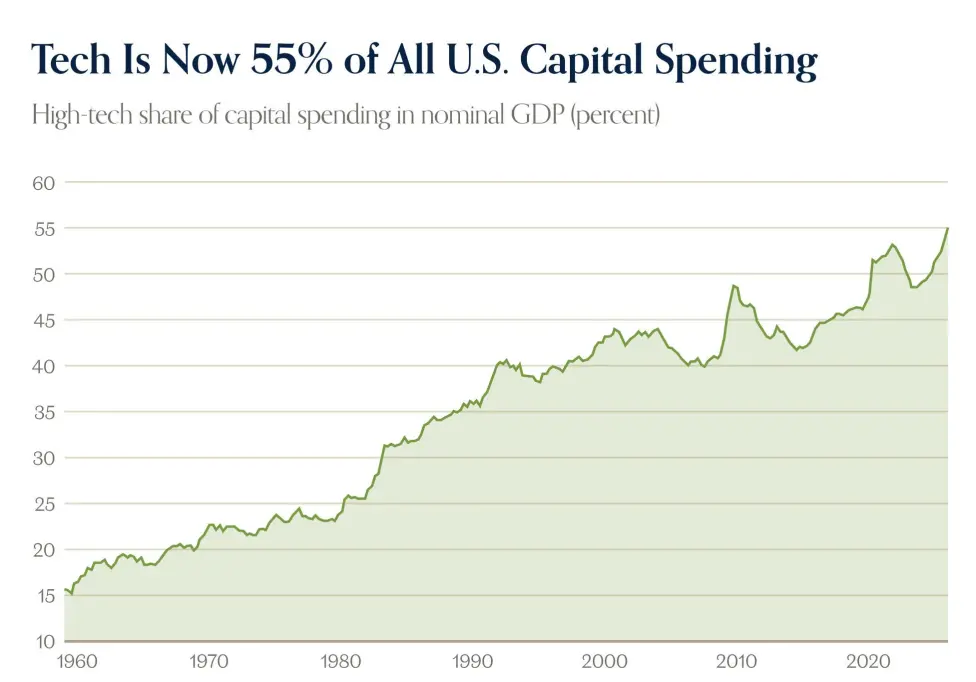
The core judgment of the report is that technology has transformed from a "cottage industry" into a major driving force of the global economy. The report states that today, every company is, in some sense, a technology company, and it is difficult to find businesses that operate solely with pen and paper. Technology drives investment, research and development cycles, profit growth, and margin expansion more than any other industry; the largest, most profitable, and fastest-growing companies are mostly technology companies.
The report points out that after the global financial crisis, technology truly took off as a force in the capital market. After the housing collapse and credit tightening, technology provided a high-growth, capital-light alternative for investors who were cautious about assets.
More importantly, technology has significant built-in operational leverage, as the addressable market is far from saturated, and the marginal cost of software is close to zero. In hindsight, those who doubted whether loss-making technology companies could grow into high-margin machines missed the theme of the last decade.
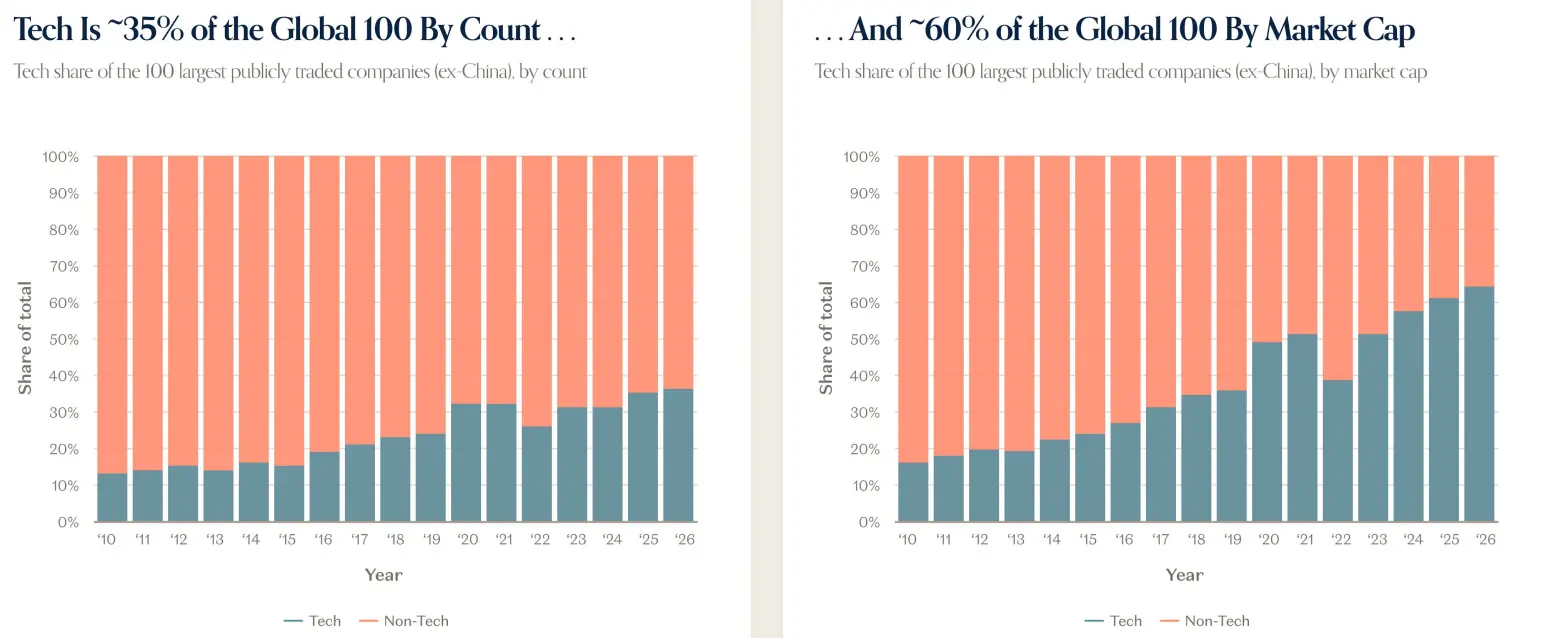
Software has indeed consumed the world, but technology's centrality in the capital market has risen to another level. Technology profits continue to compound, and although the base is low, it is more evident compared to other sectors. Since 2023, technology has almost been the story of profit growth: by the end of August 2026, technology contributed about 76% of the total profit growth of the S&P 500.
The report believes that technology can no longer be referred to as just a sector. In the past, durable goods defined cycles—houses, dishwashers, cars, etc.—and now technology has replaced them. Technology is everywhere and has become the "everything cycle."
Software dominated the last technology cycle, while hardware has taken center stage now
As technology has become the "everything cycle," the internal structure of technology is also changing.
The report states that the theme of annual and longer cycles is shifting from bits to atoms. Software dominated the last technology cycle, while hardware has now become the main character.
AI development is driving a surge in demand for traditionally slow-growing, cyclical, and capital-intensive industries such as semiconductors, power, and networking. This demand is largely financed by the historic profits of the largest global technology companies, functionally converting the free cash flow of hyperscale cloud providers into semiconductor free cash flow; at the same time, it is increasingly reliant on debt.
But it’s not just AI. Global infrastructure demand is measured in trillions, defense spending is rising, the power grid is responding to all electrification, manufacturing is returning, and robots and self-driving taxis are on the horizon.
The report states that hardware and infrastructure, after years of lagging behind software, have now become the market focus. Public and private equity are investing in computing, storage, power, robotics, manufacturing, and defense with an intensity not seen in decades, or even longer. In the report's words: atoms have returned.
AI is a generational platform shift, with unprecedented capital expenditure scale
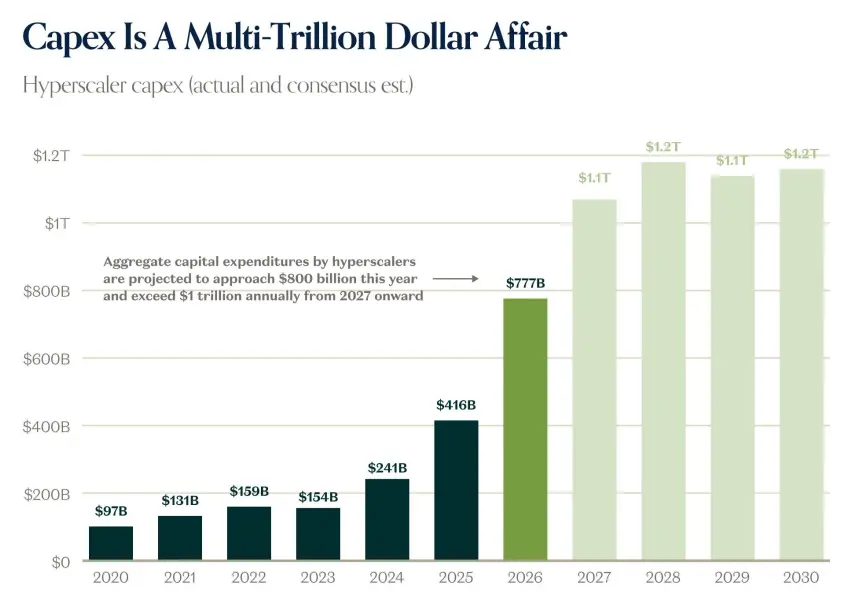
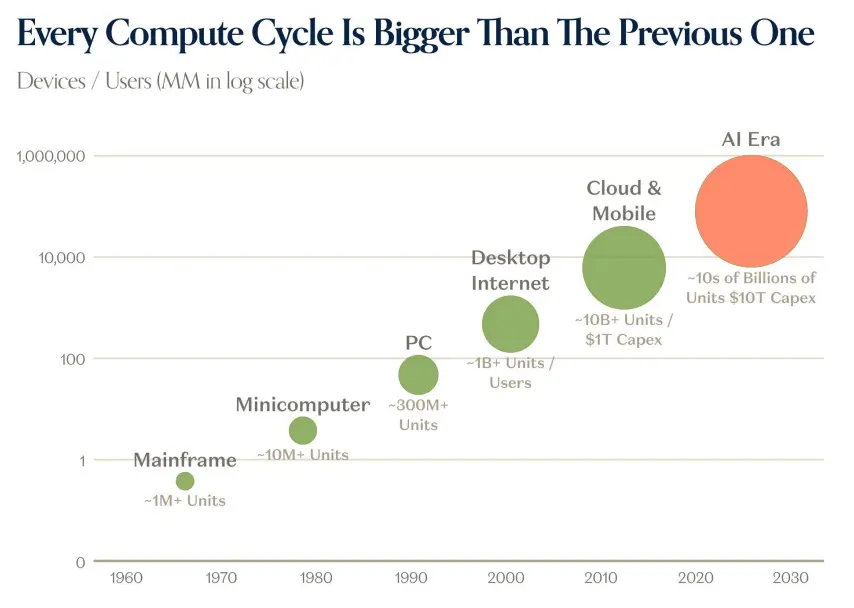
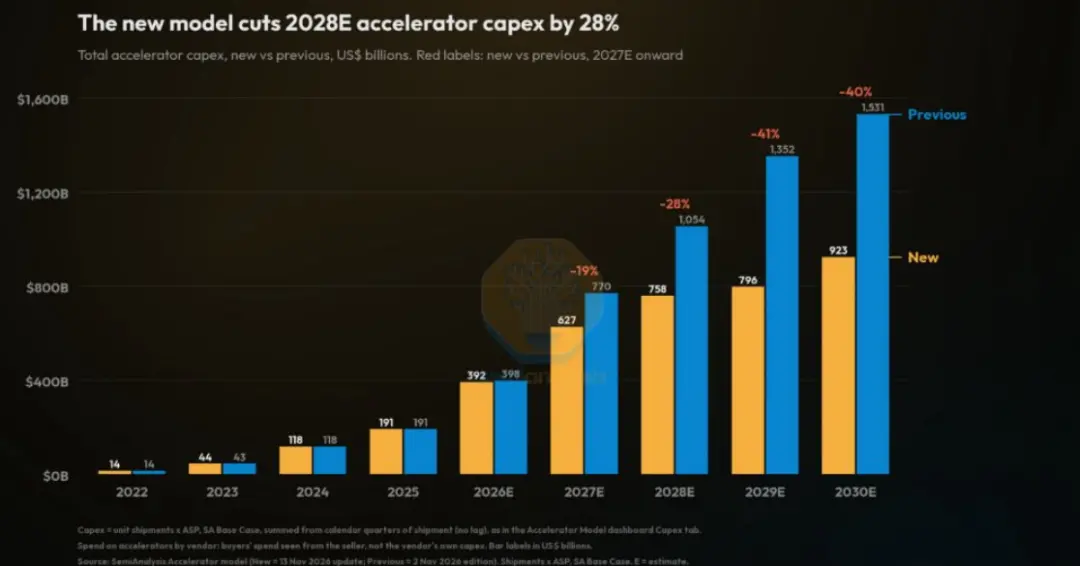
The report describes AI as a generational platform shift. Capital expenditures of hyperscale companies have risen from about $97 billion in 2020 to $241 billion in 2024, $416 billion in 2025; expected to be $777 billion in 2026, and exceed $1 trillion annually starting in 2027. The report states that each computing cycle is larger than the previous one: from mainframes, minicomputers, PCs, desktop internet, cloud and mobile, to the AI era, the scale of devices, users, and capital expenditures has increased by an order of magnitude.
The report points out that market forecasts for capital expenditures are consistently underestimated, with demand and prices continuously driving up investment. The proportion of capital expenditure to GDP is nearing or exceeding historical cycle peaks seen in railroads, oil and gas, and telecommunications. The free cash flow of hyperscale companies is being consumed by capital expenditures, and the report expects this pressure to continue until around 2028. As cash is fully utilized, the debt market begins to intervene: AI-related borrowing is expected to rise significantly in 2026, with longer terms. The report also states that the ROIC of hyperscale companies remains above the cost of debt and WACC, making their borrowing and investment financially sound at present.
Capital expenditures are also spilling over into the real economy. The report states that data center construction has led to an increase of over 300,000 jobs in construction and skilled trades, bringing wage premiums: salaries for positions such as facility managers, construction managers, and network engineers in data centers are higher than similar non-data center roles.
Capital expenditures are yielding results
The report states that the speed and scale of AI revenue growth are unprecedented. The combined ARR of OpenAI and Anthropic is expected to rise rapidly from the fourth quarter of 2024, reaching nearly $150 billion by the third quarter of 2026. The report shows that in 2026, the revenue scale of OpenAI and Anthropic is about $100 billion, exceeding the revenue of public software (excluding hyperscale companies) of about $63 billion. Cloud revenue backlog has doubled year-on-year, and the free cash flow of hyperscale companies is expected to significantly recover between 2029 and 2030.
The report also mentions that Neoclouds are growing rapidly, with companies like CoreWeave, Nebius, and Applied Digital showing steep revenue curves. Regarding concerns about GPU depreciation and obsolescence, the report states that the rental and residual values of old GPUs have not collapsed but have remained stable or even increased: rental prices and residual value data for B200, H200, H100, and A100 support this judgment.
In terms of adoption, the report believes that AI is still in its early stages. 69% of companies in the S&P 500 report having real-time AI deployments, but only 2% disclose any tracked metrics, and 0% break out and track metrics separately. There is still significant room for corporate AI spending: only 20% of organizations limit usage due to AI-related costs; most industries expect to increase AI spending. The report states that AI inference spending currently accounts for only about 0.3% of S&P 500 revenue, while cloud reached about 4% of IT budgets in its second year, indicating that AI's total addressable market is larger than IT budgets. On the consumer side, paid AI subscriptions have grown about fivefold since 2025, with average monthly household spending increasing, but search recommendation traffic remains small.
The report also references the mobile internet: semiconductors led the way, followed by infrastructure, and then software and services. The report believes that the AI version may follow a similar order.
The argument of GPU obsolescence is exaggerated
Directly related to hardware and capital expenditures is the supply and demand of computing power and the GPU lifecycle. The report points out that computing demand still exceeds supply. Previously, well-known bears questioned whether GPUs would become obsolete in three to four years and whether it was worth investing so much; what does the popularity of B200 mean for A100 deployed one or two years ago? At least for now, AI computing power demand has shifted upward, and A100 remains quite useful.
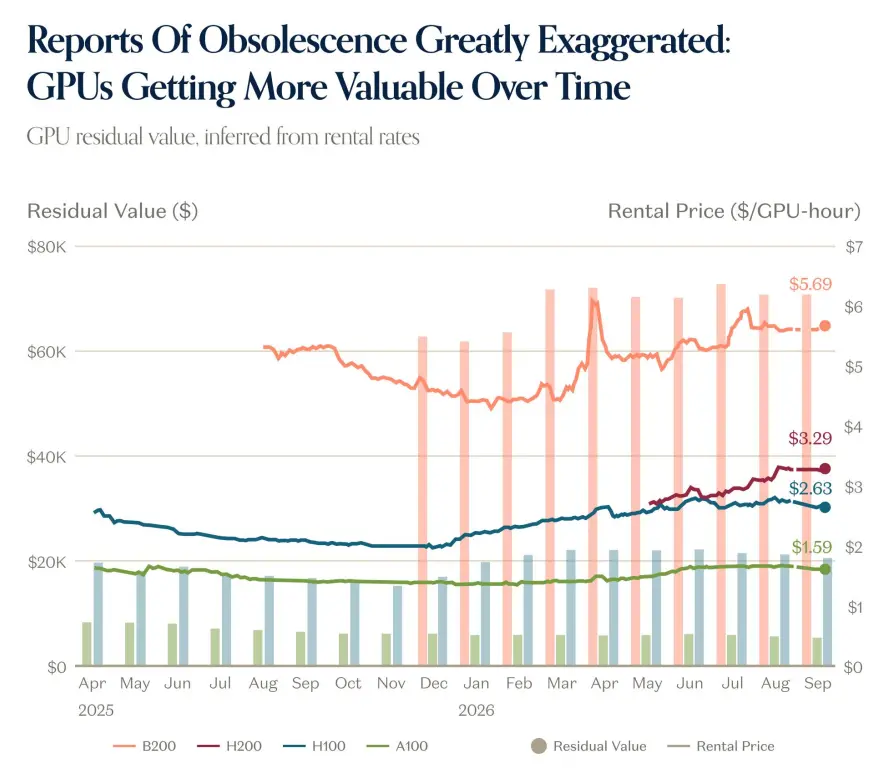
Typically, rental rates and GPU residual values decline over time, but this is not the case. As intelligence becomes cheaper, computing demand rises, and the prices of the latest chips increase, the prices of old chips also remain strong. The pricing of A100 is equal to or higher than the levels at the beginning of the year. The report believes that the story is far from over, but so far, advancements in computing and models are not zero-sum. Better and cheaper intelligence is accumulating value for the entire ecosystem, and old chips and models retain considerable value even after the "expiration date" set by bears.
At the same time, AI adoption is still relatively immature: widespread but shallow. Nearly 30% of S&P 500 companies report that AI has brought some "quantifiable impact," but only about 2% report any trackable metrics. In agent-based use cases, only a tiny fraction of users have deployed at scale. On the consumer side, as of April, only about 2% of American households were paying for some form of AI service; this number is now higher and growing, but overall it remains small. The report concludes that GPUs are running hot, while data shows that mature AI adoption and utilization are still in their early stages.
SaaS: proving itself, not the end
Returning from hardware to software, earlier this year, there were voices claiming that software was dead, and that AI could generate everything through "ambient programming," heralding the end of SaaS. The report states that reality is often more nuanced. There has indeed been a sell-off, but it is more discerning than what "the end" implies; AI or the threat of AI plays a role, but it is not the only factor.
Some revaluation of publicly listed software companies was long overdue. After the end of zero interest rate policies, technology companies exchanged growth for profitability. In 2022, the market was filled with high-growth, mostly unprofitable software companies; by 2026, the story had reversed: about 75% were profitable, but only about 30% grew by more than 20%. High interest rates were intended to make capital relatively scarce, so companies wisely shifted from loss-making growth to more self-sustainable, slower but steadier growth. This is reasonable in itself, but slow-growing companies will not receive high growth valuation multiples in the long term; the new "slow growth" norm eventually caught up with software. Not all companies are like this: fast-growing companies still trade at multiples in line with historical averages, although not at the peak of zero interest rates; but the number of such companies is decreasing, and the sector as a whole has been revalued. The report summarizes: software is not at its end, but it does need to "prove itself."
Private markets: value accumulates on the private side
The report believes that the private equity market is accumulating historic value. From the beginning of 2026 to the present, venture capital financing has reached approximately $72 billion, with the exit value supported by venture capital amounting to about $2.188 trillion. The scale of the largest private companies is unprecedented: the combined valuation of companies such as SpaceX, Anthropic, OpenAI, Databricks, Stripe, Revolut, Anduril, Cursor, Ramp, and Waymo reaches several trillion dollars. The report states that the value of the top five private companies has surpassed the total of technology IPOs over the past decade.
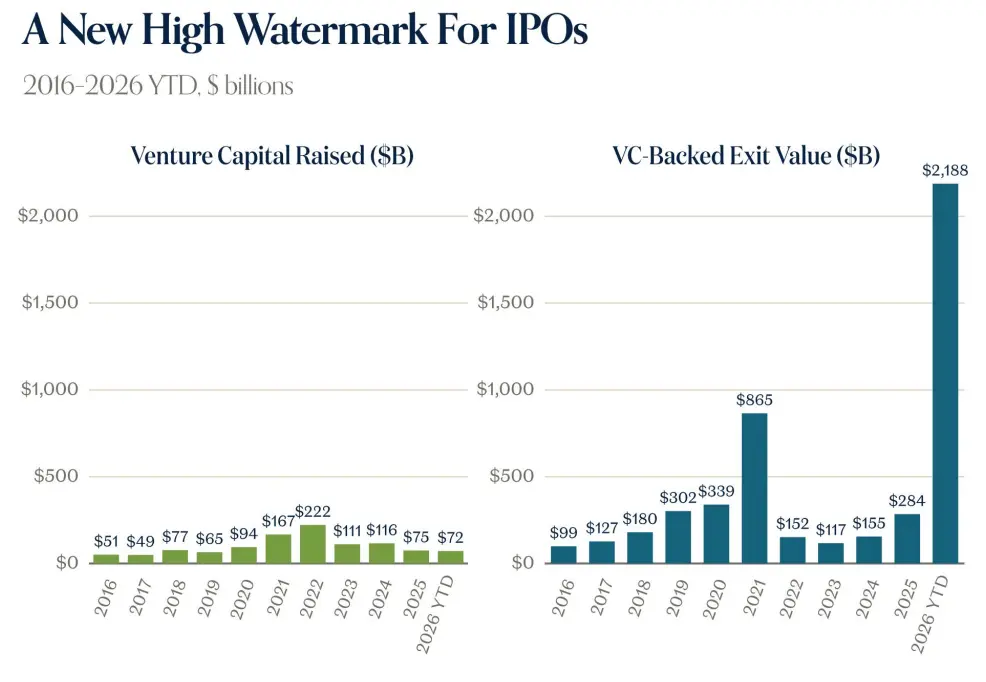
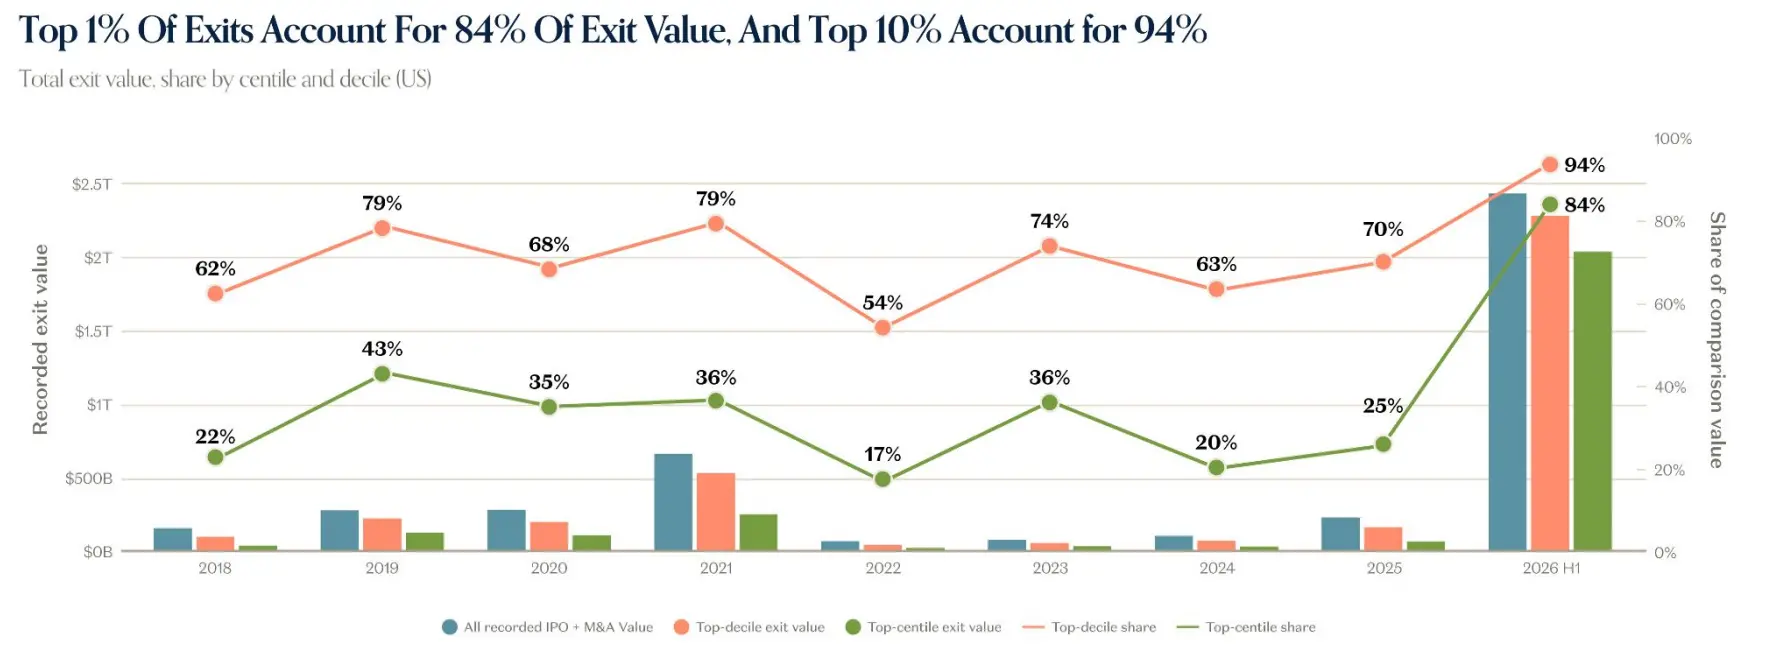
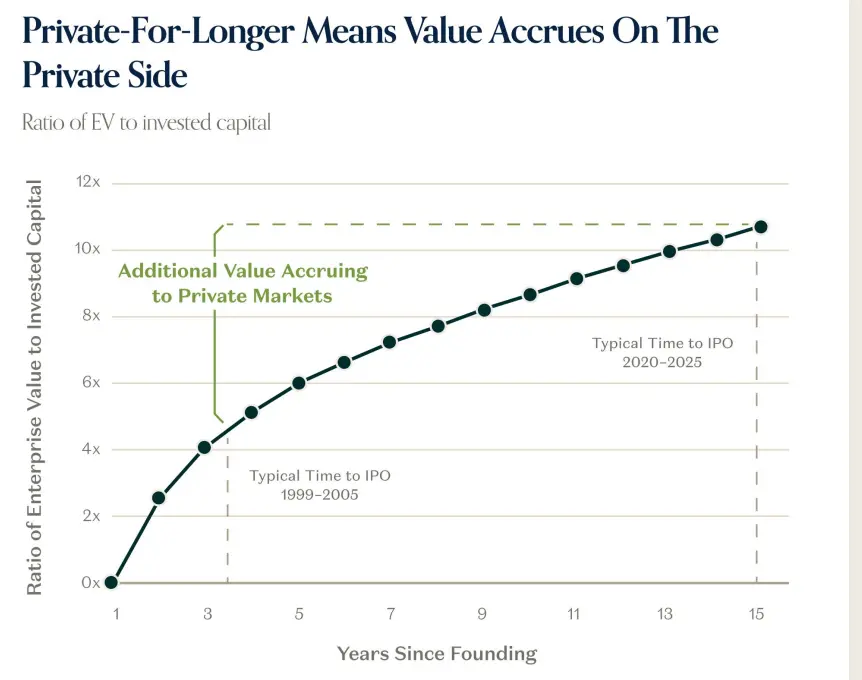
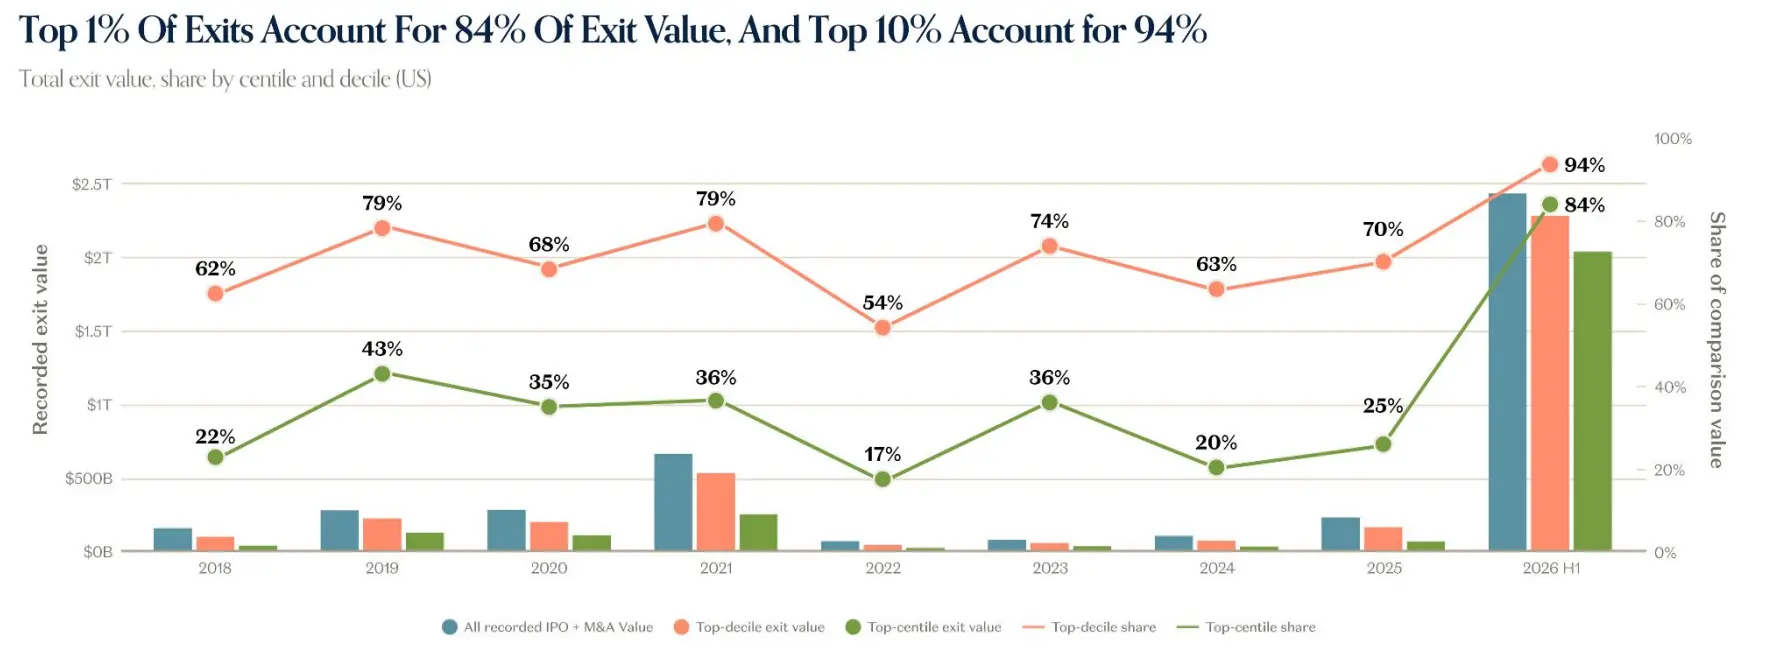
The report refers to this phenomenon as "Private-for-longer," meaning companies are going public later, accumulating more value during the private equity stage. The typical IPO time has extended from about 3 years between 1999 and 2005 to over 10 years from 2020 to 2025. The total valuation of active U.S. unicorns has reached $5.34 trillion, exceeding the $3.5 trillion of the Russell 2000. The power law effect of exit returns is also stronger: the top 1% of exits account for 84% of exit value, while the top 10% account for 94%.
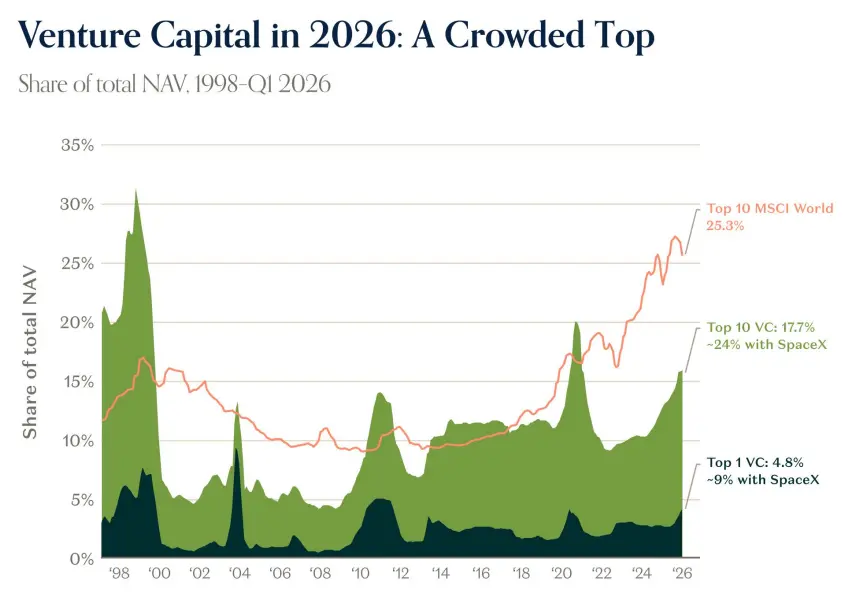
The secondary market also reflects this trend. The report states that the participation rate in employee stock transfers is below 60%, but the subscription rate has reached a historical high; discounts on stock transfers are small; the median price in the secondary market shows a 0% discount compared to the previous round, with the 75th percentile at a 23% premium and the 90th percentile at a 79% premium. The value growth of top VC portfolios far exceeds that of top public companies: from 2017 to 2026, the Top 30 VC portfolio index rose from 100 to 2,333, while the Top 10 public companies only rose to 542. VC concentration has increased, with the Top 10 VCs accounting for 17.7% of NAV, and about 24% if SpaceX is included. Meanwhile, the performance dispersion of VC funds has reached a historical high, with the gap between the top decile and the remaining funds widening.
The report states that after the end of the zero interest rate era, startups, like public companies, are shifting from growth to profitability. However, companies that successfully secure financing continue to maintain high growth rates, with growth comparable to or faster than during the zero interest rate peak. The share of AI in VC deal value has increased from 15% in 2016 to 86% in 2026. New unicorns are younger: the median age of new unicorns has decreased from about 7 years in 2019 to about 4 years in 2026, while the median age of all active unicorns has risen to about 15 years.
The report also states that in 2026, most VC-supported tech unicorns in the U.S. have revenues below $500 million, with growth not exceeding 20%, but with a short cash runway. Post-AI startups exhibit different growth curves: companies founded in 2022 have revenue growth in their fourth year approximately three times steeper than in previous years. Top AI applications grow about 5 times on a small base and about 2.5 times on a large base; the median year-on-year growth on a small base is 423%, while on a large base it is 150%.
Private company data is telling a macro story
The report states that private tech companies are increasingly becoming leading indicators of important economic issues. OpenRouter data shows that weekly token usage has increased from 0.5 trillion at the beginning of 2025 to 4.7 trillion in September 2025, and then to 126.2 trillion in September 2026, a year-on-year increase of about 27 times, having doubled twice since June.
The report believes that AI adoption is still "broad but shallow." The proportion of top decile users utilizing plugins and skills is far higher than that of typical enterprises: the plugin adoption rate is 95% for OpenAI, 21% for frontier companies, and 9% for typical companies; the skills adoption rate is 93%, 19%, and 3%. Databricks' Smart Router solves 92.3% of coding tasks at a cost of $2.13 per task, reducing costs by 35% and improving scores by 1.3 points. Kalshi has begun pricing forward GPU computing power. The report also states that inference providers have added about three-quarters of revenue but account for only about one-fifth of EV.
In retrospect, the report also provides a forecast. The a16z Growth team expects that AI will expand demand: enterprise and consumer adoption will become more mature and push into new frontiers such as robotics, biotechnology, health, and AD. Overall, technology is improving at an exponential rate. The report states that no one can predict the future, but given the speed and pace of change, this cycle will not resemble any previous cycle.
 Risk warning
ChainCatcher reminds readers to view blockchain rationally, enhance risk awareness, and be cautious of various virtual token issuances and speculations. All content on this site is solely market information or related party opinions, and does not constitute any form of investment advice. If you find sensitive information in the content, please click , and we will handle it promptly.
Popular articles





