








Wednesday Nvidia earnings focus: Without Jensen Huang, who can still tell a good AI story?
 Core Viewpoint

 NVIDIA's third-quarter report is expected to show revenue of $109 billion, with profit growth of about 90% year-on-year, but the sudden departure of Jensen Huang has overshadowed the performance itself. HSBC downgraded its rating from Buy to Hold, cutting the target price in half to $170; Morgan Stanley is concerned that the company may delay releasing its performance guidance for next year. The market is more focused on the selection of a permanent CEO, whether the target of 70% revenue growth for FY2028 can be achieved, and the risks associated with Rubin's mass production, AI customer financing, and export controls. This financial report will be a critical moment to test whether NVIDIA can break free from its reliance on Jensen Huang.
Author: Bu Shuqing, Wall Street Journal
NVIDIA will release its quarterly earnings report on Tuesday local time (Wednesday early morning Beijing time), but this time, the numbers themselves have taken a back seat. Jensen Huang's sudden departure has pushed this originally routine earnings release into one of the most watched moments on Wall Street in decades—what the market really wants to know is whether NVIDIA can continue the grand narrative about AI without him.
The market expects NVIDIA's revenue for the third fiscal quarter to reach $109 billion, with profits growing by 90%.
Jensen Huang resigned as President, CEO, and board member of NVIDIA on November 12, due to an investigation by the company's board regarding an extramarital affair, followed by two more reports of extramarital affairs involving NVIDIA employees. The company subsequently appointed Chief Financial Officer Colette Kress as interim CEO, but a permanent successor remains undecided.
Since the news broke, NVIDIA's stock price has fallen about 22% from October 29, with a decline of about 25% over the past month, bringing its valuation to a 15-year low, with a forward P/E ratio of only about 11 times.
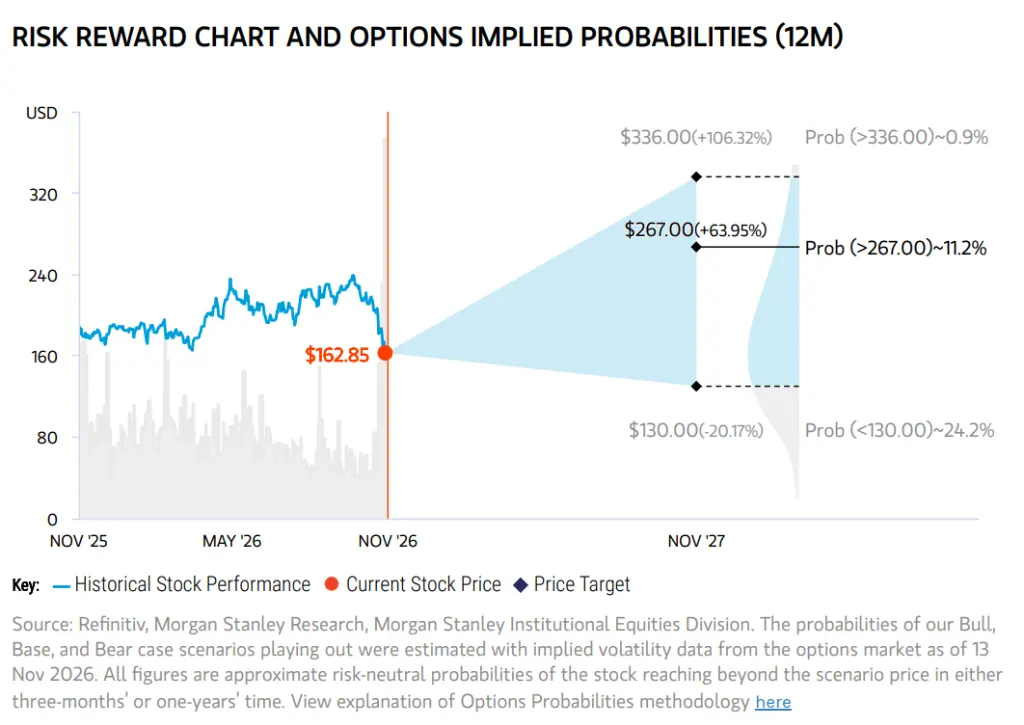
In this context, HSBC downgraded NVIDIA's rating from "Buy" to "Hold," significantly reducing the target price from $365 to $170; Morgan Stanley maintained an "Overweight" rating with a target price of $267, but admitted uncertainty about whether the company will provide guidance for next year's performance in this earnings report.
Morningstar analyst Brian Colello bluntly stated, "If NVIDIA's performance falls short of expectations or guidance is weak, we would be shocked," but he also pointed out that the fundamentals for this quarter are "somewhat secondary."
Performance Expected to Be Strong, But Guidance Is Uncertain
From a purely financial perspective, NVIDIA's fundamentals for this quarter are not in doubt.
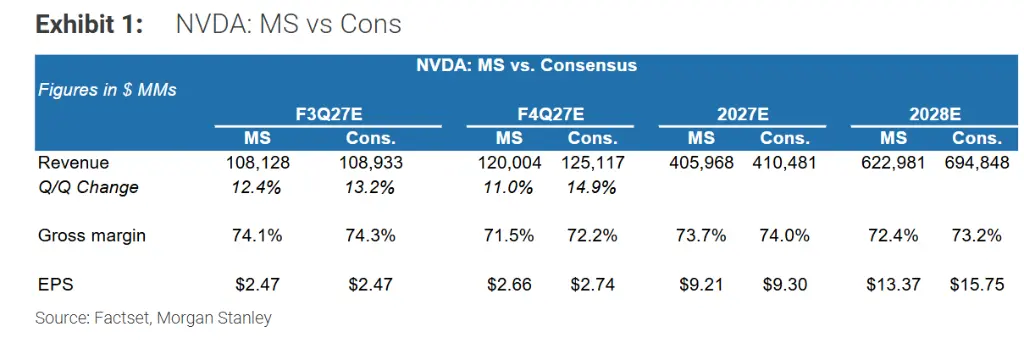
HSBC expects NVIDIA's revenue for the third fiscal quarter (ending October 2026) to be $113 billion, which is higher than the management's midpoint guidance of $108 billion and market expectations, with non-GAAP earnings per share expected to be $2.55, about 3% higher than the market consensus.
Morgan Stanley also stated that its channel research shows that business remains strong, even though some projects in Southeast Asia have slowed down, and supply is still unable to meet demand.
However, the market is more concerned about whether the company can reaffirm the medium- and long-term targets previously announced under Jensen Huang's leadership—including a revenue growth guidance of about 70% for FY2028 and a forecast of nearly 100% year-on-year growth in customer demand.
Morgan Stanley pointed out that its current revenue growth forecast for FY2028 is 52%, below the company's guidance of 70%, believing that this figure fully reflects the downside risks, but given the uncertainties surrounding the interim CEO's appointment and other factors, it remains unclear whether the company will provide guidance for next year in this earnings report. D.A. Davidson analyst Gil Luria indicated that management is likely to remain cautiously restrained when responding to questions related to Jensen Huang.
Succession Issues Dominate Market Sentiment, Valuation Reset Not Yet Over
Jensen Huang's departure means much more for NVIDIA than a typical CEO transition.
Over the past thirty years, he transformed NVIDIA from a startup idea in a California restaurant into a core AI infrastructure company with a market value of over $40 trillion, shaping the company's unique competitive advantage with his foresight of technological trends and flat management style—according to HSBC's report, Jensen Huang directly managed over 60 subordinates, with many decisions made personally by him.
Since Colette Kress took over as interim CEO, the long-term succession plan remains unclear, and NVIDIA's board has initiated a search for internal and external candidates.
HSBC believes that until a permanent successor is determined and demonstrates the ability to execute the existing product roadmap, there is limited room for stock price revaluation. The firm has significantly lowered its target P/E ratio from 25 times to 11 times (equal to the current valuation low) and clearly stated that the formal handover of the CEO and related organizational adjustments are not expected to have a substantial impact on the company's product development or competitive position before 2028.
Mark Malek, Chief Investment Officer at Siebert Financial, stated, "'Interim' means the real decision has not yet come, the investigation is still ongoing, making Tuesday's earnings call the most important in the company's history."
Three Core Issues: Demand, Supply, and Export Controls
In addition to succession issues, analysts and investors will focus on three aspects.
AI Demand and Financing Outlook: Morgan Stanley noted that after the midterm elections, the Democratic Party won victories on several anti-data center platforms, significantly raising concerns about land, power, and infrastructure bottlenecks. SoftBank (partner in NVIDIA's PORTS-Pike project) has written down $3.7 billion for power equipment. Additionally, emerging cloud computing companies like CoreWeave, Nebius, and IREN have collectively guided capital expenditures of about $100 billion for 2027, but their combined market value has shrunk by about $38 billion over the past month, and the tightening financing environment poses potential risks to NVIDIA's long-tail customer base.
Progress on Rubin Platform Mass Production: This quarter marks NVIDIA's first large-scale shipment of Rubin architecture products, previously expected to account for about 20% of data center revenue (approximately $20 billion). Morgan Stanley pointed out that key testing partner KYEC has lowered its performance guidance for two consecutive quarters, partly due to Rubin ramping up slower than expected, but analysts believe this will not have a significant impact on NVIDIA's revenue confirmation for this quarter.
Export Control Risks: HSBC conducted a sensitivity analysis on this. Based on the revenue distribution over the past six quarters, the U.S. accounts for about 69%, while other countries and regions account for about 31%. If a comprehensive export ban is imposed on other regions (resulting in a loss of about 11% of revenue), HSBC estimates that FY2028 earnings per share will decline by about 13% compared to the baseline scenario, with earnings per share in a bear market scenario at $13.57, about 14% lower than the current market consensus.
The Call Itself Is Cautiously Worded, Likely to Lack "Sparks"
Several analysts expect this earnings call to be the most closely watched in NVIDIA's history, but the actual information may be disappointing.
StoneX analyst Cody Acree stated, "The attention will obviously be higher, but I don't think there will be more substantive content to discuss; they won't respond to the specific details of Jensen Huang's resignation." Interactive Brokers Chief Strategist Steve Sosnick warned, "There are countless uncomfortable questions that may be thrown at NVIDIA, and wrong answers will be punished."
It is noteworthy that Jensen Huang previously did not make an opening statement during the earnings call but actively participated in the Q&A session and was known for his macro narrative on the transformative impact of AI. Morgan Stanley pointed out that under the new management structure, this broad expression of enthusiasm for AI may marginally recede.
Gabelli Funds portfolio manager Hendi Susanto holds a relatively optimistic view, believing that NVIDIA is no longer solely reliant on one executive, "The fast innovation culture he created has been integrated into NVIDIA's engineers and product roadmap, and at least for the next two years, we do not see any significant impact on NVIDIA's roadmap."
 Risk warning
ChainCatcher reminds readers to view blockchain rationally, enhance risk awareness, and be cautious of various virtual token issuances and speculations. All content on this site is solely market information or related party opinions, and does not constitute any form of investment advice. If you find sensitive information in the content, please click , and we will handle it promptly.
Popular articles





