Micron and SanDisk lead the decline, storage continues to adjust, what happened?
 Core Viewpoint


 This is driven by three overlapping shocks: the delayed decline after the South Korean holiday, the largest-ever buyback by Samsung and SK Hynix (approximately $40 billion) being terminated early, and Changxin Technology announcing a breakthrough in 4F² architecture, potentially leading South Korean giants by two years in unit architecture. The market paradox lies in the fact that despite fundamentals reaching historical highs, there is a sell-off, as investors have begun to price in the risks of a supply-demand reversal triggered by capacity expansion in 2027-2028.
Author: Dong Jing
The storage sector is experiencing a concentrated sell-off triggered by multiple pressures. Micron fell 3.88% on Monday, while SanDisk dropped even deeper by 5.97%. Both benchmark stocks have declined on six out of the last seven trading days, with Micron down nearly 20% from its June peak, nearing a technical bear market.
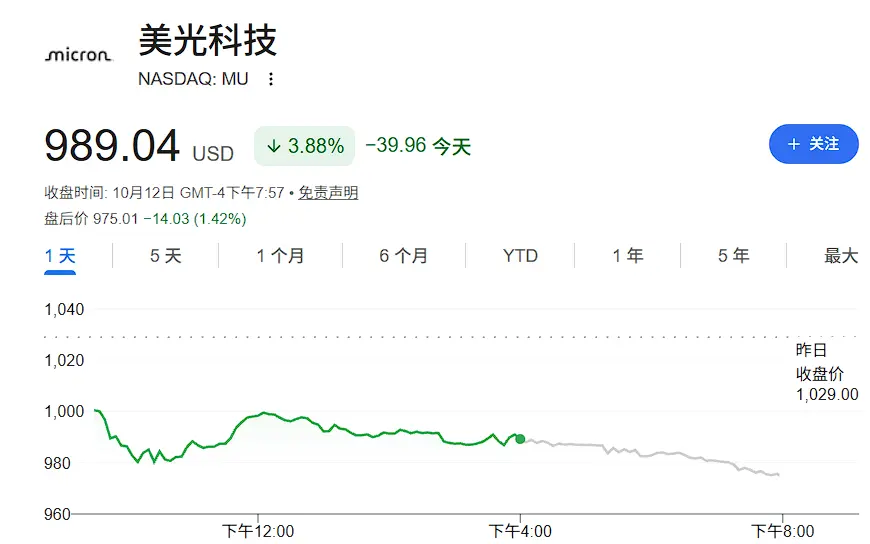
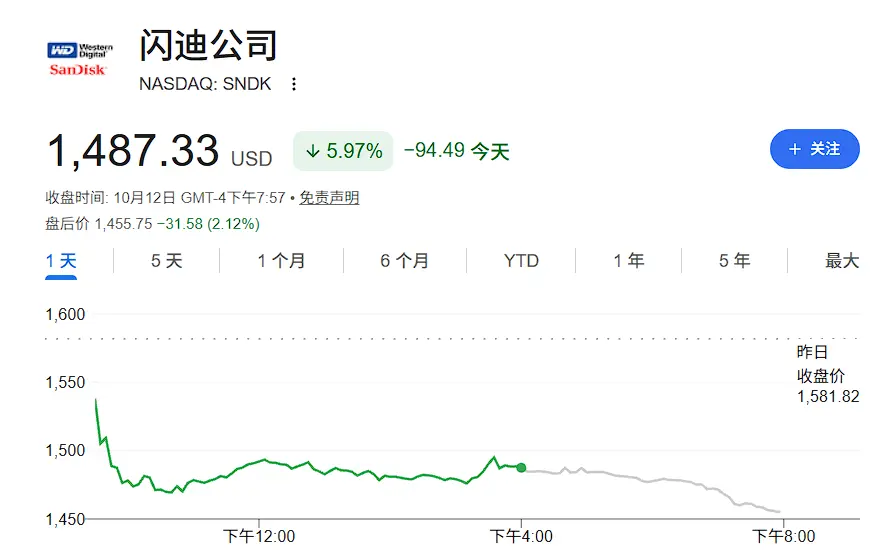
The catalyst for this round of adjustment comes from a triple impact: the Korean market's lagging correction after the holiday, the early end of Samsung and SK Hynix's largest-ever buyback plan, and Changxin Technology (CXMT) announcing key progress in its 4F² next-generation DRAM architecture in Shanghai, with plans to launch server memory products by the end of the year. Goldman Sachs EMEA trading head Rich Privorotsky summarized the situation as "storage remains the epicenter," pointing directly to the core market concern: despite the recent strong fundamentals, worries about peak earnings are suppressing valuations.
However, the paradox in the market is that the fundamentals of the storage industry have never been so strong, yet investors have shifted their focus to 2027-2028: by then, China's storage capacity will continue to expand alongside the new wafer fabs in Korea, potentially reversing the supply-demand dynamics. As Pictet's Jon Withaar noted, storage stocks "have become value stocks, and based on current earnings, valuations are cheap," but "retail investors and fast-money hedge funds are chasing growth, not value."
Korean Market Correction, Buyback Support Disappears
The Korea Composite Stock Price Index (KOSPI) plummeted 3.65% on Monday, closing at 6384.2 points, just above the 200-day moving average support level of 6376 points. The tech-heavy KOSDAQ fell by 4.8%, and the semiconductor index KRXSEMI dropped by 5.2%. SK Hynix and Samsung each fell about 4.5%, with Goldman Sachs' Seoul trading desk describing the day's trend as "a one-sided decline from the opening."
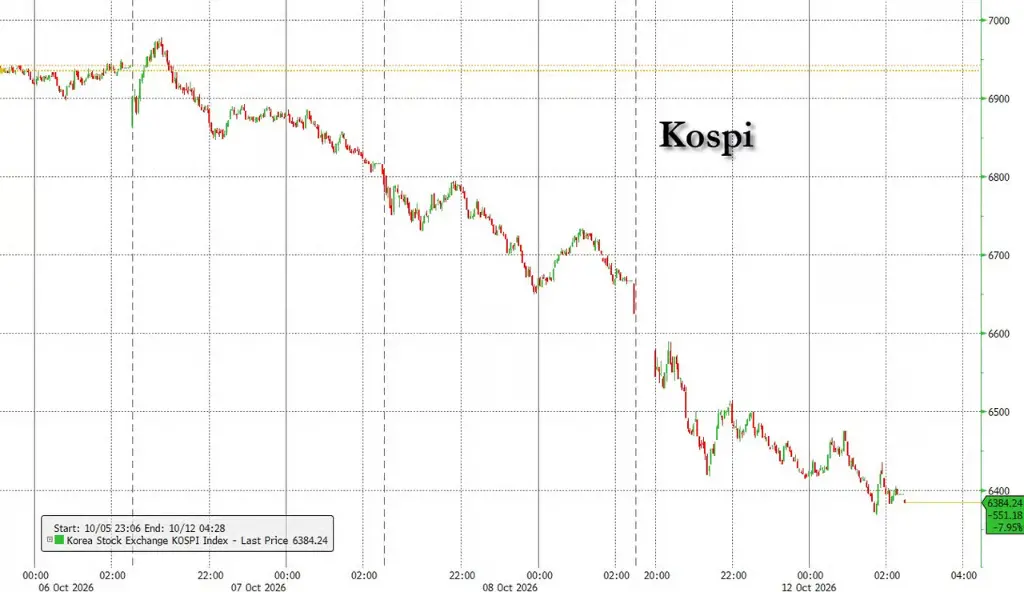
The direct reason for this correction is that the Korean market needed to digest the declines of U.S. chip stocks over the previous two trading days after the Korean holiday. Foreign investors have net sold for five consecutive days, with a single-day net sell in the tech sector reaching $1.3 billion, including $782 million in sales of SK Hynix and $415 million in sales of Samsung. Retail investors bought against the trend, net purchasing $710 million in Samsung, but Goldman Sachs pointed out that the net buying by retail investors is on a downward trend.
A deeper structural issue is the disappearance of buyback support. According to previous reports, Samsung and SK Hynix's combined buyback plan of about 55 trillion won (approximately $40 billion) — the largest in Korean history — ended several weeks early, with Samsung's buyback officially terminating on October 6. Over the three trading days following the end of the buyback, the KOSPI has cumulatively fallen about 8%. The KOSPI is currently down about 30% from its historical peak on June 22, with SK Hynix down even more at 45%.
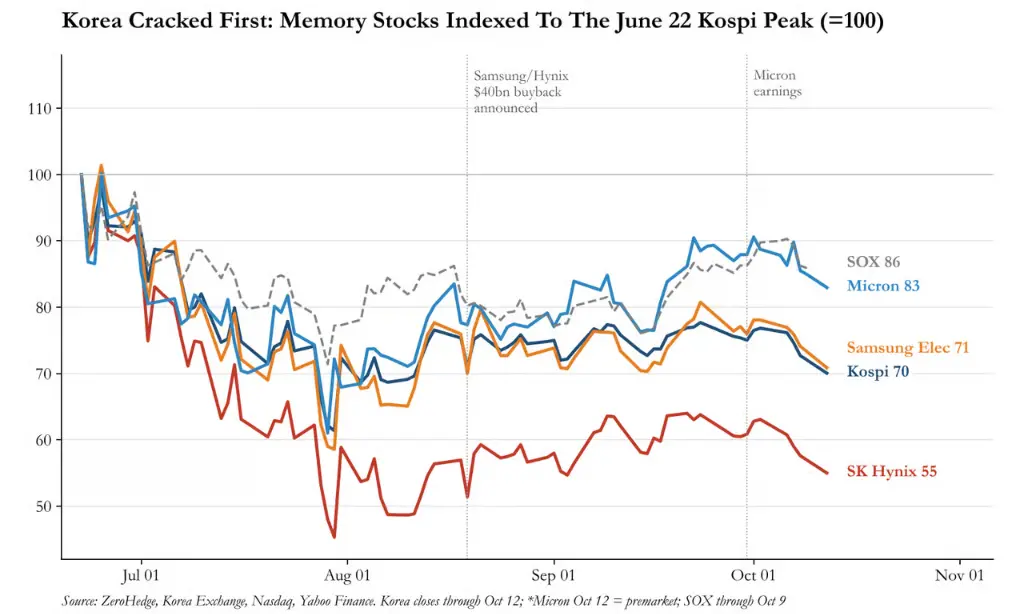
Analysts believe that the Korean market led the rise during the storage upcycle and also broke down first during the downcycle, potentially playing the role of a leading indicator again.
Changxin's 4F² Breakthrough, Long-term Supply Concerns Heat Up
News from Shanghai over the weekend became an important catalyst for this round of sell-off. According to the Shanghai Securities News, at the fourth Integrated Circuit and Chip Conference held on October 9-10, Changxin Technology's president, Cao Kanyu, announced that the company has made key progress in the development of the 4F² architecture and officially stated that it plans to launch a new generation of DDR5 RDIMM products that integrate 4F² architecture and advanced technologies such as hybrid bonding by the end of the year, directly targeting the server memory market.
The core significance of the 4F² architecture lies in the leap in density. The current mainstream in the DRAM industry is the 6F² architecture, where each storage cell occupies an area six times the minimum feature size. 4F² means that the area of each cell is reduced by about one-third, theoretically achieving about a 50% increase in storage density at the same wafer area and process node. The core innovation of Changxin's 4F² architecture is the self-developed VSG (Vertical Surrounded Gate) transistor, which enhances gate control capability through a vertically surrounded channel structure while addressing leakage and short-channel effects, and achieves area reduction through the vertical layout of transistors.
The leap from 6F² to 4F² essentially represents a fundamental transformation in the orientation of the transistor channel from horizontal to vertical layout, requiring the integration of a completely new process flow and cannot use the design and manufacturing systems from the 6F² era. Changxin also decouples DRAM from CMOS processes, achieving high-speed interconnection through wafer-level hybrid bonding, which is seen as a key turning point for DRAM technology moving from two-dimensional scaling to three-dimensional integration.
It is reported that Changxin has been conducting research and patent layout for 4F² since its establishment, with over 300 public patent families, reportedly leading its domestic and international peers. The company published papers related to the 4F² architecture in 2021 and has continued to disclose research progress in 2023 and 2025. In 2025, Changxin will also present a paper at IEDM, introducing the results of experiments validating wafer-level bonding of DRAM and CMOS on a 12-inch wafer platform.
For Samsung and SK Hynix, this timeline poses direct pressure. SK Hynix will not announce its 4F² roadmap until 2025, while Samsung aims to achieve mass production of DRAM based on this architecture below 10nm by 2028, according to Korean media The Elec. If Changxin delivers its 4F² DDR5 RDIMM products as scheduled by the end of the year, it will lead the two Korean giants by about two years at the unit architecture level.
Recent Strong Fundamentals, but the Market is Pricing Peak
The current fundamental data of the storage industry remains impressive, which is precisely the dilemma for the market — strong numbers have been fully priced in, and investors are beginning to discount longer-term risks.
Nanya Technology in Taiwan reported a third-quarter performance described by Goldman Sachs' Taipei trading desk as "another astonishing quarter": revenue reached NT$133.6 billion, a 62% quarter-on-quarter increase and a staggering 612% year-on-year increase; gross margin was 85.7%, up 6.2 percentage points quarter-on-quarter; operating profit margin was 80%; the mixed average selling price increased by over 60% quarter-on-quarter, with more than half of the increase coming from the reset of long-term contracts expiring in 2025. Management expects that contract prices can still achieve double-digit increases in 2027, with gross margins "expected" to remain above 80%.
However, Goldman Sachs' Taipei trading desk bluntly pointed out: "There has been a lack of sufficient catalysts recently to drive further revaluation." Samsung's operating profit nearly increased ninefold in the third quarter, which should have reignited the storage market, but instead triggered a sell-off — this itself indicates the position of market expectations.
Goldman Sachs Prime Book data shows that last week, the U.S. information technology sector shifted from being the most net bought sector in four out of the previous five weeks to the most net sold sector, and it was the fastest selling pace in seven weeks, with technology hardware, storage and peripherals, and semiconductors being the most concentrated sub-sectors for selling.
The pressure facing storage stocks does not come from a deterioration in fundamentals, but from the market's early pricing of the cycle's peak.
At the same time, the current core narrative in the market has shifted from "how strong are recent fundamentals" to "what will the supply-demand dynamics look like in 2028." Goldman Sachs' Korea research team listed six key points of interest for Samsung's earnings call on October 29, with the top concern being: whether the company will clearly state, like Micron, that storage supply will become tight in 2028.
Additionally, Acer CEO Jason Chen previously stated that "the supply shortage issue has completely disappeared," and he expects storage prices to peak around mid-2027. Acer, HP, and ASUS have adopted Changxin chips in their PC products. ASML is reportedly raising spare parts prices for Korean customers by about 10%, and Samsung and SK Hynix have accepted this price increase, which will take effect in January 2027.
This week, the market will also welcome several important milestones: TSMC will announce its earnings on Thursday, ASML will release its financial report on Wednesday, and SEMICON West will also be held — these events will provide new directional signals for the chip sector.
 Risk warning