AI plummets, and the first to drop is not Nvidia—optical communication fell nearly 10% in a single day, with Broadcom's CEO pointing directly at capital bottlenecks

 On the same day, a warning about capital came from the CEO of Broadcom in Singapore, and three days ago, news about the new structure progress of Changxin Storage came from Shanghai. One of these matters points to where the money on the demand side comes from, while the other indicates whether the pattern on the supply side will change. In the early trading session on Tuesday, KOSPI and Nikkei both declined, extending this round of adjustment to the Asia-Pacific region. This article will break down these two clues in the order of transmission.
Introduction: On Monday (October 12), U.S. markets observed Columbus Day, with the bond market closed and the stock market operating normally. The AI hardware sector underwent concentrated adjustments at low levels. The Philadelphia Semiconductor Index fell by 2.67%, marking four consecutive days of decline, pushing last Friday's divergent market trend toward a clearer direction. On the same day, a warning from the CEO of Broadcom regarding capital was reported in Singapore, while three days earlier, news of Changxin Storage's new architecture progress emerged from Shanghai. One points to where the money on the demand side comes from, while the other questions whether the supply side's landscape will change. In the early trading on Tuesday, both KOSPI and Nikkei fell, extending this round of adjustments to the Asia-Pacific region. This article will break down these two clues in order of transmission. 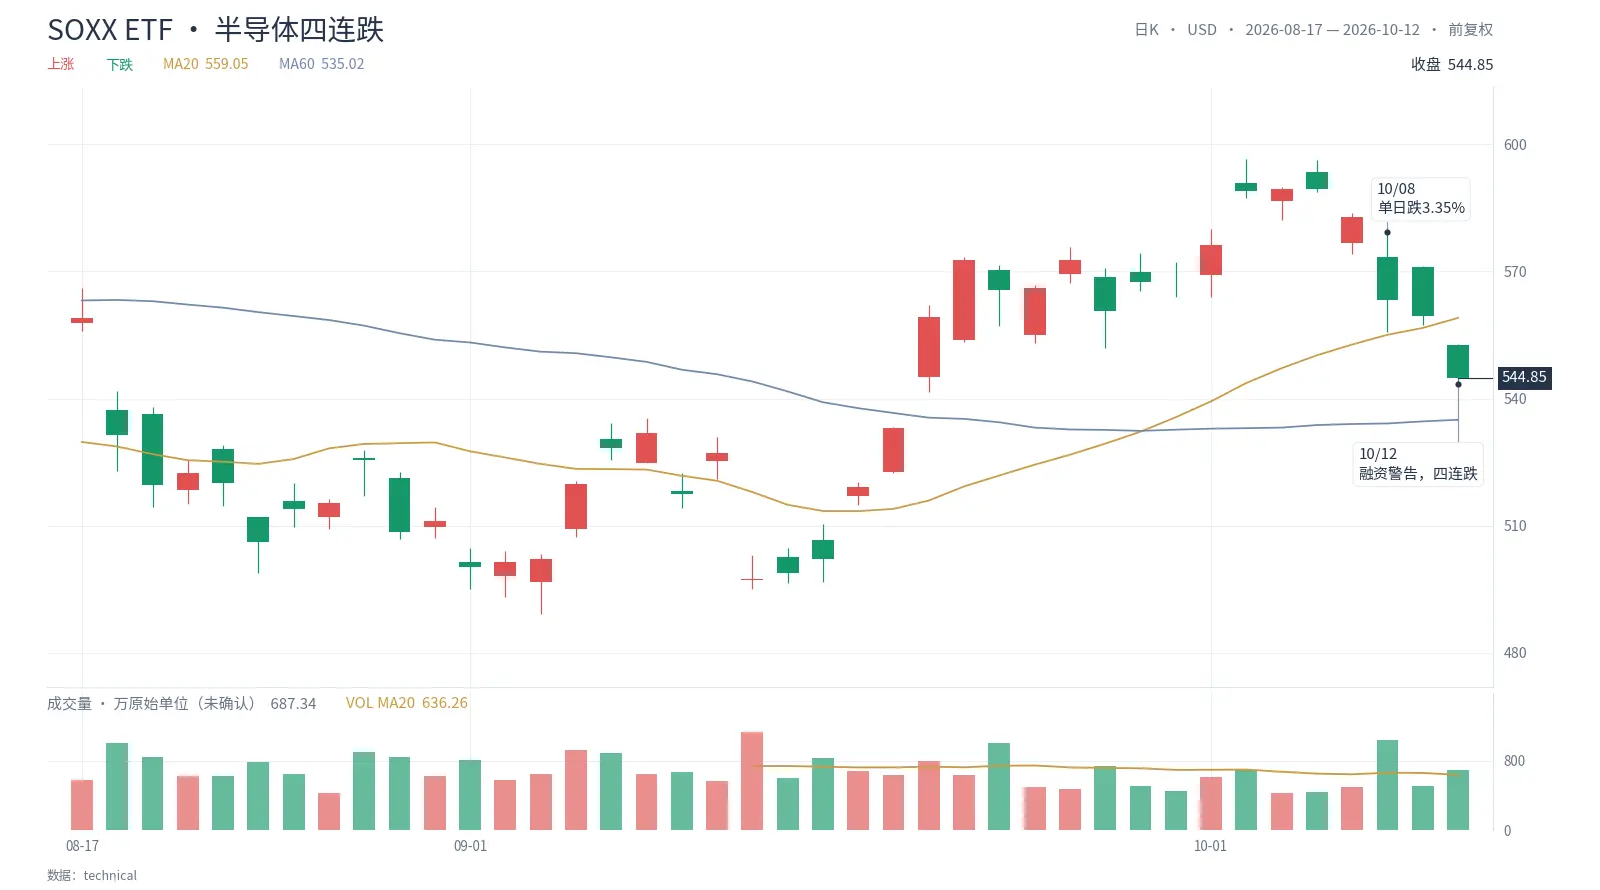
I. The Path of One Day's Sell-off
First, let's look at the daily structure. The SOXX ETF fell by 2.60% on Monday, following declines of 1.12%, 3.35%, and 0.69% in the previous three trading days, erasing all gains from the early October rebound over four consecutive days. Among the 30 constituent stocks of the Philadelphia Semiconductor Index, 28 fell, closing at 12,236.79 points.
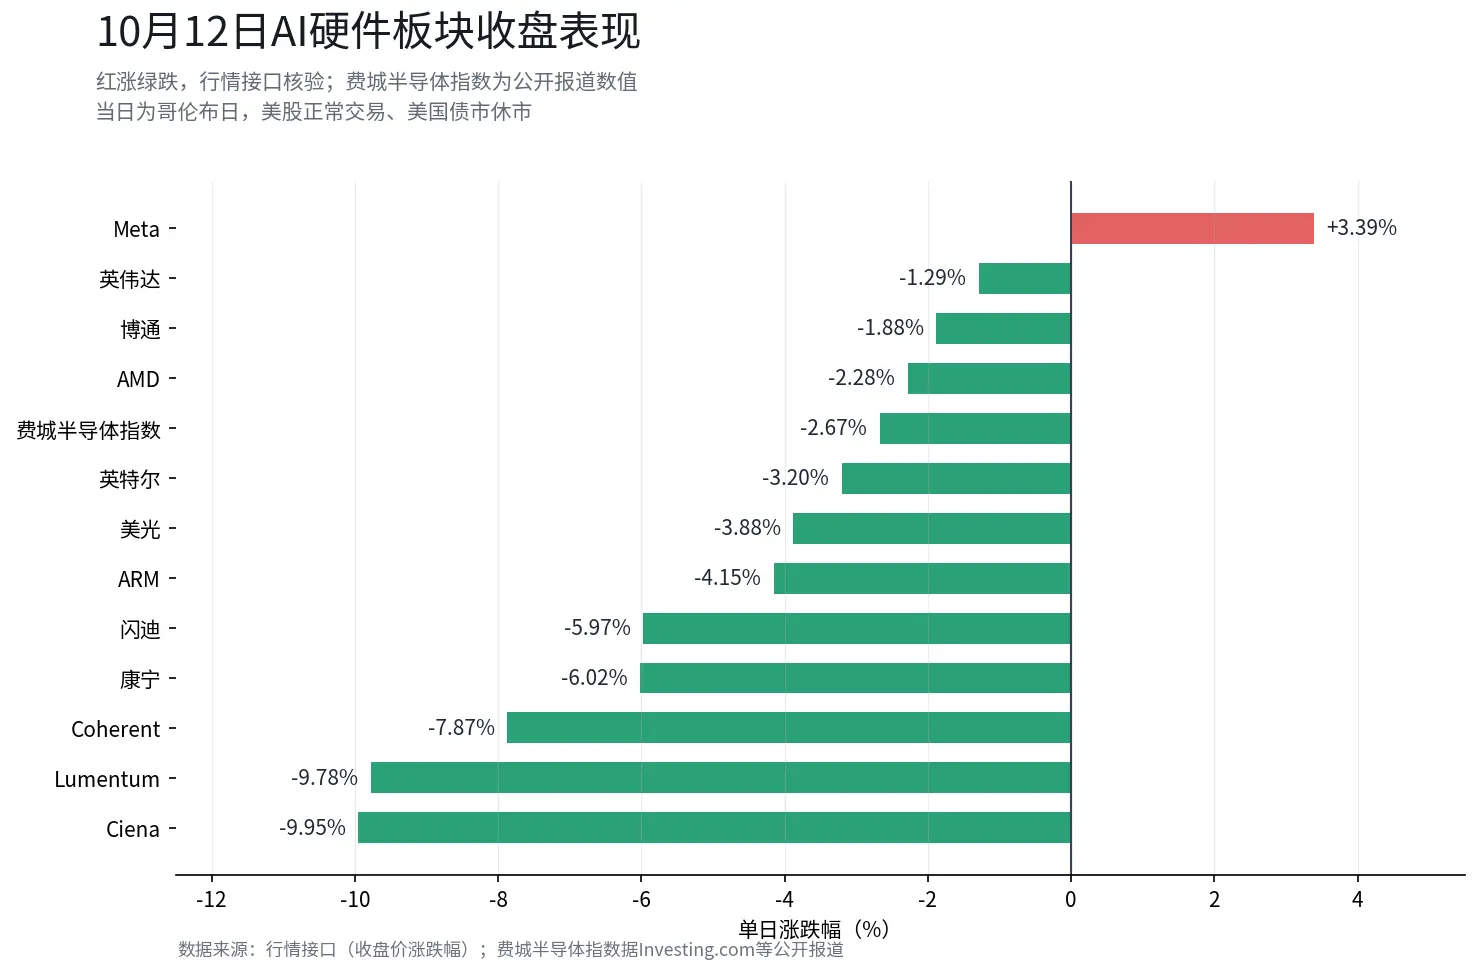
The ranking of declines itself conveys information. Optical communication and storage components led the decline, with Ciena down 9.95%, Lumentum down 9.78%, Coherent down 7.87%, Corning down 6.02%, SanDisk down 5.97%, Micron down 3.88%, ARM down 4.15%, Intel down 3.20%, and AMD down 2.28%. Meanwhile, NVIDIA fell by 1.29%, Broadcom by 1.88%, while Meta rose against the trend by 3.39%. A verifiable interpretation is that panic along the AI chain is transmitted from the segment most reliant on capital expenditure to the core segment, consistent with the pattern observed after the revenue expectations of OpenAI were exposed on October 8. If subsequent earnings reports show that optical communication orders remain strong, this interpretation will need to be revised, as it would indicate that the market is pricing financing conditions rather than a contraction in demand.
II. Why the CEO of Broadcom's Statement is Significant
On Monday at the DBS Bank Asia Future Summit in Singapore, Broadcom CEO Hock Tan stated that as the entire industry competes to build infrastructure, financing may become a greater obstacle to AI expansion, potentially surpassing shortages in semiconductors, memory chips, or electricity. According to CNBC, his exact words were, "[I believe] the biggest constraint is capital." He also mentioned that shortages in wafers and memory are easing, and that there is no contraction on the demand side. According to reports from Yahoo Finance and others, Broadcom still believes that the demand for computing infrastructure will continue to exceed supply. Intel CEO Pat Gelsinger expressed a similar viewpoint.
The weight of this statement lies in its redefinition of the issue from a shortage of chips to a shortage of money. Another noteworthy detail, as reported by Reuters citing Anthropic's IPO documents, is that Broadcom has agreed to provide up to $42 billion in loans to Anthropic, which is approximately one-third of the latter's $125.2 billion chip procurement commitment. The fact that chip companies are beginning to provide financing directly to customers is itself a footnote indicating that financing issues are entering the pricing center.
III. What Changxin is Redefining
On October 10, Changxin Technology President Cao Kanyu announced at the Fourth Integrated Circuit and Chip Conference in Shanghai that progress has been made in the development of the 4F² DRAM architecture, with plans to launch DDR5 RDIMM products for servers that integrate 4F² architecture and hybrid bonding technology by the end of the year. The 4F² architecture compresses the storage cell area to about two-thirds of the traditional 6F² structure. According to public reports, some commentators believe that its roadmap is about two years ahead of similar architectures from Samsung. It is important to emphasize that, according to TrendForce, this is still a development progress and product goal, and not a mature product aimed at customers.
The impact of Changxin's news should be read in the context of the storage industry's prosperity. Demand remains extremely strong, with TrendForce predicting that conventional DRAM contract prices may rise by 10% to 15% quarter-on-quarter in the fourth quarter, and NAND flash may rise by 15% to 20%. Micron's financial report released on September 30 showed that its revenue for the fourth quarter of fiscal year 2026 was $54.23 billion, a year-on-year increase of about 379%, with total revenue for the fiscal year reaching $133.19 billion, more than three times that of the previous year; Samsung Electronics' third-quarter operating profit forecast set a record. On the supply side, Goldman Sachs judges that the likelihood of new DRAM supply before the fourth quarter of 2027 is extremely low. Against this backdrop, Changxin's progress primarily changes not this year's supply-demand gap, but the expectations for the supply landscape after 2027, potentially adding a variable that needs to be priced into the long-term pricing of companies like Micron and SK Hynix.
IV. From Cash Flow to Bonds: A Shift in Pricing Logic
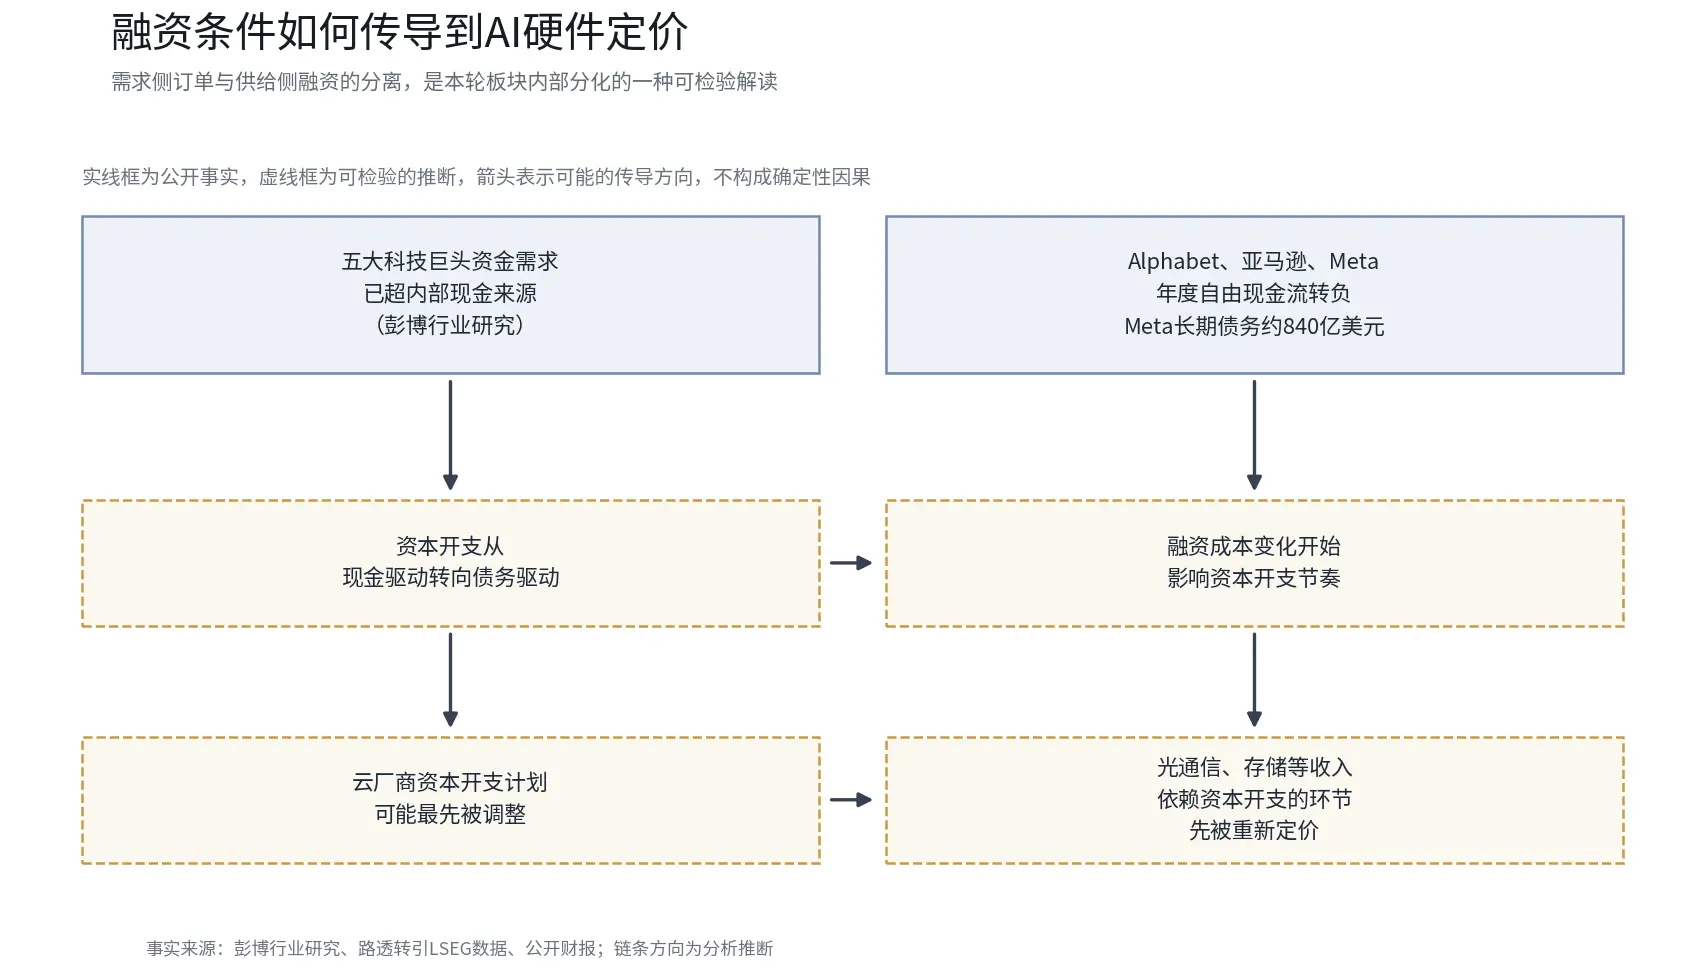
The implicit premise of AI capital expenditure over the past two years has been cash-driven, with tech giants covering expenditures with their own cash flow, and financing conditions not entering pricing. This premise is beginning to loosen. According to Bloomberg Industry Research, the funding needs of Meta, Amazon, Alphabet, Microsoft, and Oracle have exceeded internal cash sources, and they will rely more on the bond market over the next two years, with leverage levels trending upward. Among these, Alphabet, Amazon, and Meta's annual free cash flow has turned negative, with Alphabet's second-quarter free cash flow at negative $5.9 billion, marking the first quarterly negative since its IPO in 2004, and Meta's long-term debt reaching $84 billion. According to Reuters citing LSEG data, the five major AI companies have issued about $220 billion in bonds this year, and Goldman Sachs estimates that the five major buyers will issue about $250 billion in bonds by 2026.
As capital expenditure shifts from cash-driven to debt-driven, the environment where the 10-year U.S. Treasury yield operates around 5.3% begins to directly participate in pricing, and changes in financing costs may affect the rhythm and order of capital expenditure. From the readings above, this round of sell-off is more likely to reflect expectations of marginal tightening in financing conditions rather than a contraction in AI demand itself, with different implications for valuation. If subsequent earnings calls from cloud vendors begin to discuss financing rhythms rather than computing gaps, the above interpretation will be validated; otherwise, it will need to be revised.
Next Steps
In the short term, there are four observation points. First, the wording of cloud vendors' earnings call, as guidance on capital expenditure and financing statements can explain issues better than quarterly profits. Second, the production rhythm of Changxin's 4F² DDR5 RDIMM; the end-of-year release is just the first step, and the capacity ramp-up in 2027 will determine the extent of changes in the supply landscape. Third, the visibility of orders from optical communication companies; a combination of strong orders and weak stock prices indicates that the market is pricing financing conditions. Fourth, the sustainability of the Asia-Pacific market; KOSPI has fallen for five consecutive days, and foreign capital has continuously net sold, with the performance of Samsung and SK Hynix being a direct reading of sentiment in the storage chain. To what extent has repricing been factored into the market remains to be observed.
Data Explanation
Market: Philadelphia Semiconductor Index, SOXX, and individual stock price changes, market interface verification, closing on October 12.
Index and Asia-Pacific Market: Public reports, with Asia-Pacific data from October 13 trading session.
Statements from Broadcom and Intel CEOs: October 12 at the DBS Bank Singapore Summit, as reported by CNBC, Reuters, and Yahoo Finance.
Changxin Storage: Conference speech on October 10, as reported by Yicai and TrendForce.
Storage and Financial Aspects: TrendForce, Micron's financial report, Goldman Sachs, Bloomberg Industry Research; the approximately $220 billion bond issuance data has not been independently verified.
Disclaimer: The content of this article is for general information and market commentary only, compiled based on publicly available information as of the time mentioned in the article. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other individuals cited in this article represent the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it be the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when necessary. BIT's Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted jurisdictions.
 Risk warning