








Alibaba plans to spin off Pingtouge for a Hong Kong IPO: 10 billion in revenue, 560,000 units shipped, valuation difference of 66 billion USD?
Introduction: Alibaba's Chip Business Approaches the Hong Kong Stock Market, Next Step is to See Who is Willing to Price It
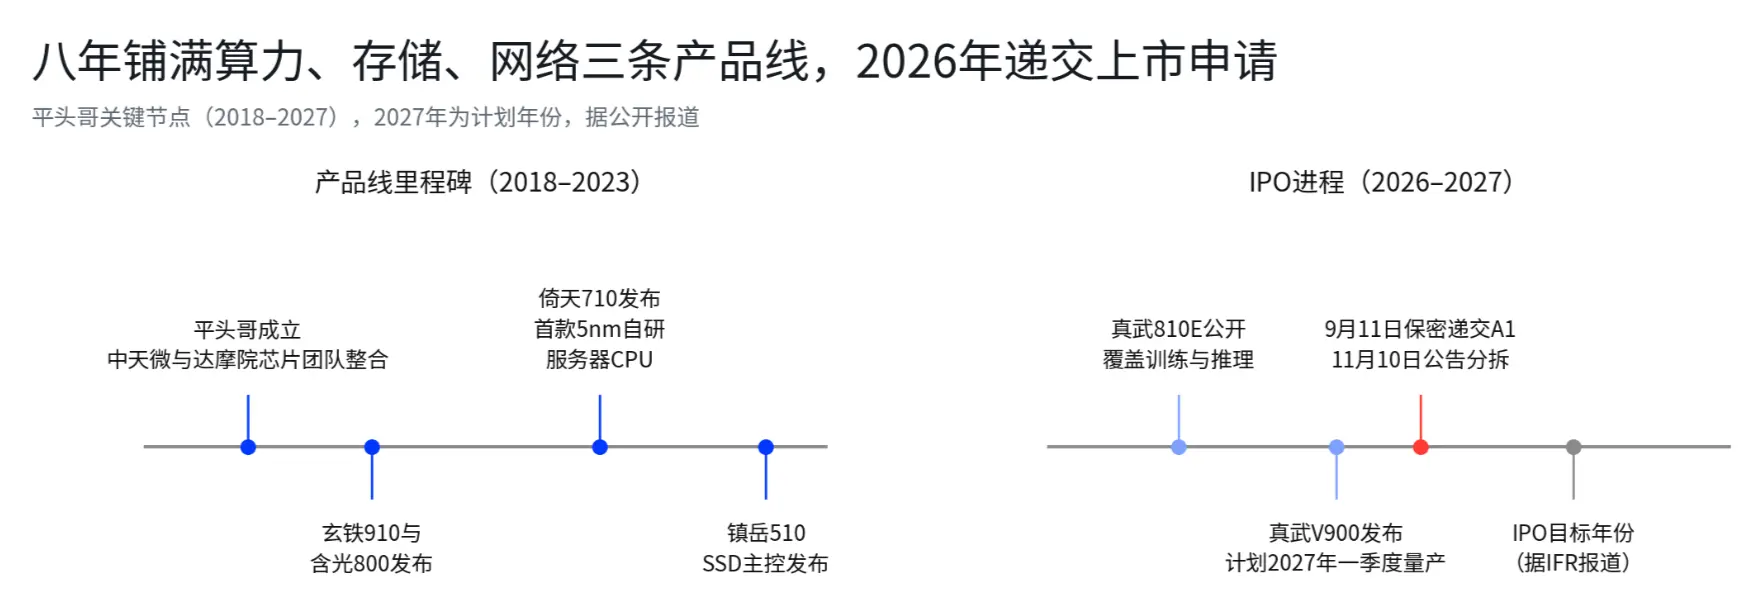
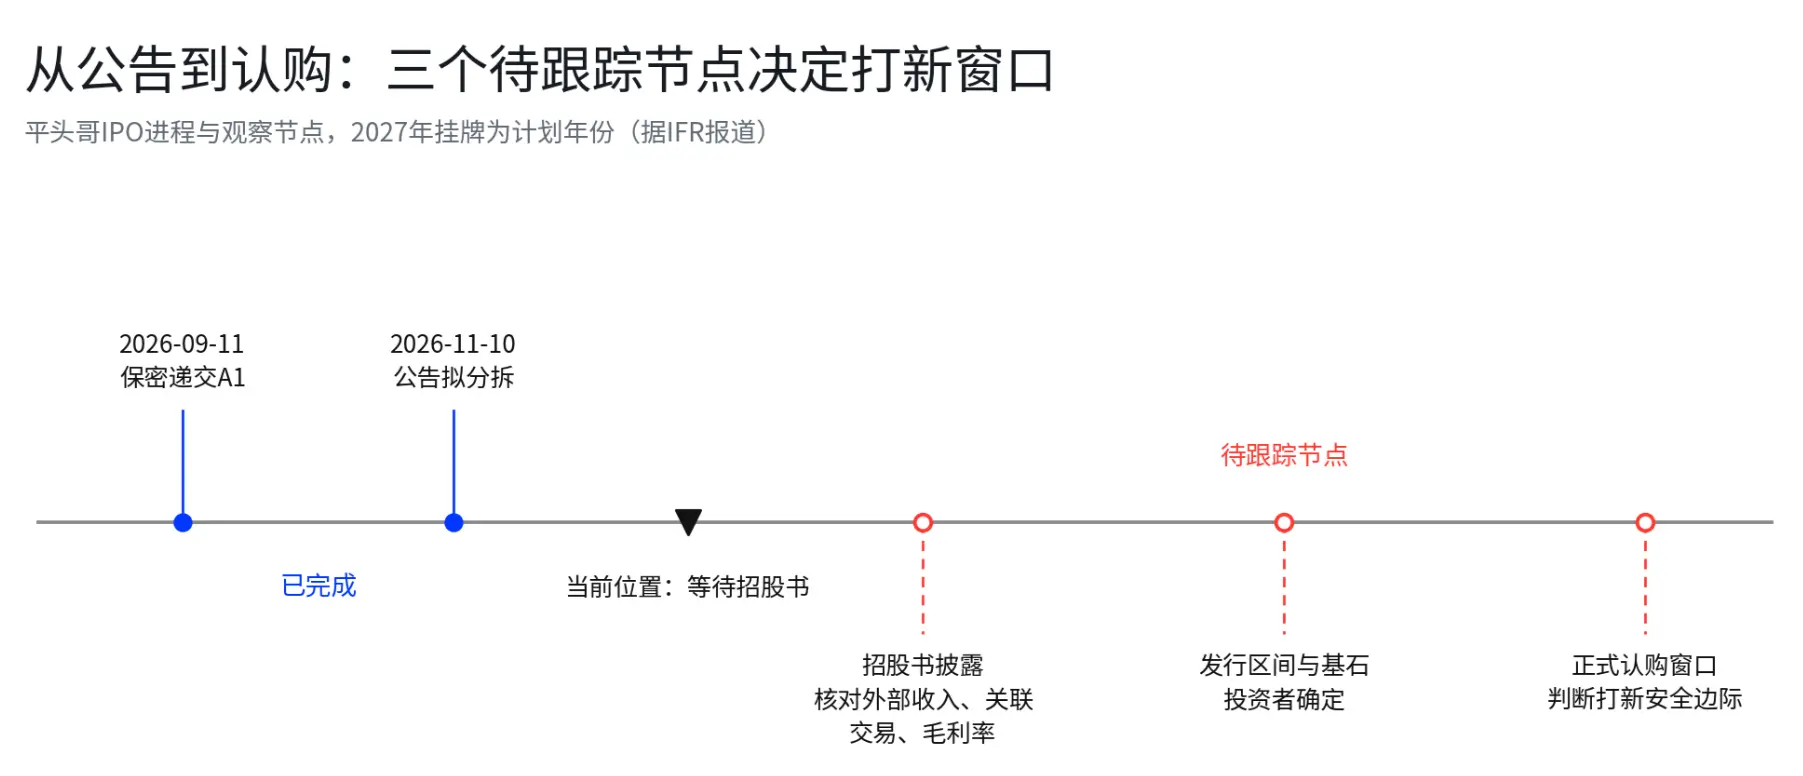
On the evening of November 10, Alibaba-W (09988.HK) announced that it plans to spin off its wholly-owned subsidiary T-head (Shanghai) Technology Co., Ltd. for an independent listing on the main board of the Hong Kong Stock Exchange, which has confirmed that the spin-off can proceed; T-head previously submitted a confidential A1 listing application on September 11. From its establishment to preparing for the listing, T-head has taken about 8 years.
The company is named after the honey badger, originally positioned for chip design, and now its products cover AI computing, server CPUs, SSD controllers, smart network cards, interconnect chips, and RISC-V processor IP. The company's annual revenue exceeds 10 billion yuan, and the Zhenwu series AI chips have already transitioned from product validation to large-scale commercialization. The highlights of T-head's IPO focus on "how much the products can sell for, how independent the customers are, how much profit can be retained, and how much valuation the capital market is willing to give."
For the Hong Kong stock market, this is also an event worth putting on the watchlist in advance: if it ultimately lists, the Hong Kong stock market's domestic computing power sector will gain a new chip company covering computing power, storage, and networking, and the market will obtain a more direct reference for the pricing of domestic AI chips.
I. The Stock Exchange Confirms the Spin-off, T-head's IPO Enters Substantial Advancement Stage
The information that has been confirmed is quite clear. Alibaba submitted a spin-off proposal according to the 15th application guideline of the Hong Kong Stock Exchange listing rules, and the Stock Exchange has confirmed that the spin-off can proceed. T-head submitted the A1 application form confidentially on September 11, 2026, planning to apply for H-shares to be listed and traded on the main board of the Hong Kong Stock Exchange, and intends to conduct a global offering of H-shares, including a public offering in Hong Kong and a placement to institutional and professional investors.
This spin-off does not involve "selling" T-head; after the independent listing, Alibaba will continue to maintain control, and T-head will still be a subsidiary of Alibaba. This has two direct implications for the company itself: on one hand, after the independent listing, the revenue, customers, R&D investment, and profitability of the chip business will gain clearer capital market pricing; on the other hand, Alibaba Cloud, Qianwen, and other internal ecosystems can still provide application scenarios and computing power demands, meaning T-head is not completely detached from its original ecosystem.
As for the fundraising scale and listing time, current market information is still in the expectation stage. According to IFR reports, this issuance aims to raise 2 to 3 billion US dollars, targeting a listing in 2027. What can be confirmed now is that "the IPO process has started," but the issuance scale, issuance price, and listing valuation are not final results; the next document that truly determines the value of the new shares will be the prospectus.
II. Revenue Exceeding 10 Billion is Not Just a Story: Zhenwu Chips Have Entered Large-Scale Commercialization
The most valuable change for T-head currently is that its business has transitioned from "chip R&D" to "chip sales." According to disclosures from the company's earnings call, T-head's annual revenue exceeds 10 billion yuan, and the cumulative shipment of the Zhenwu series AI chips has surpassed 470,000 units; media statistics indicate that as of April 2026, the cumulative shipment of the Zhenwu series is about 560,000 units, and as of June 2026, it has served over 650 enterprise customers, with external commercial customers accounting for over 60%.
If this commercialization trend can be further validated in the prospectus, then T-head will be significantly different from early chip companies that rely solely on technology stories to support their valuations: it already has revenue, shipments, and customers, and has entered a real procurement cycle.
The product side is also continuing to iterate. Public information shows that the Zhenwu 810E is equipped with 96GB HBM2e memory, 700GB/s inter-chip interconnect bandwidth, and has been used in some Alibaba Cloud Wan card clusters for training and inference of large models. The next generation Zhenwu V900, to be released in September 2026, will have memory increased to 216GB, inter-chip interconnect bandwidth reaching 1200GB/s, and is officially claimed to have three times the computing power of the previous generation, with plans for mass production in the first quarter of 2027.
For IPO valuation, the significance of the V900 lies in its growth logic: if the V900 can be mass-produced as planned and generate revenue, T-head has the opportunity to prove that its growth does not rely entirely on existing products but can continuously raise the revenue ceiling through the new generation of chips. This will directly affect the central valuation the market assigns to it.
III. From AI Chips to RISC-V, T-head Sells a Complete Product System
Another advantage of T-head is that its business is not limited to AI acceleration chips. Currently, the company's data center products cover the Zhenwu series AI chips, Yitian 710 server CPUs, Zhenyue 510 enterprise SSD controllers, Panmai smart network cards, and ICN interconnect chips; on the terminal side, there are also the Xuan Tie series RISC-V processor IPs, with cumulative shipments exceeding 6 billion units and over 400 ecosystem partners.
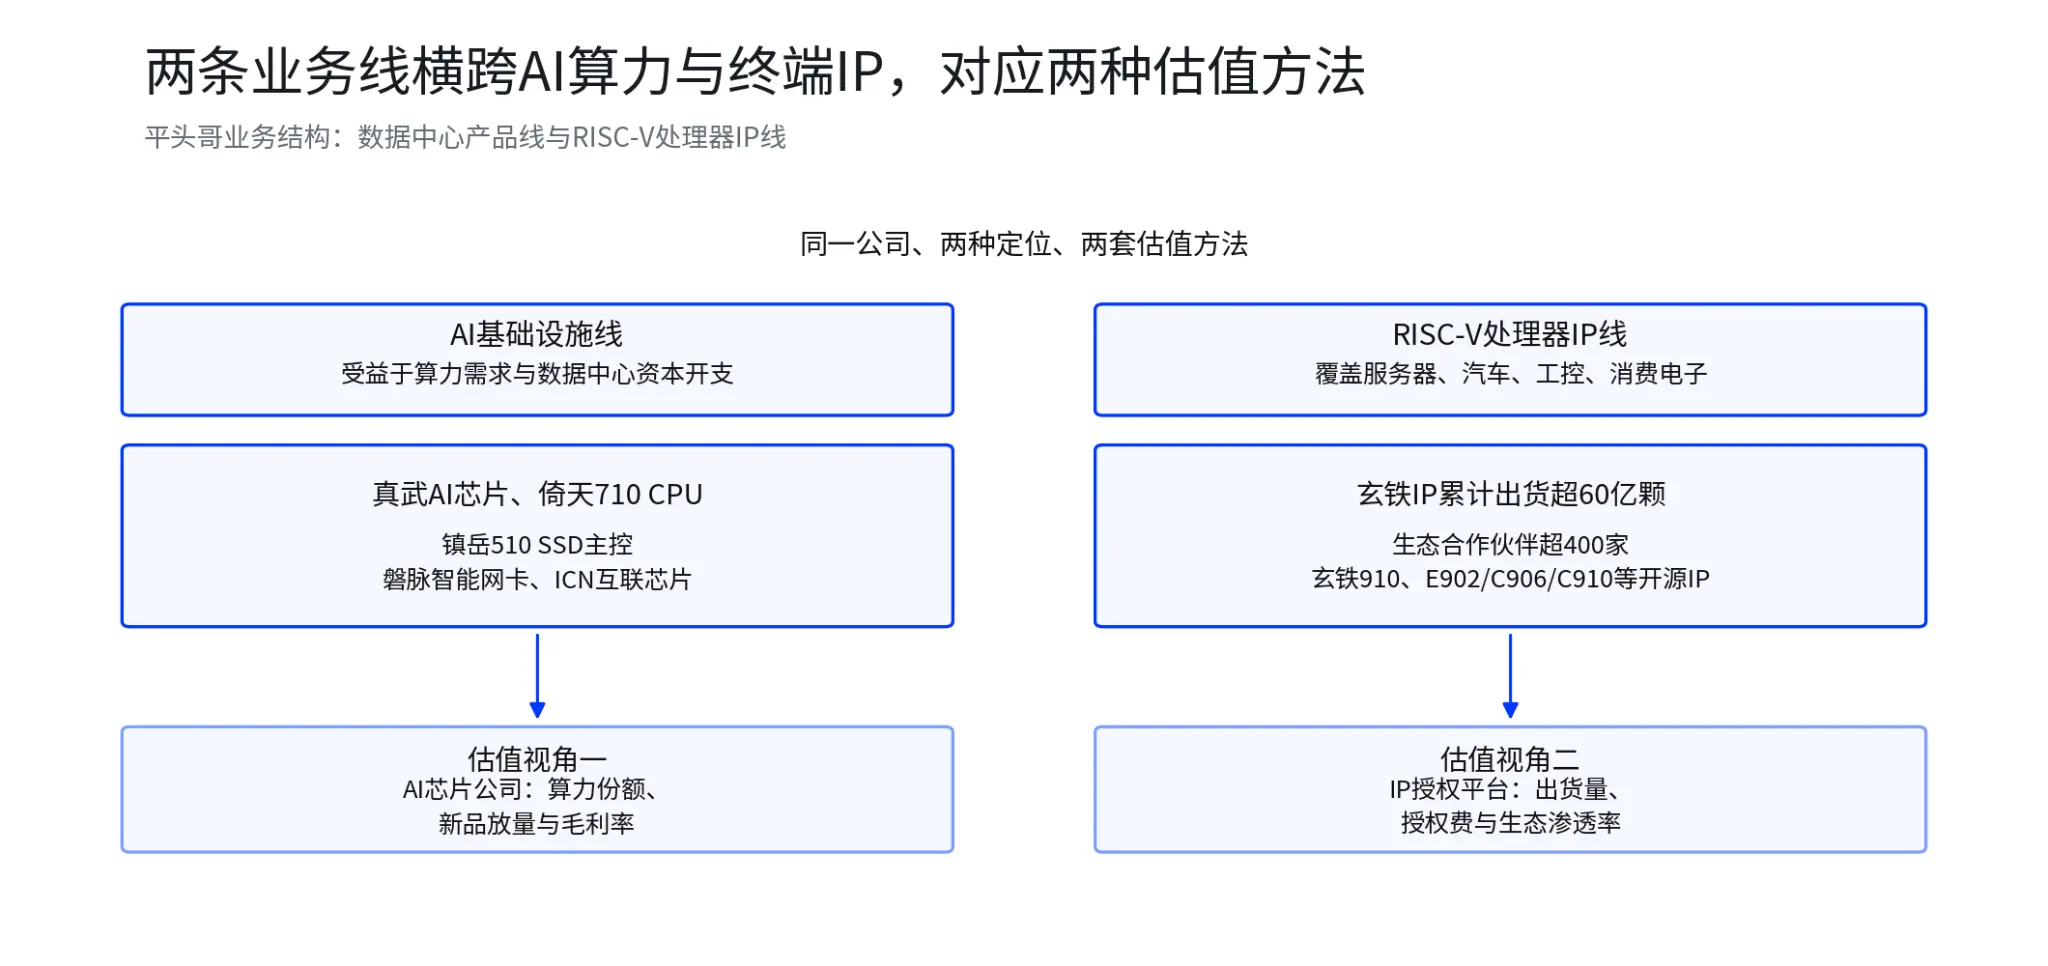
This means that T-head's business model actually spans two lines: one is AI infrastructure, directly benefiting from computing power demand and data center capital expenditures; the other is RISC-V processor IP, covering a broader terminal market including servers, automotive electronics, industrial control, and consumer electronics.
For Hong Kong stock investors, this business structure is worth noting, as it determines whether T-head will ultimately be regarded by the market as an AI chip company, a comprehensive chip platform, or a computing power infrastructure asset within the Alibaba ecosystem. Different positioning corresponds to different valuation methods.
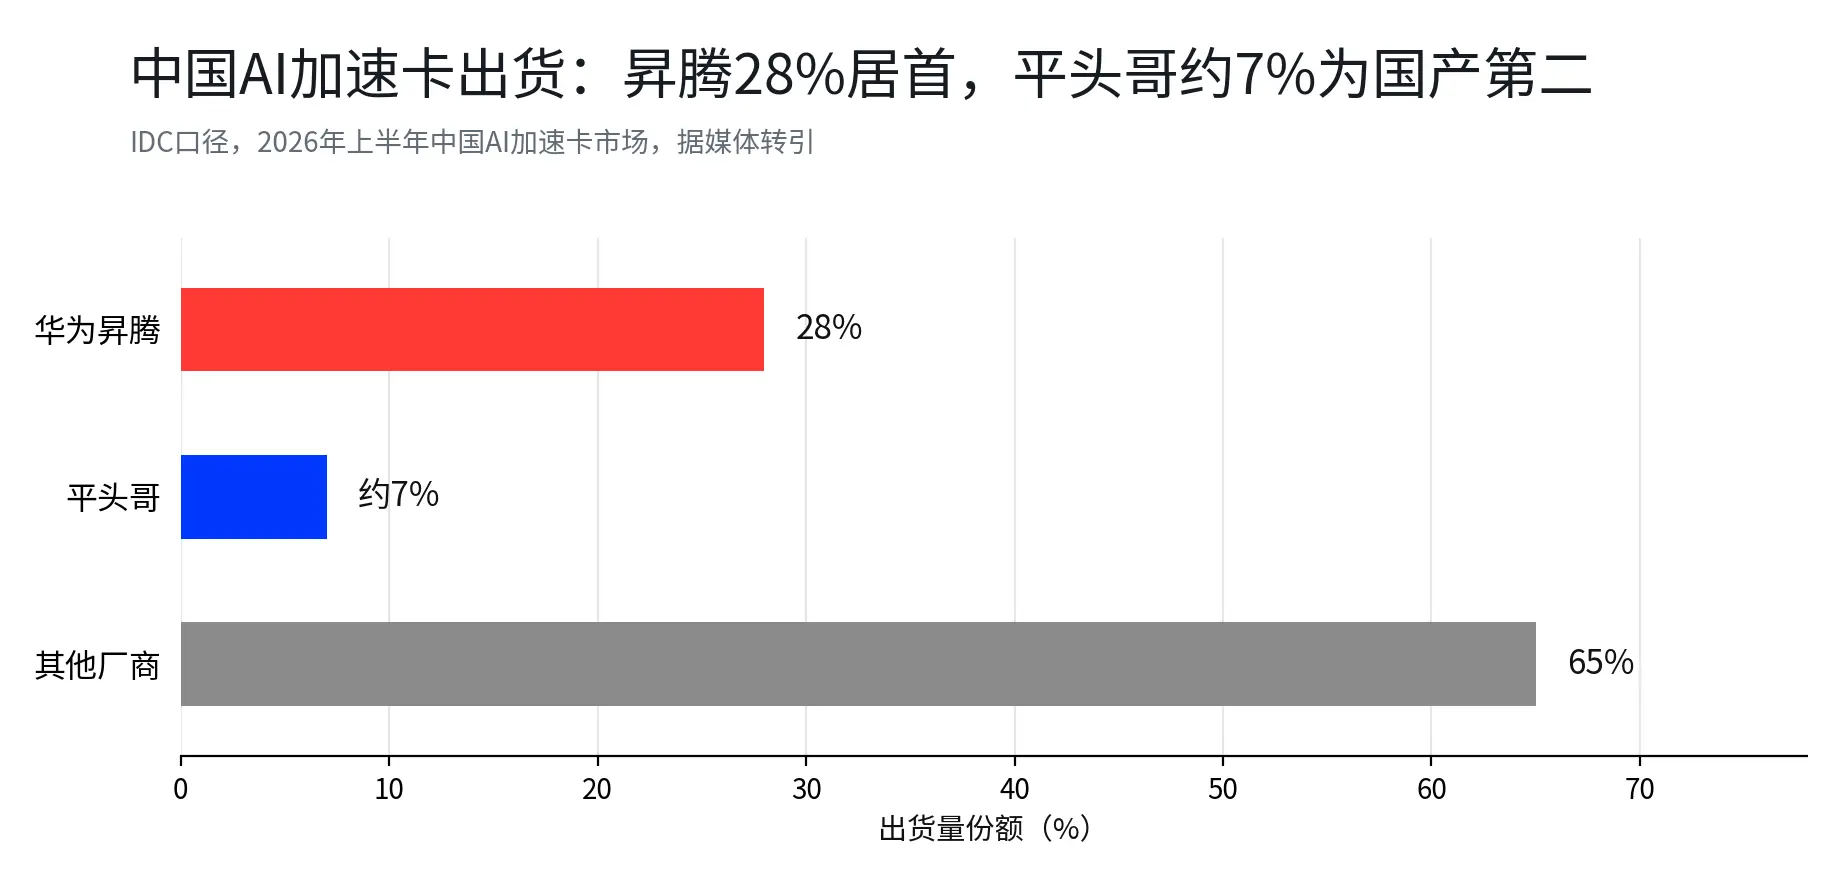
In terms of AI infrastructure, there is already third-party data available for market position reference. According to IDC data (as cited by the media), in the first half of 2026, T-head's shipment share in China's AI accelerator card market was about 7%, ranking second among domestic players, only behind Huawei's Ascend at 28%.
IV. The Real Valuation Mystery: From 20 Billion to 86 Billion USD, Why is There a 66 Billion USD Difference?
Currently, the market's expectations for T-head's valuation vary greatly. According to the 21st Century Business Herald, the valuation range given by professional institutions is about 20 billion to 30 billion USD; JPMorgan's estimate range in January this year was 25 billion to 62 billion USD; other media reported that Morgan Stanley's valuation range is about 28 billion to 86 billion USD. The highest and lowest differ by 66 billion USD.
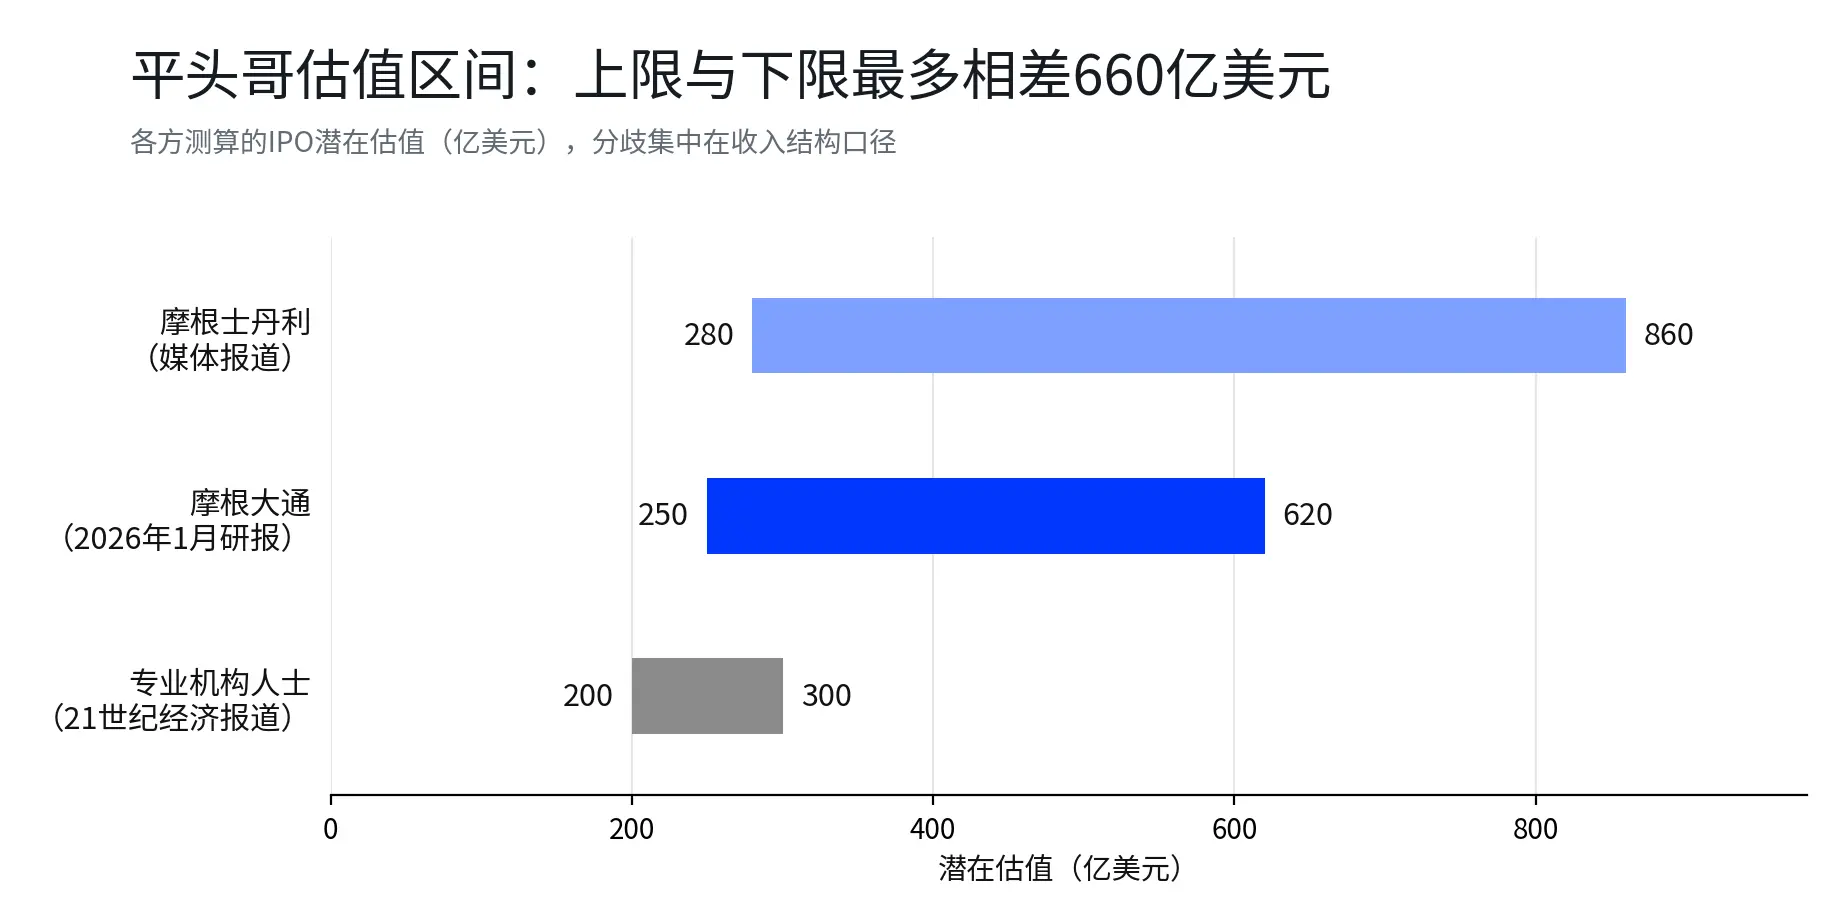
For a company, this exceeds the normal several hundred million USD estimation error and reflects a clear divergence in the capital market's understanding of the business model. This divergence does not mean the market does not know how much T-head is worth; the real issue is that several key accounts are still missing.
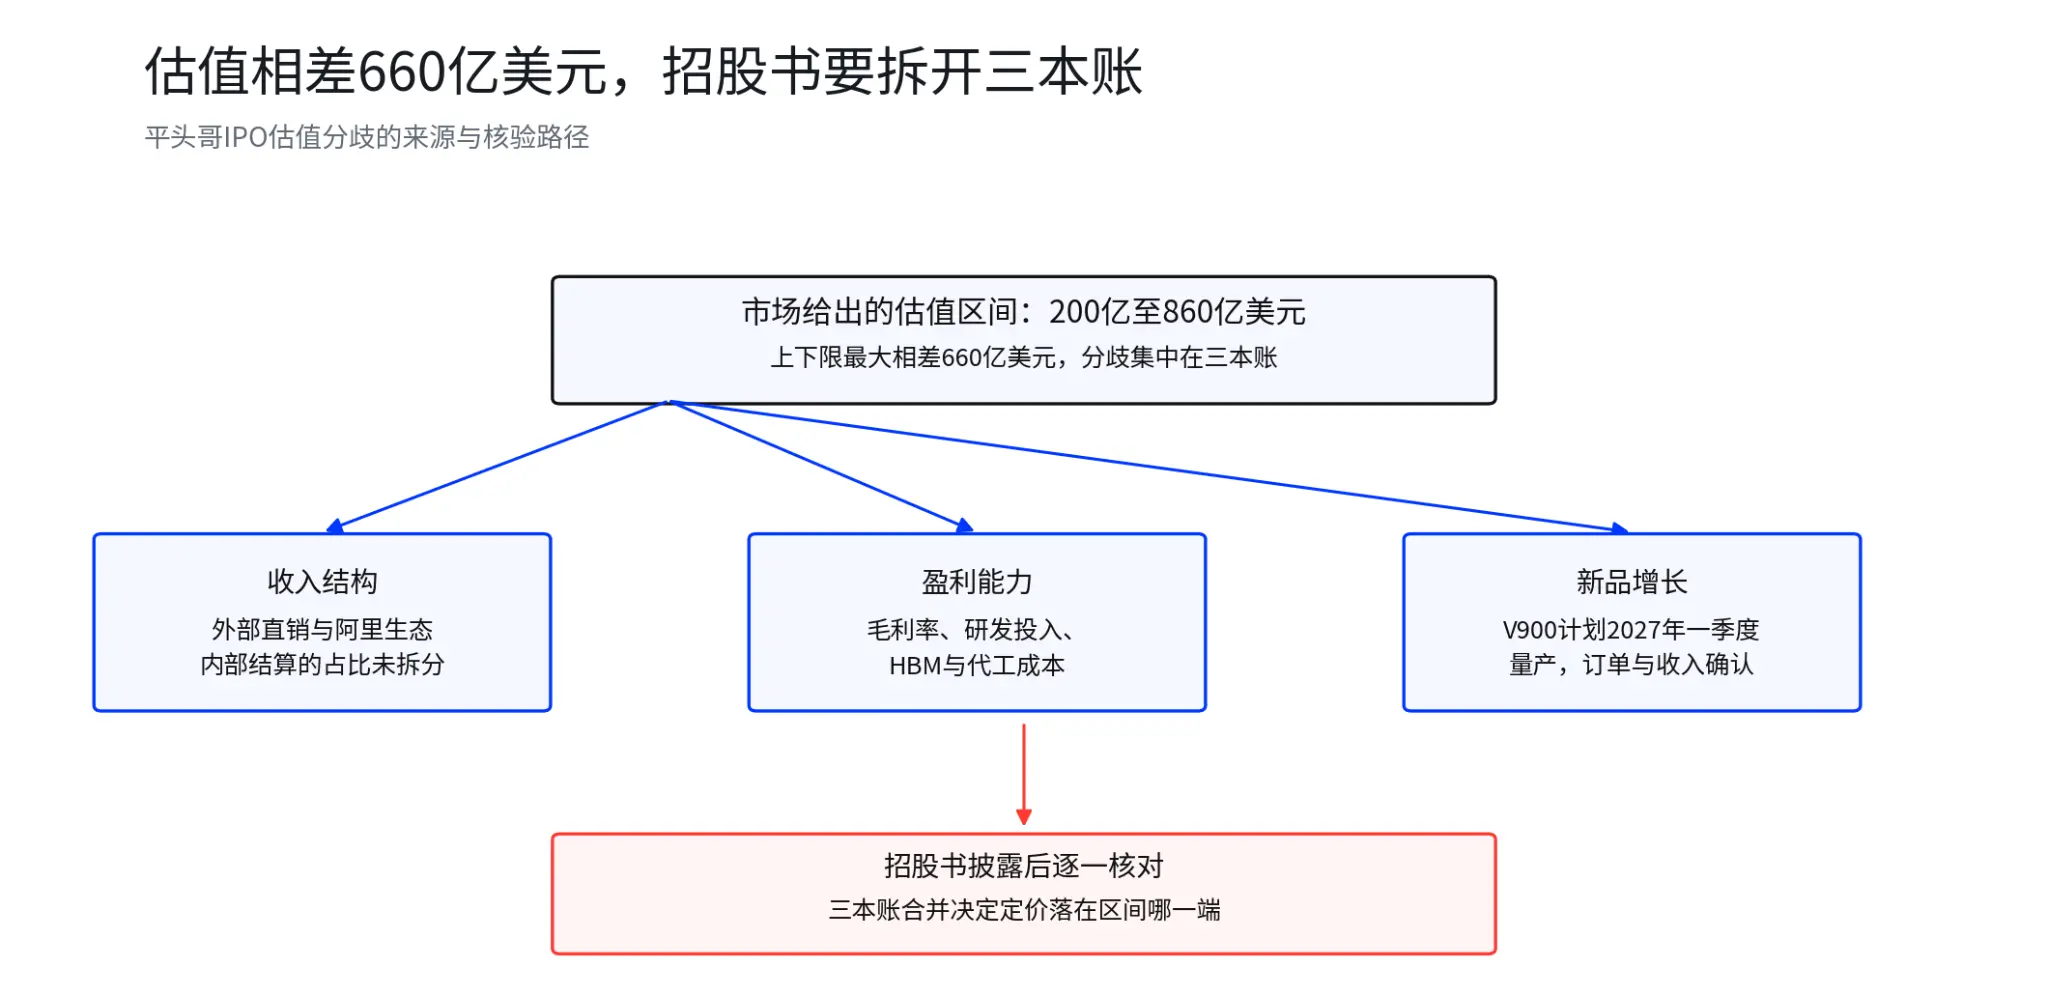
First is the revenue structure. T-head's annual revenue has exceeded 10 billion yuan, but how much of that comes from real external customers and how much comes from within the Alibaba ecosystem is still lacking complete public data.
Second is profitability. Revenue growth for chip companies does not automatically equate to high profits; R&D investment, wafer manufacturing, advanced packaging, HBM, and other supply chain costs will all affect the final gross margin and net profit. The market is willing to assign high valuations, provided that high revenue can gradually convert into sustainable profits.
Third is new product growth. If the V900 is successfully mass-produced in the first quarter of 2027 and quickly generates orders and revenue, what the market will see is a product curve that is still expanding upwards, with revenue potentially exceeding the current 10 billion revenue.
Therefore, what is truly worth watching in the prospectus are the financial and customer structure cards that can push the valuation from 20 billion USD to 86 billion USD.
V. Before the Prospectus is Disclosed, Look at These 5 Numbers: They May Determine How Much T-head is Worth
Once the prospectus is officially disclosed, investors can focus on verifying the following five items.
Proportion of External Customer Revenue. Current public information shows that external commercial customers account for over 60%. If this number continues to rise, it means T-head's reliance on internal orders from the Alibaba ecosystem is decreasing, and its independent commercialization capability is strengthening; if it remains at a low level for a long time, more attention will need to be paid to related transactions and revenue quality.
Growth Rate of External Revenue. Total revenue growth is important, but external revenue growth is even more crucial. If the growth rate of external customer revenue continues to outpace overall business growth, it indicates that T-head is transitioning from a chip company within the Alibaba ecosystem to a market-facing chip supplier.
Mass Production Progress of Zhenwu V900. The current official plan is for mass production in the first quarter of 2027. For new share valuation, the V900 is not just a product launch event; it is also an important verification point for whether the next round of revenue growth can be realized. Mass production, shipments, customer onboarding, and revenue recognition are the complete chain that is truly worth tracking afterward.
Gross Margin and R&D Investment. In the chip industry, revenue alone cannot be the only focus. If revenue is growing rapidly while gross margins improve and the proportion of R&D investment gradually decreases, profitability elasticity will significantly increase; conversely, if revenue growth relies mainly on high R&D investment and high supply chain costs, it will be more challenging for the market to assign high valuations.
Issuance Valuation and Issuance Price. This is the most direct question for new shares in the Hong Kong stock market. No matter how good the company is, if the issuance price is too high, it will compress the safety margin for new shares; if the fundamentals continue to improve while the issuance valuation is relatively restrained, it will be easier to form positive expectations.
Therefore, it is also necessary to consider the issuance market value, fundraising scale, issuance ratio, peer valuations, and company profit forecasts together; looking solely at the rumored valuation numbers in the market is not enough.
VI. What Should Hong Kong Stock Investors Look at Now?
T-head is currently still in the IPO advancement stage, and the formal offering and final issuance conditions still need to wait for subsequent documents. Therefore, the more appropriate action now is to establish a watchlist in advance; the issuance price has not yet been determined, so it is not appropriate to talk about early trading.
The most direct observation direction is the domestic computing power sector in the Hong Kong stock market. If the market begins to trade on T-head's IPO expectations in advance, related directions such as domestic AI chips, servers, semiconductor manufacturing, packaging testing, storage, and data center infrastructure may all experience emotional linkage.
However, this linkage needs to distinguish between two types of signals: if there is increased trading volume, leading stocks strengthening simultaneously, and the industrial chain's fundamentals also have orders or price changes to support it, it usually belongs to a higher quality sector trend; if it is just a single-day pulse stimulated by IPO news, it is more suitable for observation and should not be simply chased high.
For users participating in IPOs of Hong Kong stocks, what is truly worth waiting for are the subsequent three milestones: the disclosure of the prospectus, the determination of the issuance range and valuation, and the official subscription. When it reaches the formal IPO stage, it will be more meaningful to assess whether to participate based on the issuance valuation, cornerstone investors, public offering ratio, company profitability, and peer valuation, rather than guessing the issuance price in advance.
7. Why is this IPO worth continuous tracking and attention?
The significance of Pingtouge is not just that another subsidiary of Alibaba is going public. If it successfully lists on the Hong Kong stock market, the market will gain a domestic chip platform company that covers AI computing power, server CPUs, storage control, network interconnection, and RISC-V IP.
More importantly, as revenue, customers, shipments, and R&D investments are gradually disclosed, the market will be able to start comparing the commercialization capabilities of domestic computing power companies using the same set of capital market language. For investors, this comparability itself is valuable.
In the past, the market traded more on the industrial trends and thematic expectations of domestic computing power; after going public, investors can further compare who has faster revenue growth, who has more external customers, who has higher gross margins, and who can convert R&D investments into sustained orders. This is also the most noteworthy aspect of Pingtouge's IPO: it may shift domestic computing power from thematic trading to fundamental pricing.
In conclusion: First look at the company's quality, then look at the issuance price
Since its establishment in 2018, Pingtouge has achieved over 10 billion yuan in annual revenue and shipped hundreds of thousands of AI chips, reaching the doorstep of an IPO on the Hong Kong stock market, completing an important step from technological R&D to commercial verification. However, the real reason to participate in the IPO should not just be the labels of "under Alibaba," "domestic computing power," or "AI chips."
The most important thing moving forward is whether Pingtouge's external revenue, customer structure, gross margin, R&D investment, and V900 production capacity can collectively support a higher valuation after the prospectus breaks down the accounts. The current market valuation range of 20 billion to 86 billion USD itself serves as a good reminder: gaining recognition in direction does not mean that any price is worth buying.
For Hong Kong stock investors, at this stage, Pingtouge can be added to the IPO observation list, focusing on tracking the prospectus, issuance valuation, and cornerstone investor situation. Once the price is truly established, then assess whether a "good company" and a "good price" appear simultaneously.
Disclaimer: The content of this article is for general information and market commentary purposes only, compiled based on publicly available information as of the time mentioned in the text. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies quoted from third-party institutions, analysts, or other individuals only represent the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it be used as the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess the relevant risks based on their own circumstances and seek professional advice when necessary.
 Risk warning
ChainCatcher reminds readers to view blockchain rationally, enhance risk awareness, and be cautious of various virtual token issuances and speculations. All content on this site is solely market information or related party opinions, and does not constitute any form of investment advice. If you find sensitive information in the content, please click , and we will handle it promptly.
Popular articles





