








Former Chief Economist of Meta: The true moat of AI is not in the model itself, and Anthropic will not dominate alone
 Core Viewpoint


 The article argues that AI is at the crossroads of the promise and turning point of general-purpose technology. The history of steam, electricity, and railways shows that most value flows to complementary assets rather than first movers. Open weights will accelerate the commodification of intelligence, and companies will rely on proprietary data, distribution, and real-world learning loops to capture returns. Anthropic may be highly valuable, but it will not be the only surviving company.
Author: Christian Catalini, Founder of MIT Cryptoeconomics Lab, Co-creator of Libra, Co-founder and former Chief Strategy Officer of Lightspark, Former Chief Economist at Meta
Compiled by: Gu Yu, ChainCatcher
Time and again, general technologies perform the same three-act magic in the economic realm: the pledge, the turn, and the prestige. From steam and electricity to internal combustion engines and railroads, their evolutionary patterns are remarkably similar.
It all begins with the demonstration of early breakthrough capabilities. Enthusiasm surges, hype follows, and everyone is eager to infer a future dominated by the technology and its pioneers from the initial applications. Soon after, greed drives massive capital into infrastructure and capacity to conquer the market. Winners are prematurely declared and hailed as inevitable.
Riding the initial momentum, the steering entrepreneurs become arrogant, and investors no longer scrutinize assumptions and fundamentals: "This time it's different."
But a turning point usually arrives, with crashes, major reshuffles, or delayed productivity gains pulling valuations and expectations back to reality. After the revelry, many traumatized investors completely withdraw from the technology.
Once the tourists leave, the real "prestige" is ready: it is precisely the irrational expansion that pushed early winners into bankruptcy, leaving behind the abundant infrastructure necessary for the eventual realization of structural transformation. This technology delivers on every promise, but the vast majority of value flows to those organizations that quietly own or build the scarce complementary assets needed for scaling.
The Inevitable Arrogance of Pioneers
Artificial intelligence is currently in a phase between the pledge and the turn. Overconfidence has reached historical peaks. The rhetoric from the labs is generally as follows: our models may possess consciousness; only our labs can be entrusted with such powerful technology; please regulate us, or terrible things will happen; we may one day become the last remaining private company in the world. Gavin Baker attributed the last statement to Dario Amodei. Anthropic researcher Sholto Douglas vehemently denied this, but Amodei did not directly address it in his response.
Whether Amodei truly believes that Anthropic can ultimately control most of the economic system, his arrogance reflects the shadows of entrepreneurs who profoundly shaped general technologies before him—many of whom mistakenly conflated control over the early forms of new technologies with the ability to shape their developmental trajectories and capture the value they create.
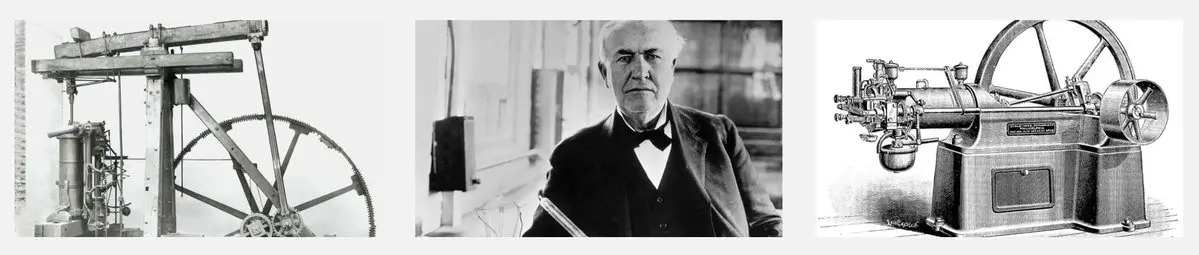
Take the steam engine as an example. Boulton & Watt strictly controlled their designs for decades through patent monopolies. However, enormous value flowed downstream. In cotton production, the price of yarn plummeted, and by 1830, cotton products accounted for about half of the UK's domestic exports. Looking at electricity, it was so successful that it became a regulated public utility, undifferentiated and measured by kilowatt-hours. Factories captured the upward space, with the share of electric motors in U.S. factory power rising from less than 5% in 1899 to nearly 80% within 30 years. During almost the same period, the annual growth rate of labor productivity in manufacturing surged from 1.5% to 5.1%.
What about internal combustion engines? The situation is similar. Over 700 companies in the U.S. joined the race to manufacture automobiles, but by 1941, the industry had shrunk to three giants and a few independents. Value migrated to its complements: gasoline surged from being a nearly worthless byproduct to accounting for 44% of the crude oil processed by U.S. refineries in 1931, while each additional highway crossing through a city was estimated to reduce the city's population by 18%, benefiting the suburbs.
Railroads? The similarity is almost too perfect. In 1876, Tom Scott managed one of the most powerful companies in the U.S. at the time, and the world's largest freight carrier: the Pennsylvania Railroad. The media compared him to Napoleon, and his actions suggested that owning railroads equated to owning the entire market. However, Standard Oil captured most of the Pennsylvania Railroad's oil volume.
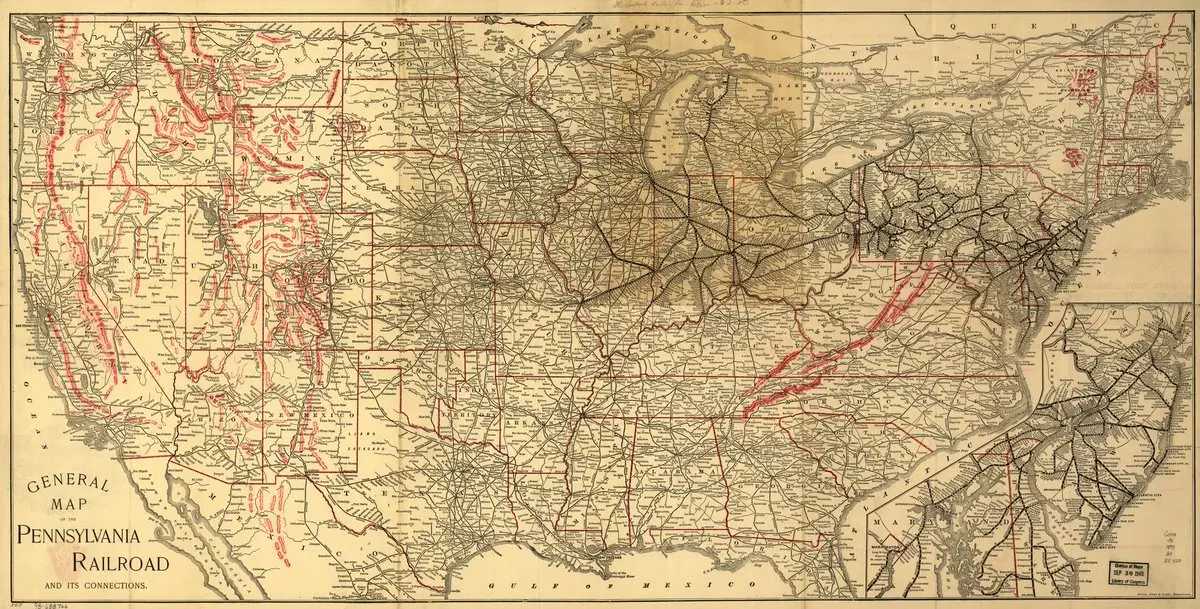
The contradiction began when the Pennsylvania Railroad's affiliated carrier, Empire Transportation, ventured into the refining business. Rockefeller demanded that Empire exit the new business, but Scott refused, forcing Rockefeller to shift his freight to competing railroads. The Pennsylvania Railroad then responded with a devastating price war, desperately trying to attract other shippers to use its lines. As one of Scott's aides put it, "We paid them large rebates… In some cases, the rebates we paid exceeded the entire freight charge." Subsequently, the railroad strike of 1877 drained the Pennsylvania Railroad's treasury, and Empire's assets were sold to Standard Oil. Within months, Standard Oil extracted 20 cents per barrel from the Pennsylvania Railroad, even including crude oil transported for Standard Oil's competitors.
But the story of the Pennsylvania Railroad is not an isolated case. After years of overbuilding, financial leverage, and price wars, the panic of 1893 led to the bankruptcy takeover of over 100 railroad companies. However, the tracks remained, and the network thrived: it is estimated that the annual private return rate of railroads in 1890 was only 3.5%, while the social return rate was as high as 48%. Without railroads, the value of American agricultural land would have shrunk by 60%.
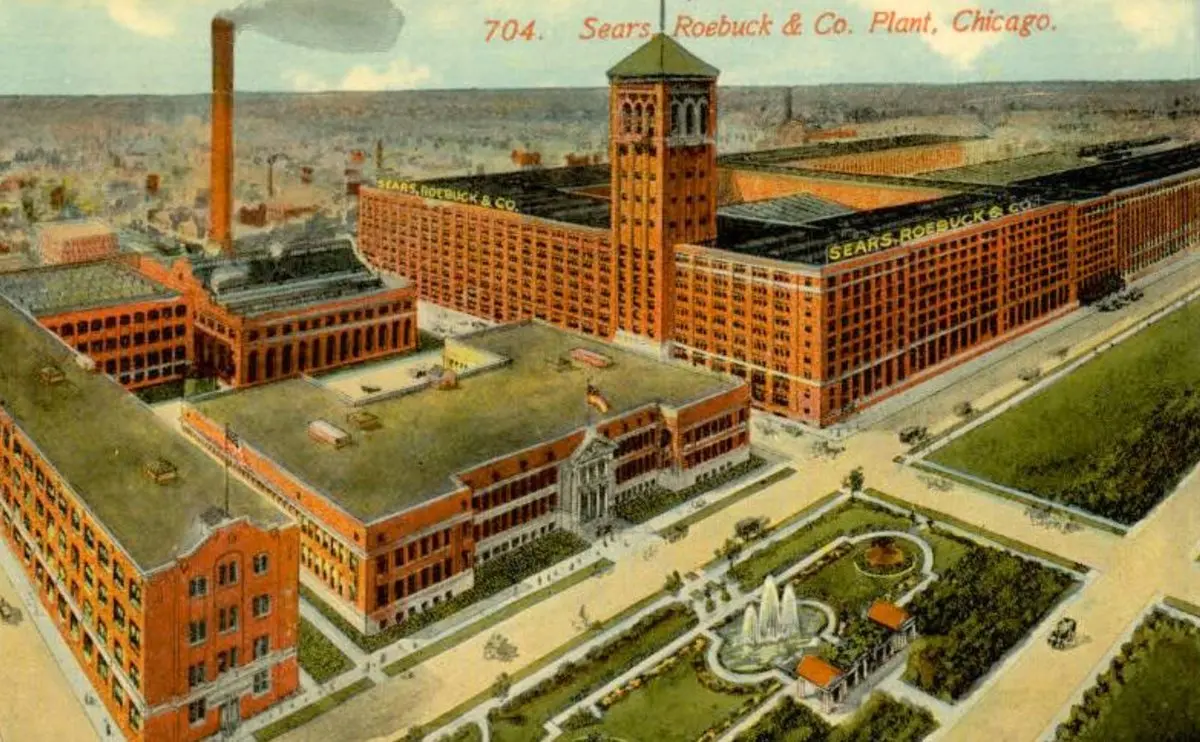
Investors funded the construction, but the value flowed to landowners, manufacturers, shippers, and of course, consumers. Sears is an excellent example of the "application" layer of that era: Richard Sears began his career as a train station agent and built a massive retail empire relying on mail-order catalogs and railroads. By 1906, his Chicago distribution center, covering 3 million square feet, connected to every major outbound rail line. Sears' sales skyrocketed from $750,000 in 1895 to $50 million in 1907.
The Value of Complementary Assets
So, if AI labs are the railroad companies, who plays the role of Standard Oil, and who plays Sears? Standard Oil represents any enterprise that controls high-value demand: those benefiting from proprietary data and capable of routing to real benchmarks (ground truth) for AI workloads. Sears represents the application layer: as intelligence becomes commoditized, its customer relationships, distribution channels, and automated workforce become increasingly valuable participants. NVIDIA is currently a scarce upstream supplier in both categories.
In a recent in-depth analysis of the economics of closed models versus open-source AI models, I argue that due to the difficulty of protecting AI models and their ease of learning, the field exhibits a weak appropriability regime. While the primary concern so far has been that open-source weights will undermine future investments in AI, the reality is that they will only affect the direction of those investments: what to produce, who produces it, and who captures the returns.
When appropriability is weak, value does not flow to the party that contributed most to the invention. It flows to the bottlenecks that constitute large-scale deployment. The obvious scarce complements for AI are computational infrastructure and chips. Amodei points out that if open-source weight models dominate at the expense of labs, these will become natural sources of centralization. However, control over these assets is not static: labs, hyperscale cloud providers, chip manufacturers, and even sovereign nations are moving upstream to secure alternative supply sources.
In the short term, as supply severely lags behind the surge in inference demand, scarcity may exacerbate centralization and reward those entities capable of providing the necessary inputs on land or in space. However, in the long run, the same strong demand signals will attract investment and innovation, thereby disrupting today's market leaders.
What Amodei cleverly avoids mentioning is that hardware and infrastructure do not follow the same extreme winner-takes-all mechanism as software. They can remain centralized, but their bottlenecks are physical, explicit, and investable: even though building new capacity takes time, high prices will attract the entry of new global capacity.
At the inference end, as long as labs can maintain a sufficient lead, they will not have difficulty monetizing state-of-the-art capabilities. But beyond that, they either need to lock in customers through more traditional software bundling or rapidly acquire their own complementary assets. This explains their interest in chips and their moves into cybersecurity—where even a slight advantage can translate into significant differences in customers' willingness to pay. The same applies in biology and medicine, where patents can turn slight leading advantages into legitimate exclusive rights.
However, the steepest areas of the intelligence demand curve also set limits on private power. In these areas, marginal buyers are nation-states, and governments can bypass ordinary markets through procurement, mandatory access, or even nationalization. Ironically, if frontier labs wish to maintain their freedom, they must succeed, but not be too successful.
The feasibility of open-source weights has not diminished profit motives; it has only accelerated this process in multiple different directions. As yesterday's cutting-edge fields become commoditized, previously economically unviable artificial intelligence applications suddenly become feasible, providing more reasons for chip manufacturers, enterprises, application companies, and governments to fund and improve a more distributed intelligent "commons."
But if you take a step back and seriously examine the laws of complementary assets, you will immediately realize that although laboratories can collect large amounts of public data at low cost based on fair use principles, future returns in specialized, currently unverifiable fields will increasingly rely on proprietary traces, tacit knowledge, record systems, and unique real benchmarks and expert decision sources.
No matter how powerful the computer operations, memory, and communication tools in laboratories become, companies are becoming increasingly wary of handing over this information. As companies with valuable industry knowledge turn to owning and controlling their "production weights," many market leaders in various industries will be able to achieve or exceed the performance of cutting-edge models on tasks critical to them at a lower cost by combining open-source weight models with their own generated proprietary information.
The key remaining moat is the ability to generate more accurate and relevant real benchmarks quickly through continuous interaction with the real world, along with physical infrastructure, proprietary data and talent, and distribution channels. As intelligence spreads, the defensive barriers will no longer be historical datasets that can unlock new capabilities through purchase, but rather the actual control of valuable real-world learning loops: that is, not only being able to deploy artificial intelligence but also collecting the necessary telemetry data to verify whether automated operations are correct and improving the system until it is trustworthy enough to support deeper automation.
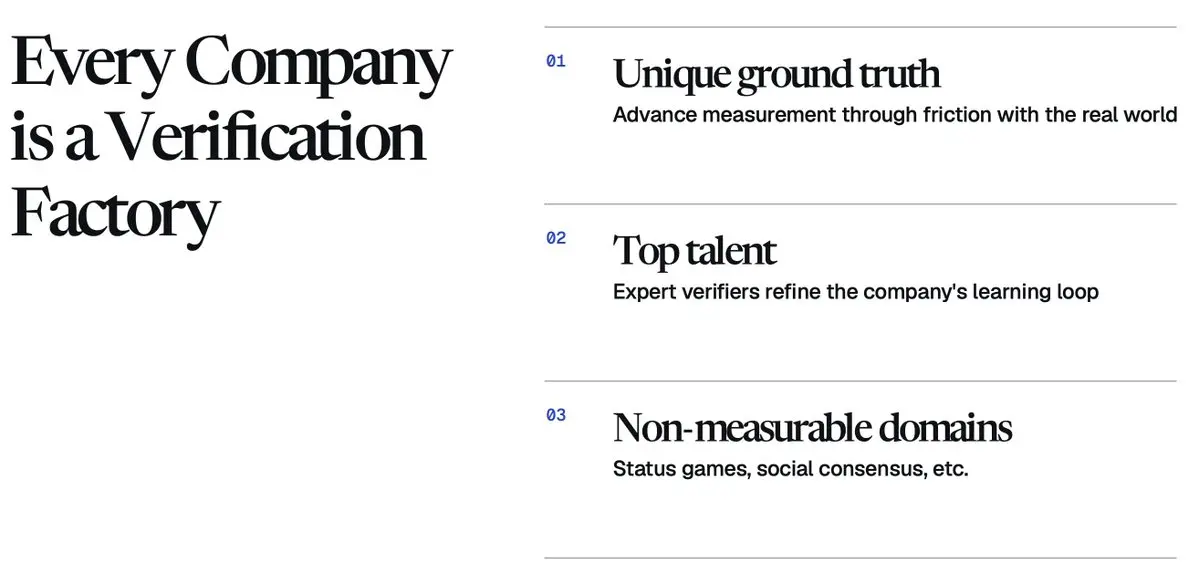
Companies that retain the information generated by these loops will not only send fewer token requests to upstream cutting-edge laboratories but will also better protect their businesses from the disintermediation impact of artificial intelligence. Laboratories are aware of this and are expanding downstream into workflows in finance, healthcare, law, design, and accounting to compete for more business. But of course, the deeper they expand, the greater the conflict with some of their own clients, thus creating additional demand for treating open-source weights as a fallback option.
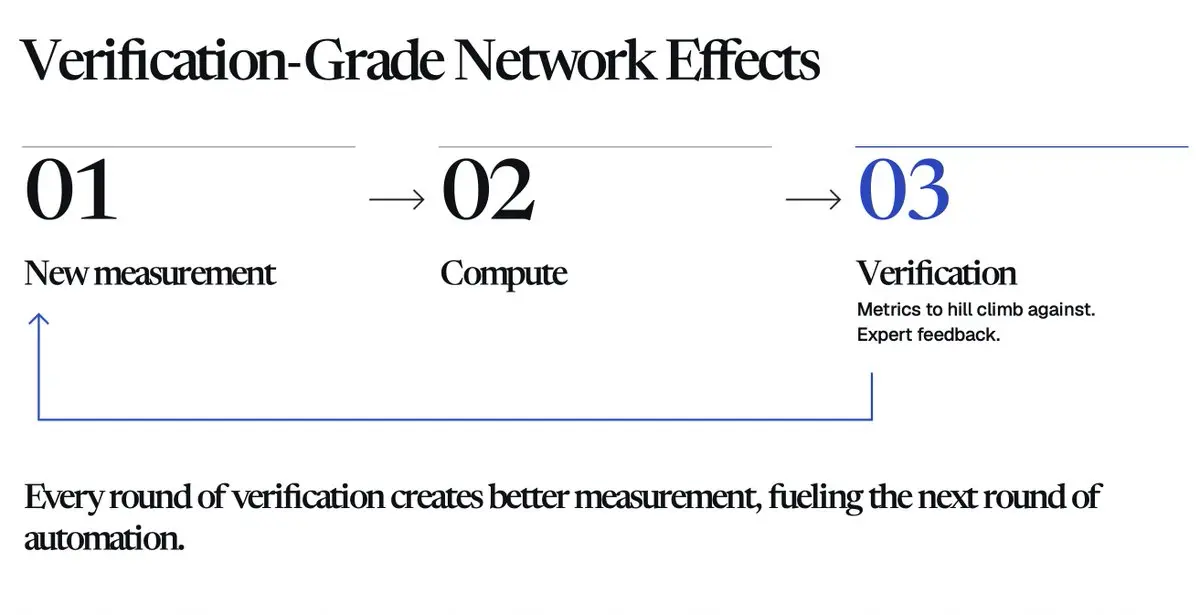
This may split the demand for machine intelligence into commodity tokens and high-value tokens. The former will be cheap and measured like kilowatt-hours. The latter will ensure a premium with defensive barriers, increasingly driven by proprietary real benchmarks.
A World with Numerous Competitive, Specialized Intelligences
For most economic sectors, once models are good enough, additional capability enhancements are far less important than deeper enterprise workflow integration, lower costs, or greater control. Therefore, as open-source models continue to commoditize cutting-edge technology, they will seize substantial demand, forcing laboratories to delve deeper into fields where they can still command a premium.
Whether it is the underlying economics of artificial intelligence or the history of general technologies, both are pushing society toward a more balanced outcome rather than centralization. The only force that could completely reverse or delay this trend is the kind of regulation that Amodei is fervently advocating for. If regulators set extremely high compliance thresholds, they will favor laboratories large enough to support massive legal, policy, and security expenditures. They may also harm the thriving open-source alternatives outside of closed-source models, such as by limiting the capability ceilings that open-source models are allowed to reach. This would reduce regulation to a missing complementary asset that technology itself cannot provide. Of course, this does not mean that safety concerns are insincere or unimportant.
If the logic of complementary assets holds as it has in the past, the most likely outcome remains a coexistence and competition of various competitive intelligences across markets and applications. This diversity will equip society with better preparedness, greater resilience, and greater safety in many areas. Rather than cultivating a few single varieties that may experience correlated failures, it is better to establish a diversified intelligent ecosystem that provides us with various tools to cope with the inevitable unknown risks in the coming years. In the field of cybersecurity, a broader diffusion through open-source models is clearly beneficial for defense rather than attack. Other fields, such as biology, may be quite different, but we might be able to control them more effectively by focusing on complementary assets that bridge ideas and implementation (such as synthesizers, biomaterials, and related supply chains).
Artificial intelligence, by making intelligence cheap, could become the most universal technology created by humanity. If so, it is likely to bring the greatest victories to holders of complementary assets to date. Laboratories have laid the tracks for machine intelligence to operate and expand, and they are likely to dominate the cutting-edge intelligence market for quite some time. In any case, value will flow to those who control perennially scarce resources, just as it has in past cycles.
Anthropic is likely to become one of the most valuable companies in the world. But it will never be the only one left.
Another version of this article is published on Forward Future.
 Risk warning
ChainCatcher reminds readers to view blockchain rationally, enhance risk awareness, and be cautious of various virtual token issuances and speculations. All content on this site is solely market information or related party opinions, and does not constitute any form of investment advice. If you find sensitive information in the content, please click , and we will handle it promptly.
Popular articles




