The Kobeissi Letter: $60 trillion evaporated in 45 days, but this is not the AI bubble bursting
 Core Viewpoint


 The Kobeissi Letter believes that the current situation is not a burst of the AI bubble, but a normal correction. In the past 45 days, the market value of U.S. stocks has evaporated by about 6 trillion dollars, and the market has factored in pessimistic expectations regarding capital expenditures, regulations, interest rate hikes, and Nvidia uncertainties. Although volatility and liquidity pressures remain, the risk-return profile of high-quality tech stocks is improving.
Author: The Kobeissi Letter, a global capital market commentary organization
Compiled by: Gu Yu, ChainCatcher
The most common question we are currently asked is: Is there an "AI bubble," and has it already burst? The U.S. stock market has lost an average of $225 billion per day over the past 31 consecutive trading days. In the following text, we will comprehensively analyze how we got to this point, what is currently happening, and our outlook for the future.
Since November 2022, we have been highly optimistic about AI, calling it the most significant technological revolution in history. Our view of "holding assets or being eliminated" is based on innovation-driven returns and compounded inflation.
In the past six weeks, AI trading has faced one of its most severe tests since its inception, comparable to the situation during the trade war in April 2025. We recommend saving this article and referring to it in the coming weeks.
The reality is that AI is disrupting the status quo of global markets, economies, and human civilization. Disruption will lead to polarized emotions, and the volatility of asset prices will only exacerbate this division.
This is exactly what we are witnessing now.
Chaos Over the Past 45 Days:
Before we begin, it is essential to understand how much has happened since the S&P 500 index last reached an all-time high on October 6.
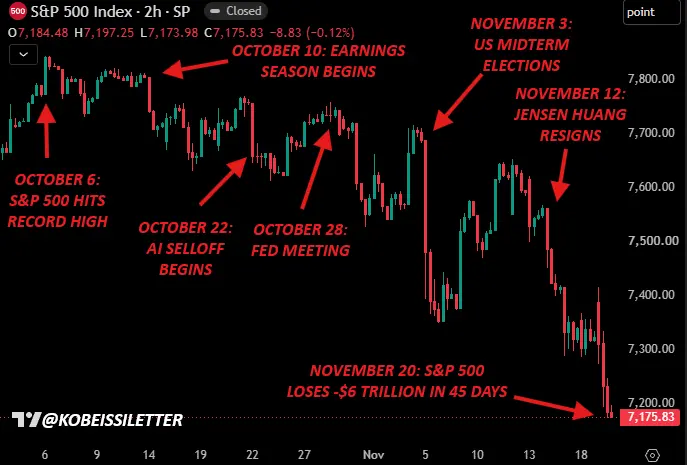
S&P 500 Index and Recent Major Events - Since October 6, 2026
In the past 45 days, the market has been flooded with countless headlines about the Iran war, the third-quarter earnings season of 2026, concerns over AI capital expenditures and free cash flow, the October Federal Reserve meeting, the U.S. midterm elections, the controversy surrounding Nvidia ($NVDA), which ultimately led to a market capitalization evaporation of $6 trillion.
In addition, Anthropic's IPO recently raised over $100 billion, setting a record for the largest IPO in history, which has clearly put immense pressure on market liquidity in recent trading days.
During such times, it is crucial for investors to step back and ask themselves a core question: What has changed, and what expectations have already been digested by the market?
Many Expectations Have Been Digested: Concerns Over Capital Expenditures and Free Cash Flow:
This round of sell-off was primarily triggered by market concerns over the capital expenditures (CapEx) of major U.S. tech companies in AI and the outlook for free cash flow and profitability impacts in 2027 and 2028.
These are very real concerns.
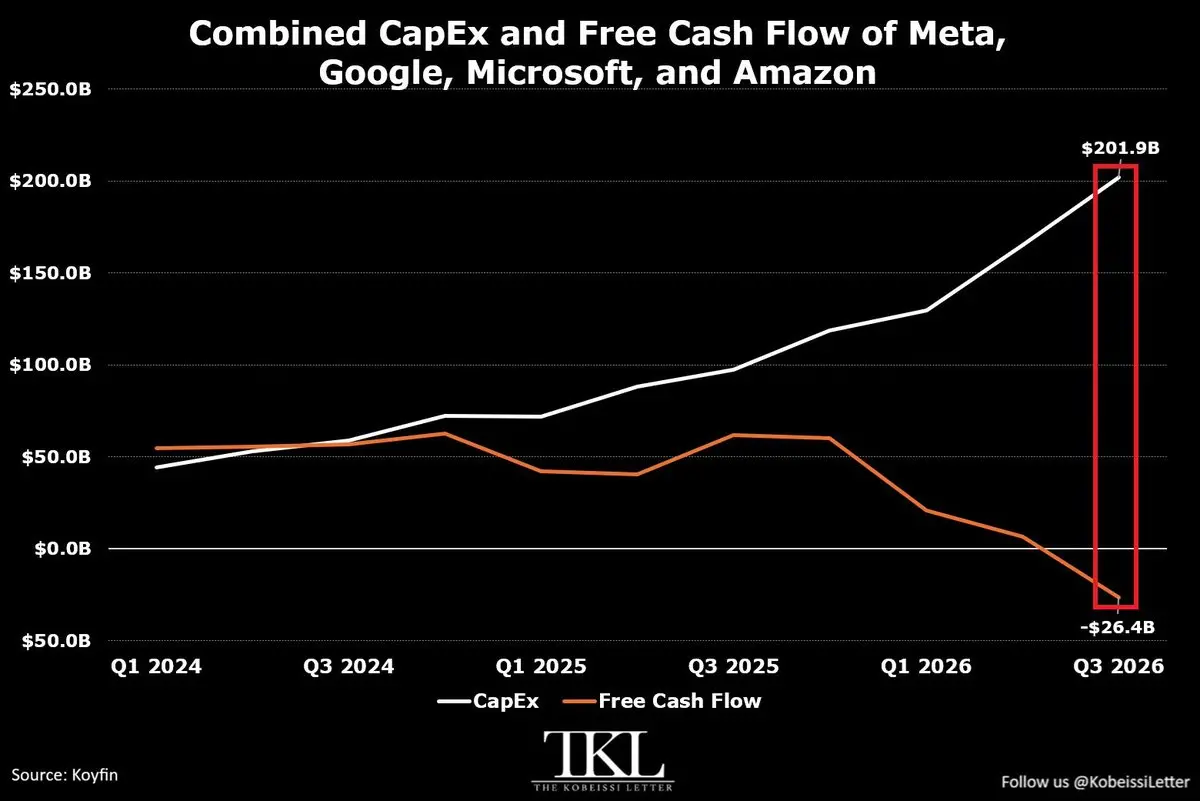
Capital Expenditures and Free Cash Flow - Major Tech Companies
Amazon ($AMZN), Alphabet ($GOOGL), Meta ($META), and Microsoft ($MSFT) saw their capital expenditures in the third quarter of 2026 increase by $36.9 billion, reaching a record $201.9 billion.
This figure has more than doubled in the past 12 months, growing by 356% compared to the first quarter of 2024. The capital expenditures of major tech companies have reached $1.6 trillion over the past three years.
However, we must also acknowledge that record infrastructure spending is a necessary prerequisite for this historically significant technological revolution. A brief period of negative free cash flow is the short-term cost of undertaking long-term construction.
Many of these concerns have already been reflected in prices, but they will persist until clearer information about the return on investment (ROI) for this capital expenditure is obtained—likely extending into the first/second quarter of 2027.
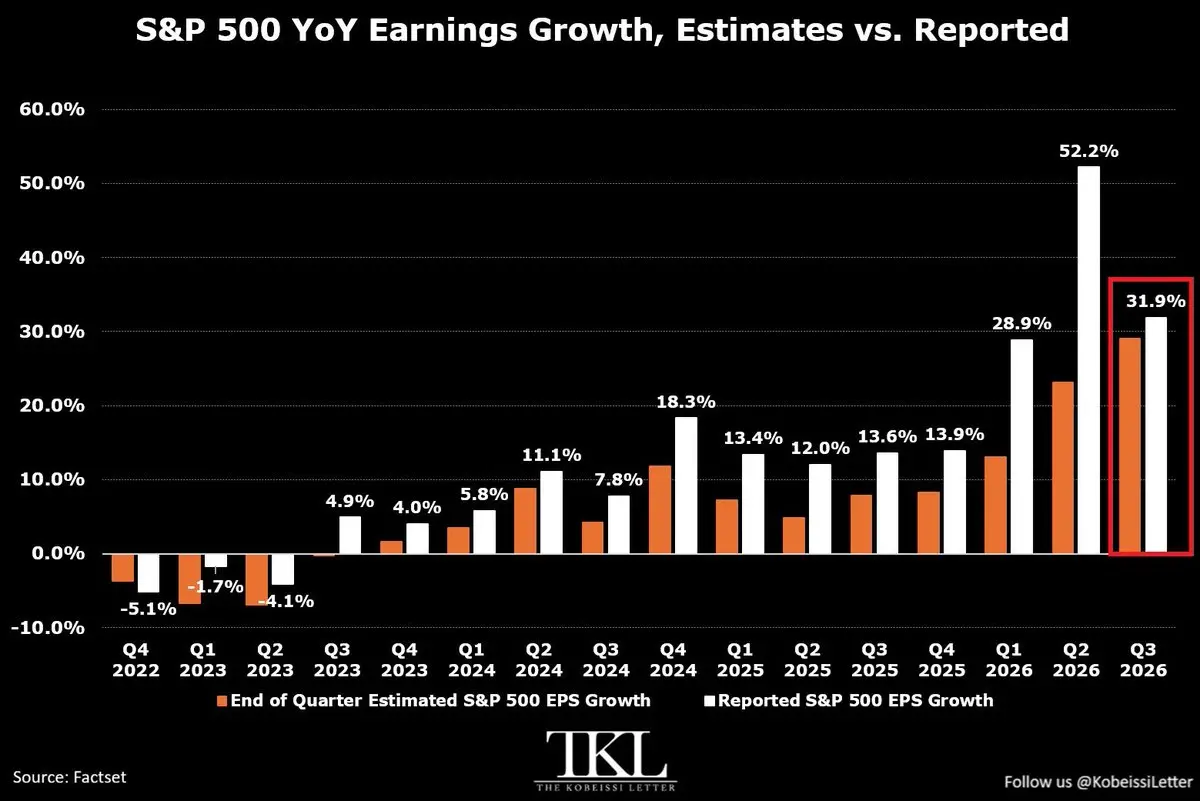
S&P 500 Index Earnings Per Share Growth - Third Quarter of 2026
The market has never experienced such immense panic accompanied by such strong growth. As of now, S&P 500 constituent companies have seen their earnings per share (EPS) grow by 31.9% year-over-year in the third quarter of 2026, the strongest year-over-year growth in at least four years.
Actual earnings have exceeded expectations for 13 consecutive quarters, and the strength of AI construction has surpassed most people's perceptions.
Democrats Sweep U.S. Midterm Elections—Ending the "Trump Put":
Secondly, we believe that the recent significant pullback in tech stocks is mainly catalyzed by the results of the U.S. midterm elections, which effectively herald the end of what we call the "Trump Put."
From President Trump's first term from 2016 to 2020 and his current second term, it is evident that when the market faces volatility and President Trump has the ability to influence the market, the market objectively feels reassured. The "Trump Put" is a hedging mechanism, where people believe that if market conditions worsen, President Trump would intervene, as a stable market has always been his top priority.
With the Democrats' "sweep" in the midterm elections, we believe the "Trump Put" has effectively come to an end. The following post released on November 4 further catalyzed the conclusion of this safety net:
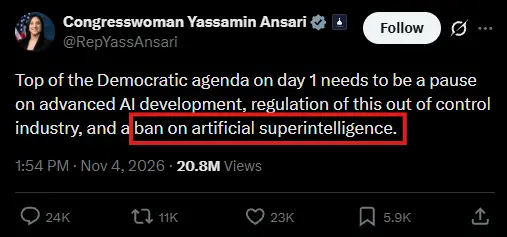
U.S. Congresswoman Calls for AI Ban - November 4, 2026
With the shift in control of the U.S. Senate and House of Representatives, President Trump's ability to intervene in the market has been partially weakened. The momentum for calls to ban AI is rising, and the market has digested expectations that the Democrats will implement strict regulations or even potentially issue an AI ban after taking power in January 2027.
While the end of the "Trump Put" is irreversible and will trigger a more significant pullback in U.S. stocks, we believe that concerns over regulation are somewhat overblown.
A complete ban on AI in the U.S. is impossible. Even if such a ban could be enforced, it would effectively mean that the U.S. is conceding defeat to China in the global AI race.
More regulations will emerge in the future, and new taxes may be imposed, but the current assumptions in the market are more extreme than what we believe will ultimately happen.
Ultimately, regardless of who is in power, the U.S. must strive for victory.
Federal Reserve Raises Rates Amid Anxious Market:
Beyond concerns over AI investments and changes in the political landscape, the Federal Reserve is also aggressively raising interest rates.
As the Iran war approaches its 300th day and U.S. inflation has remained above the Federal Reserve's 2% target for 67 consecutive months, Federal Reserve Chairman Waller has made it clear that his top priority is to reduce inflation to 2% without exception.
This means that the already high burden of building AI is becoming even heavier. Not to mention, the state of U.S. federal debt is even more severe.
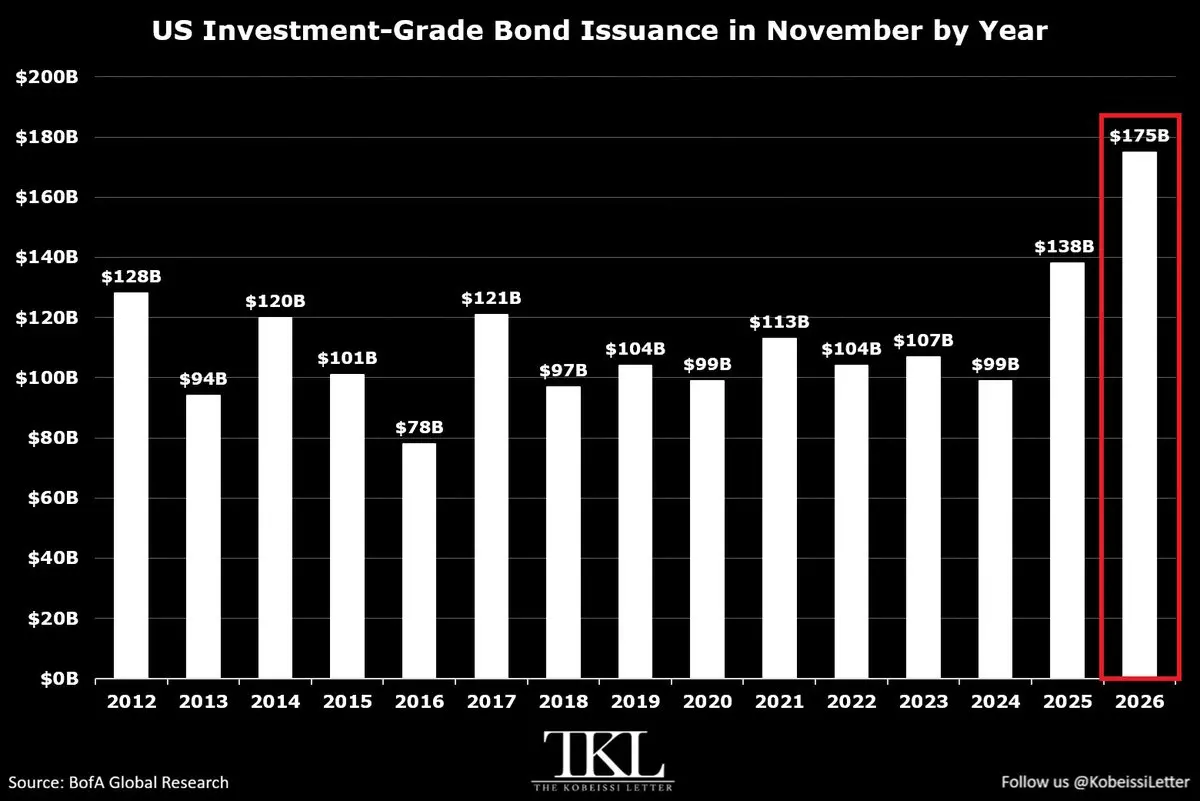
AI Construction Requires Record Debt Issuance
As shown above, U.S. investment-grade corporate bond sales are expected to increase by $37 billion year-over-year in November, a 27% increase, reaching $175 billion, the highest level for any recorded November. We believe that the Federal Reserve's interest rate hikes in this context have further exacerbated recent instability. Can this situation change?
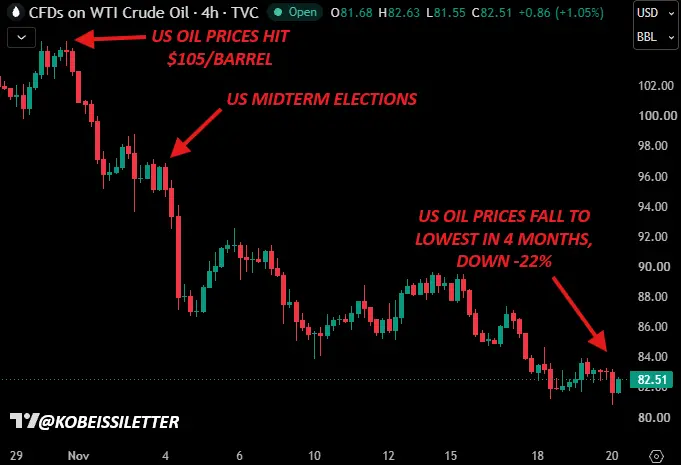
U.S. Oil Prices------November 2026
The transfer of political power and the recent market decline have led to a drop in oil prices of about 22% this month. Coupled with market instability, the Federal Reserve's outlook for 2027 is likely to change, especially if the Iran war is significantly closer to ending.
On November 2, we released the following analysis of U.S. oil prices before the midterm elections, predicting that oil prices would fall below $93.00. Since then, oil prices have reached their lowest level since August 2026. On Sunday, we will release the latest issue of The Kobeissi Letter, consider subscribing for access here.
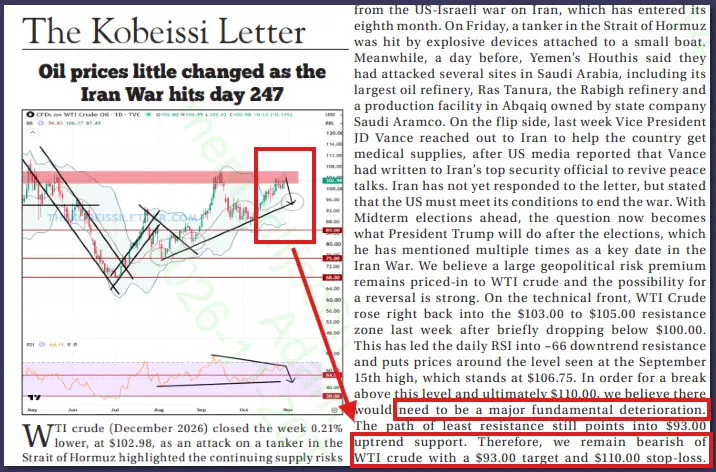
The Kobeissi Letter------November 2, 2026
Even with falling oil prices, "higher for longer" will currently persist, but we believe that the likelihood of the Federal Reserve's policy becoming less restrictive by mid-2027 is increasing.
Nvidia, AMD, and the Chinese Chip Situation
In the past two weeks, Nvidia has lost its leadership in the AI revolution with Jensen Huang, and its stock price has dropped 40% in a matter of weeks. AMD is now accused of smuggling chips to China, and the market has priced in significant concerns regarding the related impacts.
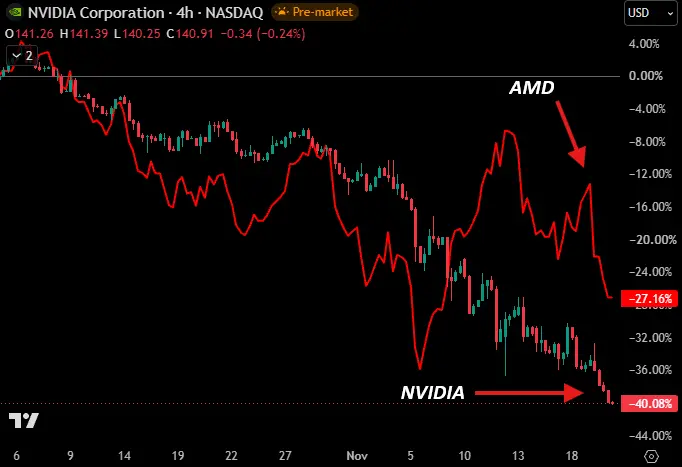
Nvidia and AMD Since October 6, 2026
As you may have already seen, we have been outspoken about Nvidia's situation and have made our position clear early on: Jensen Huang is innocent until proven guilty. We urge the board to keep the door open for Jensen's return until a clear independent investigation establishes the facts.
We hold this view because Jensen Huang has been immensely innovative and influential in the AI revolution and the success of the United States. Nvidia's stock price now reflects an almost certain expectation that Jensen Huang will not return, effectively erasing the company's forward guidance.
The same situation is occurring with AMD. A short report on November 19 accused the company of smuggling chips to China, a claim that remains unverified.
As a result of these events, the forward price-to-earnings ratio of the tech sector has fallen to its lowest level since March 2020.
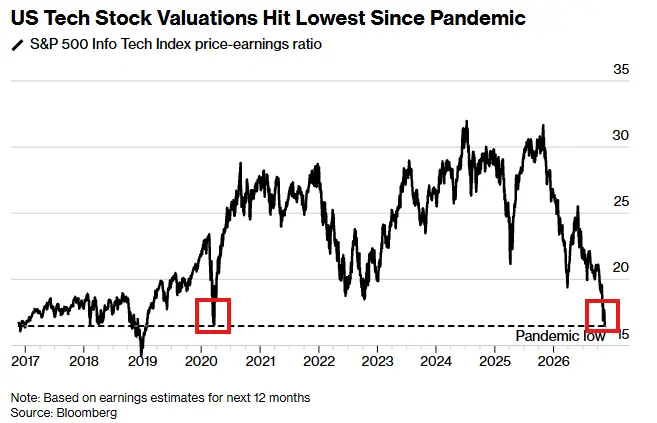
S&P 500 Technology Sector ------ Forward Price-to-Earnings Ratio
Nvidia's forward price-to-earnings ratio has dropped to 9 times, making it one of the cheapest stocks in the S&P 500, and it is undoubtedly the cheapest relative to the earnings growth the company is achieving.
What does this mean? The market does not believe the "E" (earnings) part of the forward price-to-earnings ratio. Despite Nvidia guiding for fiscal year 2028 revenues of approximately $750 billion, the market refuses to believe this even without Jensen Huang.
The current market has already priced in a significant amount of upside potential.
Current Sentiment is at Crisis Levels
On October 15, we published an analysis titled "Invisible Bear Market," pointing out that beneath the surface of the S&P 500, there exists a bear market, especially in tech stocks. This marked the beginning of a shift in sentiment. It did not start with the midterm elections or Nvidia's situation.
As shown below, these events have merely accelerated the shift in sentiment.
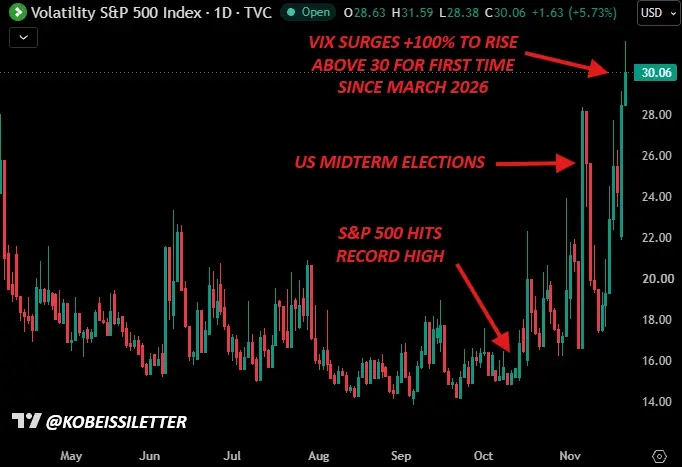
S&P 500 Volatility Index
The volatility index $VIX has risen over 100% from the October lows and recorded its largest single-day increase since February 2018 on November 5. Now, combine this sudden surge of panic with the significantly reduced market liquidity from the Anthropic ($ANT) IPO.
The institutional demand for the IPO reached $400 billion, with retail orders totaling $100 billion after the book-building ended on Tuesday, nearly 8 times the expected $78 per share and an initial fundraising scale of $64.4 billion.
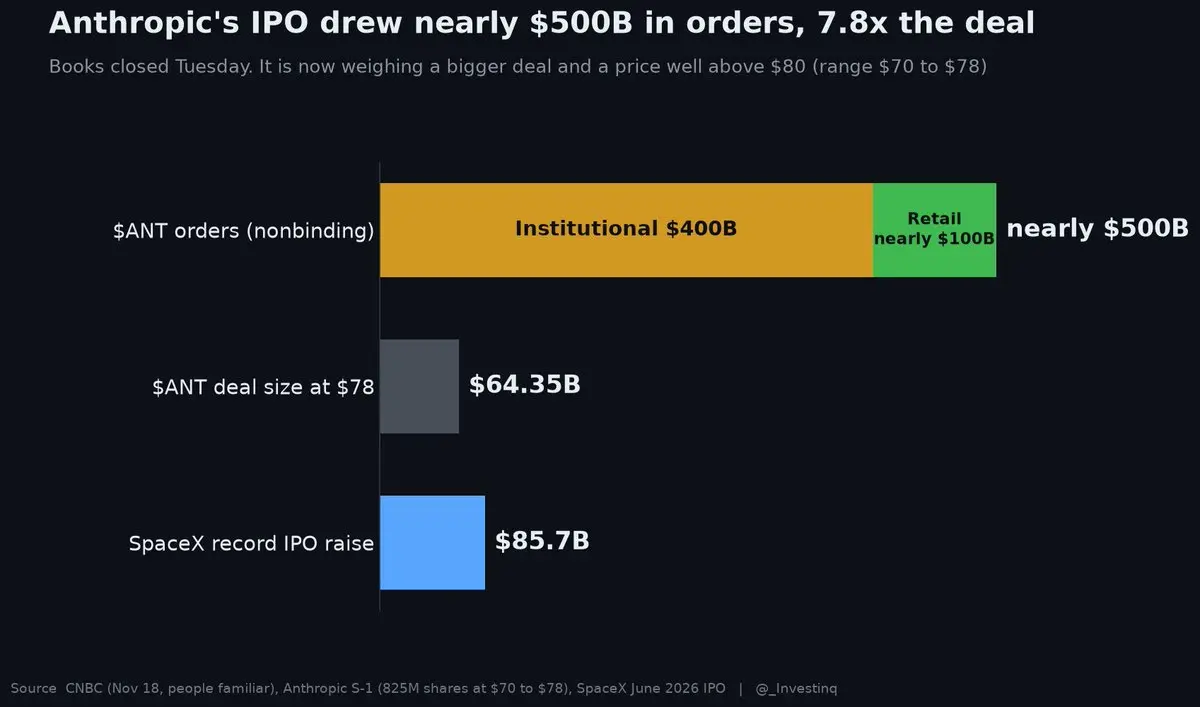
Anthropic IPO Demand
The sudden shift in sentiment combined with a significant drop in liquidity has led to the price movements we have seen this week, with everything from stocks to gold to crypto declining.
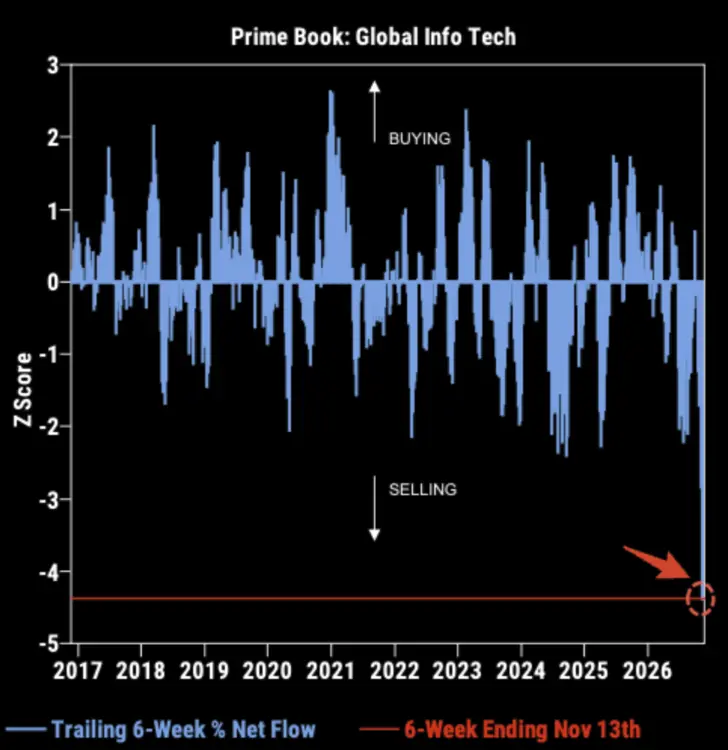
Hedge Fund Capital Flows in Tech Stocks
Hedge funds have recorded the largest net outflow in nearly 6 weeks this month, marking a rush to exit.
Once liquidity returns, we believe the market will stabilize.
Conclusion: What Happens Next?
This brings us back to the initial question: Is there an "AI bubble," and has it already burst?
Our answer is no.
There is no doubt that the AI revolution is facing one of its most significant tests to date. However, we believe the market has begun to price in a far more pessimistic outcome than what the current fundamentals suggest.
We think the market is undergoing a normal correction. Even if the S&P 500 were to drop another 10% from current levels, we would still be within the range of a healthy correction.
Calling for a prolonged bear market extending into 2027 is akin to betting that the aforementioned factors will not only materialize but will worsen. Current asset valuations have already priced in a significant amount of negative sentiment, and we remain cautious regarding calls for a more than 30% drop in the S&P 500, which is rapidly spreading.
The reality is that market sentiment has become extremely polarized, and we believe this polarization will continue to create opportunities.
At current levels, the market is pricing in a combination of various factors: persistently rising interest rates, aggressive AI regulation, disappointing returns on AI infrastructure investments, and the long-standing uncertainties surrounding some of the most important companies in the tech industry. Entering 2027, there is substantial room for positive surprises.
We are not saying the market has necessarily bottomed out. Volatility will remain high, liquidity will still be constrained, and further downside is entirely possible as uncertainty persists.
However, the risk-reward structure is becoming increasingly attractive, especially for high-quality tech companies with strong balance sheets, accelerating earnings growth, and enduring competitive advantages.
We believe a considerable degree of bearish sentiment has been priced in, while the market is overlooking the possibility of positive surprises. Once the dust settles, we expect dip buyers to quickly rotate back into high-quality tech stocks, similar to April 2025.
In the long run, asset owners will continue to prevail.
For more on our strategy: Maintaining objectivity and following a process during turbulent times is key to becoming a successful investor.
An objective and systematic approach is precisely why we have outperformed the market benchmark.
As shown below, since 2020, our investment strategy returns have approached five times that of the S&P 500 index.
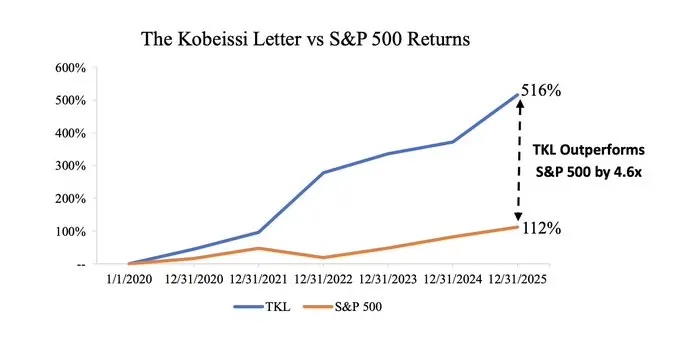
The Performance of The Kobeissi Letter ------ 2020 to 2025
 Risk warning
ChainCatcher reminds readers to view blockchain rationally, enhance risk awareness, and be cautious of various virtual token issuances and speculations. All content on this site is solely market information or related party opinions, and does not constitute any form of investment advice. If you find sensitive information in the content, please click , and we will handle it promptly.
Popular articles