Bridgewater's Dalio warns: the U.S. Treasury bear market is "far from over," and the risks of supply-demand imbalance continue to accumulate
 Core Viewpoint


 Dalio believes that the United States is entering a vicious cycle where debt expansion and demand contraction reinforce each other. Rising interest rates increase borrowing costs, which in turn raises the scale of debt; overseas demand is shifting, and both major "creditors," Japan and China, have motives to reduce their holdings. Considering the expected changes in the supply and demand for new debt, shorting U.S. Treasuries seems easier than going long. Corporate bonds and the AI financing wave intensify the competition for funds, making the corporate credit market comparable to "canaries in a coal mine." Debt servicing costs erode fiscal space; global debt competition intensifies, making it difficult for the stock market to remain unaffected. Including both debt and equity, the supply of financial assets seems to far exceed what demand can absorb.
Author: Li Dan
Hedge fund giant Bridgewater co-founder Ray Dalio has once again issued a warning about U.S. Treasury bonds: the sell-off of U.S. government debt is far from bottoming out, and the structural imbalance between supply and demand is pushing U.S. Treasuries toward a historic debt crisis.
Dalio stated on social media LinkedIn on Tuesday, the 13th, Eastern Time, that the U.S. is entering a vicious cycle where debt expansion and demand contraction reinforce each other. Rising interest rates are increasing borrowing costs, which in turn raises the scale of debt, and this spiral will continue until it "places sufficient pressure on the economy and financial markets, restoring balance between supply and demand." He wrote, "The bear market for (U.S.) bonds may have a long way to go."
Dalio's remarks sharply contrast with the positions of institutions like BlackRock and Morgan Stanley Investment Management. The latter has turned bullish after the yield on 10-year U.S. Treasuries soared to its highest level since 2002, nearing 5.4% earlier this month. According to reports, the Bloomberg index tracking U.S. Treasuries has fallen about 2.4% so far this year, and U.S. Treasury prices are expected to record their first annual decline since 2022.
U.S. Government Debt Reaches Highest Level Since World War II
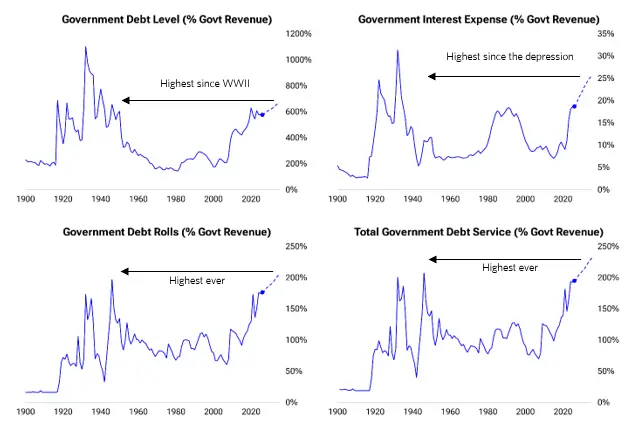
Dalio supports his judgment with a wealth of data. He estimates that, measured by the ratio of total borrowing and debt repayment costs relative to government revenue, the U.S. government's current liabilities have reached their highest level since World War II and are expected to continue deteriorating in the coming years.
As of the end of September 2026, the marketable U.S. Treasury debt outstanding is approximately $32 trillion, an increase of 8% from a year ago. The U.S. Treasury has net issued about $1.5 trillion in new debt so far this year, with an expected net issuance of $2.1 trillion for the entire year. Meanwhile, the Treasury also needs to roll over about $10 trillion in maturing debt.
Dalio warns that even a slight reduction in reinvestment willingness among investors could create a massive financing gap.
In terms of debt structure, the U.S. Treasury is increasingly turning to short-term bill issuance to alleviate the pressure of supply-demand imbalance in long-term bonds. Currently, short-term bill issuance accounts for about 50% of total issuance, far above the historical norm of 20%, a ratio typically seen only during economic recessions.
Dalio points out that while short-term issuance helps temporarily reduce interest expenses, it also significantly increases debt rollover risk and makes debt repayment costs even higher during periods of rising interest rates.
Overseas Demand for U.S. Treasuries Shifts, with Japan and China Particularly Key
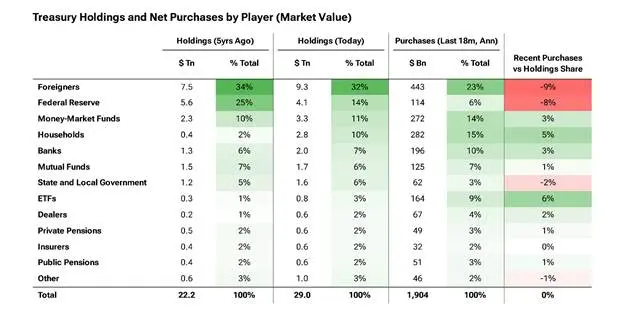
Dalio views shrinking foreign demand as one of the core factors putting pressure on the U.S. bond market. He notes that foreign investors currently hold about $9.3 trillion in U.S. Treasuries, making them the largest single holding group, accounting for about 32% of U.S. Treasuries, but their purchasing speed is slowing while supply continues to rise.
Among major foreign holders of U.S. Treasuries, the movements of Japan and China are particularly noteworthy. Dalio states that Japan holds about $1.1 trillion in U.S. Treasuries, of which about $600 billion is government reserves, and about $230 billion is held by the Government Pension Investment Fund (GPIF) of Japan.
He believes that Japanese policymakers have a strong incentive to guide domestic institutions to reduce their holdings of U.S. Treasuries and repatriate funds to support the yen and stabilize the Japanese bond market. The rise in Japanese bond yields will further reinforce this trend, and related yen arbitrage trades could also have a severe impact on the market.
Regarding China, Dalio states that official U.S. statistics significantly underestimate China's actual holdings. He roughly estimates that Chinese enterprises and individuals hold about $1 trillion in U.S. Treasuries, while China's reserves hold another approximately $2 trillion, with total Chinese financial assets in the U.S. potentially reaching $4 trillion. As the renminbi appreciates, China's holdings of U.S. dollar assets face exchange rate losses, increasing the motivation to reduce holdings.
He warns that if only 10% of private dollar holdings are hedged or converted, it could trigger about $400 billion in dollar sell-offs, which would significantly impact exchange rates and the credit market.
Dalio writes, "Overall, the expected changes in new debt supply and demand have long made shorting U.S. Treasuries easier than going long, and this remains true."
Corporate Debt and AI Financing Boom Intensify Competition for Funds
Dalio points out that the Treasury is not financing in isolation but is competing with all other borrowers and asset issuers in the market. In addition to about $2.1 trillion in net new federal borrowing, corporate debt is expected to add about $1.4 trillion, combined with household and local government borrowing, resulting in a net fixed-income financing demand of about $4.4 trillion for the entire year of 2027, excluding maturing debt that needs to be rolled over.
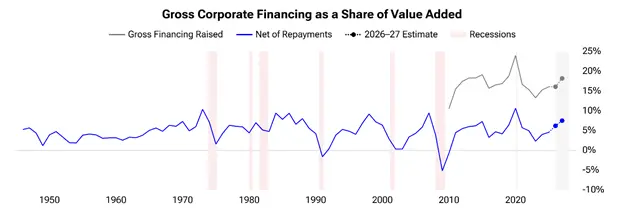
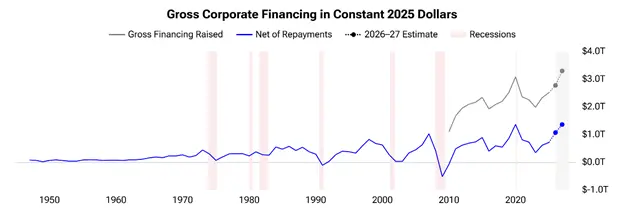
The structural changes in the corporate debt market are particularly noteworthy. Dalio points out that the total scale of U.S. corporate debt is about $15.7 trillion, driven by a surge in capital expenditures related to artificial intelligence (AI), with total corporate debt issuance this year increasing nearly 30% year-on-year. Among this, bond issuance by hyperscaler AI companies reached about $220 billion in the first half of 2026, compared to only about $108 billion for the entire year of 2025.
What is even more concerning is that high capital expenditures are compressing corporate free cash flow, and credit spreads have begun to widen, with investors demanding higher "concessions" to absorb new supply.
Dalio compares the corporate credit market to "the canary in the coal mine," believing it is an early signal that overall financial market pressures will further manifest.
Debt Repayment Costs Erode Fiscal Space
In addition to supply-demand imbalance, Dalio also focuses on the squeezing effect of debt repayment costs on fiscal space.
He points out that with approximately $32 trillion in marketable U.S. Treasury debt, if overall interest rates eventually rise by 1 percentage point, interest expenses alone will add about $310 billion annually, increasing government debt by about $3 trillion over ten years.
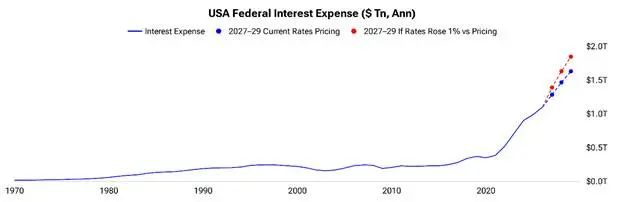
Currently, the average interest rate on existing U.S. debt is about 3.5%, while market interest rates are in the range of 4% to 5.5%.
Dalio notes that even if interest rates do not rise further, as old debt matures and is refinanced at higher rates, interest expenses will continue to climb. Treasury data shows that net interest expenses in the first three quarters of fiscal year 2026 increased by $78 billion year-on-year, a growth rate of 10%.
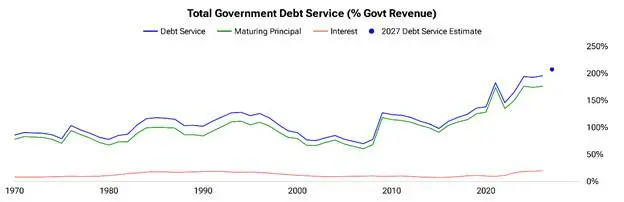
He further points out that the scale of debt principal rollover has risen to about 185% of federal tax revenue, and the total debt repayment cost accounts for about 200% of government tax revenue and is still rising, making the risk of a "death spiral" increasingly concerning.
Global Debt Competition Intensifies, Stock Market Hard to Remain Unscathed
Dalio extends his analysis to a global dimension.
He cites data indicating that the total borrowing scale of OECD member countries' governments is expected to reach a record $17 trillion by 2025, further rising to about $18 trillion in 2026, a 17% increase from 2024 and about double that of a decade ago. European countries are ramping up the issuance of sovereign bonds to finance defense and infrastructure, with Germany's total bond issuance expected to reach about €576 billion by 2027, while the European Central Bank is simultaneously reducing rather than expanding its government bond holdings.
Regarding the stock market, Dalio also issues a warning. He notes that over the past year, corporations have shifted from being net buyers to net sellers (financers) in the stock market, with equity issuance in the first half of 2026 reaching an annualized rate of $1.8 trillion, primarily driven by the AI construction boom. He expects that the pressure for equity financing through IPOs, secondary offerings, and private placements will continue.
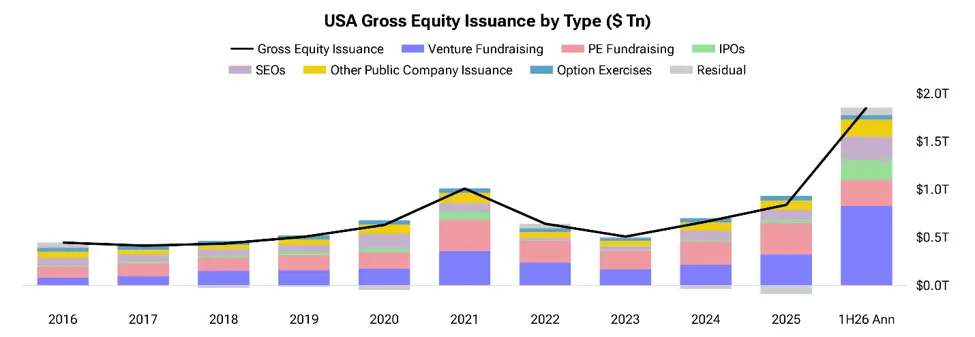
Dalio concludes that "the supply of financial assets (including debt and equity) seems to far exceed the amount that demand can absorb."
He points out that the current market is in the middle of a cycle where interest rates have risen significantly but have not yet led to a substantial decline in the stock market and risk assets. Interest rates will continue to rise until the supply-demand imbalance begins to narrow, at which point interest-sensitive markets and economic sectors will be the first to feel the pressure.
 Risk warning