








"Japan's barrier is not culture, but local investment," said Du Jun, co-founder of Huobi, discussing regulation, stablecoins, and the Asian layout
 Core Viewpoint

 Seizing the opportunity of TOKEN2049, CoinPost interviewed Du Jun, co-founder of Huobi and founder and chairman of WIDTH: why cryptocurrency regulation is inevitable, the next growth areas of stablecoin payments and RWA, and the key to conquering the Japanese market.
The transfer of cryptocurrency asset trading regulation from the "Funds Settlement Law" to the amendment of the "Financial Instruments and Exchange Act" was passed and took effect on July 15, 2026. With cryptocurrencies being positioned as financial instruments and the industry accelerating its integration into the financial system, practitioners are required to establish a more comprehensive compliance system than ever before.
Du Jun, co-founder of Huobi, is currently focusing on the AI-native compliance platform "WIDTH" in Singapore. Why is regulation inevitable? Where is the next growth area? Why is the Japanese market facing difficulties? Taking advantage of the TOKEN2049 event held in Singapore (October 7-8, 2026), CoinPost interviewed Du Jun on October 9.
Reasons Why Regulation is Inevitable
WIDTH is not a trendy business. Compared to perpetual contract DEXs or prediction markets, this is a very labor-intensive task. We acquired a company with a 12-year history and then rebuilt from scratch; signing contracts with individual clients takes 3 to 6 months, and sometimes up to 1 to 2 years. B-end enterprises have never been the most popular companies.
The most profitable entities in this industry, whether early exchanges or certain platforms today, essentially contain elements of regulatory arbitrage. Product innovation does exist, but the existence of regulatory arbitrage cannot be denied.
More importantly, both newly established cryptocurrency exchanges and decentralized exchanges like perpetual contract DEXs face the same significant issue: how to deal with regulation. Once the scale is large enough, regulatory agencies will inevitably seek dialogue and will include you in their regulatory scope.
From 2017 to 2022, the core discussion in the industry has always been "when will licenses be issued." Many regions have not issued licenses at all, and some have explicitly stated they will never issue them. Japan is one of the earliest countries to issue licenses. My judgment since then has been: regulation will definitely come, and licenses will definitely be issued.
Why have I always believed that regulation will come? Market size will affect the attention and resource investment of regulatory agencies, but it is not the only factor. Risks such as anti-money laundering, investor protection, and financial stability always exist. As the number of users increases and business scales expand, the necessity for regulatory agencies to establish clear and enforceable rules will only grow stronger.
Today's cryptocurrency market has reached a considerable scale. If we include the tokenization of RWA, stablecoins, and traditional financial assets, the potential market will be even larger. For example, in the stock market, the total market capitalization of Nasdaq-listed companies has reached several trillion dollars.
This indicates that there is still significant room for traditional assets to be brought on-chain, but we cannot directly equate the potential space with the already realized tokenized market scale. Markets like Nasdaq and Hong Kong are also exploring stock tokenization and extending trading hours.
As long as the market continues to expand, regulatory motivations will continue to strengthen. Economic activity, taxation, and financial stability will enter policy considerations, and consumer protection, anti-money laundering, and market fairness are equally important. Especially for businesses targeting retail customers, regulatory agencies often place greater importance on licensing requirements and risk management.
The primary purpose of founding this company is to help exchanges—whether decentralized or centralized—establish good dialogue mechanisms with regulatory agencies.
From onboarding reviews, KYC, KYB (corporate certification), KYT (transaction monitoring), to anti-money laundering and anti-fraud, all our products are designed to communicate with authorities "in a language that regulatory agencies can understand." This is very different from those RegTech companies that only sell KYC APIs: we provide a complete solution, tell clients what to do, and sometimes even communicate with regulatory agencies on their behalf.
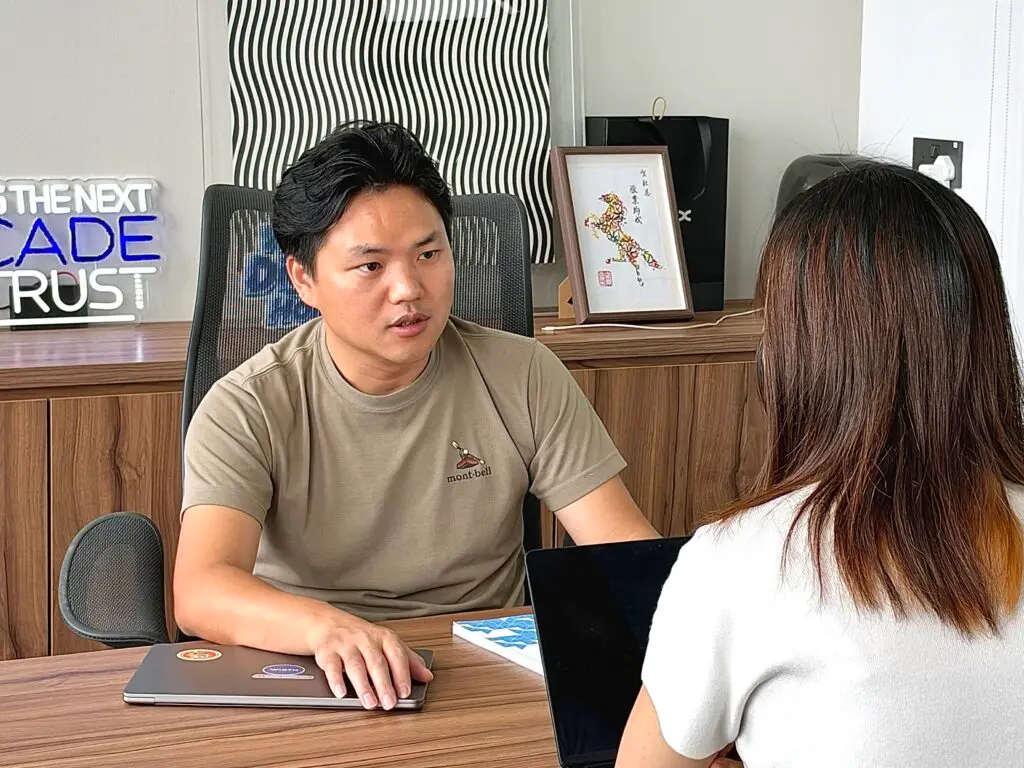
Compliance is a "Catch-Up"
We hope to achieve this, but from the practitioners' perspective, they may not think so. Decentralized exchanges like perpetual contract DEXs may not want to be strictly regulated. At the stage where they are not truly enforced by authorities, they are neither sanctioned nor facing legal measures, and they are doing well. Their primary goal is to acquire new users, new traffic, and new markets. So at this stage, they do not want regulation and do not need our intervention.
What we can do is help them establish risk identification and compliance record mechanisms from the early stages of their business, while minimizing the landing costs and impact on user experience. When regulatory agencies conduct inspections in the future, the platform needs to provide evidence that it has been continuously identifying, assessing, and addressing risks.
For example, if a deposit address involves sanctioned entities or other high-risk funds, the platform should take measures such as restrictions or reporting based on applicable laws, risk policies, and investigation results. Many of the cases we currently support involve this type of work—helping to identify these high-risk addresses.
Another example is, a few years later, when regulatory agencies ask, "Why did you have a large transaction with a high-risk address?" can you provide the screening results, investigation records, and disposal basis from that time? Regulatory agencies are concerned with whether operators have identified risks, whether reasonable measures have been taken, and whether they can explain the decision-making process.
If issues are pointed out during inspections, operators must quickly formulate a rectification plan and take effective action. Introducing compliance software or hiring auditing firms can be part of the rectification, but ultimately what is questioned is: does this mechanism really operate, have the issues been corrected, and are the records sufficiently complete? Simply implementing a system does not guarantee that regulatory agencies will be lenient, nor does it replace statutory compliance obligations.
The Next Growth Area
At this stage, I personally would not prioritize investing in exchanges. I believe exchanges are becoming a gradually mature financial intermediary business, and competition is becoming increasingly fierce. The business models and profitability of various exchanges differ greatly, but in my investment judgment, asset issuance and its related infrastructure are more worthy of attention.
Currently, asset issuance is more important. I believe there are two key directions.
The first is stablecoin payments. Payment centered around stablecoins, whether in infrastructure development or from issuance to circulation and future applications, is an extremely significant topic. Therefore, we have been investing around the stablecoin-related industry.
The second is RWA. I will distinguish between standardized and non-standardized assets. The next three years belong to standardized assets, such as bonds and stocks. The advancement of standardized assets is very fast, and the opportunities are immense; this is a market worth trillions, even tens of trillions, or hundreds of trillions of dollars. It is more easily accepted by ordinary people than native crypto projects and is also easier to access large markets.
In addition, starting a project now, launching a meme to make some quick money is certainly possible. But frankly, that does not create value.
Blockchain Technology Will Integrate into More Industries
So far, as a user-facing product, I have not seen a sufficiently mature and representative case of "crypto-native" combining with "AI-native." There are many concepts, but whether they can become sustainable applications still needs time to verify. However, in specific scenarios such as on-chain risk identification, compliance analysis, and audit assistance, AI has already been put into practical use—this is exactly what WIDTH is doing. In the long run, the notion of treating crypto as an independent industry will gradually fade, and the functions of blockchain will integrate into finance and other industries.
Is Binance considered a company in the crypto industry? Of course, it can be said that way. Today, is Visa using stablecoin payments considered part of the crypto industry? Ten or twenty years ago, saying you were an internet company was quite cool and respectable; now, almost no one introduces themselves that way.
Crypto, like the internet, is just a technology. Blockchain is a ledger technology that, with its characteristics of censorship resistance, transparency, and immutability, solves many problems in the financial sector.
Currently, the best application scenario for blockchain is payments, and the largest payment is undoubtedly stablecoin payments. The biggest scenarios are payments, asset transfers, finance, and the confirmation of financial asset ownership. What is most important now is to strengthen and expand stablecoins and to move towards the confirmation and transfer of asset ownership in this direction.
Decades ago, banks used abacuses; we wouldn't call it "abacus banking"; after computers emerged, we also wouldn't call all banks "computer banking." It is a technology, a fusion.
The best state of blockchain is to seep into various industries quietly, like a gentle rain nourishing everything, entering their genes, rather than becoming an independent category—it should be like water.
Asian Layout and Plans for Japan
First, you need to know which markets you will not enter. We probably will not enter the European and American markets within three years.
In June 2026, we established our first office aimed at overseas markets in Hong Kong. The Middle East office is planned to be located in Dubai, originally scheduled for the fourth quarter of 2026, but the pace has slowed down a bit, and it is expected to land in the first quarter of 2027. In Japan, Taiwan, and Malaysia, we also have colleagues in sales and business development keeping an eye on the market.
Recently, we have also participated in industry associations and industry summits in Japan, the Philippines, Malaysia, Indonesia, and Vietnam. The current focus layout is: Hong Kong is responsible for North Asia, Dubai for the Middle East, and Singapore for Southeast Asia.
I plan to go to Japan in early December 2026. There is already a group office in Japan, and I will go check the situation then.
Challenges in the Japanese Market
I agree with the statement that "the Japanese market is slightly more difficult than other markets." There are two reasons.
The first is the team itself. Whether going overseas or anything else, if operators are not personally embedded in that land, it is difficult to develop the business. This is especially true in Japan. Japanese culture places a relatively higher value on localization and is more conservative; foreign products often face challenges in acceptance.
But I do not think this is the core issue. The core is: are you genuinely operating seriously, and have you truly connected with the local area? Yahoo Japan has done very well, hasn't it? Many international companies have succeeded in Japan.
The core issue is whether you have a real willingness to invest in this land. Investment is not just money, but truly integrating with the local market: do you have local shareholder relationships? Are local financial compliance policies and market strategies formulated locally?
Or are you just directly transplanting the globalized, mature market strategies of your group? Have you truly invested 100%, or even 200% of your energy, time, costs, and attention into the operation? If you have done this, I believe there is no particularly difficult market to conquer in the world.
Japan is a very mature capital market. Compared to English-speaking countries or more inclusive countries, it is indeed a bit more challenging, but that is not the core issue. The core issue lies within yourself.
Whether in terms of policies, regulations, or users, have you truly understood the local market sufficiently? And what value have you actually created? If you just want to "give it a try," it is highly likely that you will not succeed.
 Risk warning
Popular articles





