








Glassnode: Bitcoin falls below short-term cost, funds exit but trend remains intact
 Core Viewpoint

 Bitcoin has fallen below the short-term holder cost basis of $75.6K and is lagging behind the U.S. stock market, which has recovered the election day closing price. The supply of stablecoins has decreased by $14.2 billion over the past 30 days, marking the fastest contraction since June 2022, with net outflows from spot ETFs and a deeper discount on Coinbase. The near-price long leverage has basically been cleared, and wallets holding 100 to 10K BTC have started to buy. As long as the June low of $58.5K is maintained, the trend reversal since August remains valid.
Author: Glassnode
Compiled by: Gu Yu, ChainCatcher
Bitcoin has fallen below the cost basis of short-term holders and is lagging behind stocks, while stablecoins, ETFs, and U.S. buyers show that funds are leaving. Leverage has been cleared, and two large wallet groups have begun to buy, which keeps the trend shift in August valid above the June low.
Executive Summary
Bitcoin has dropped below the short-term holder cost basis of $75.6K and is lagging behind stocks, while the funds that could boost it continue to leave.
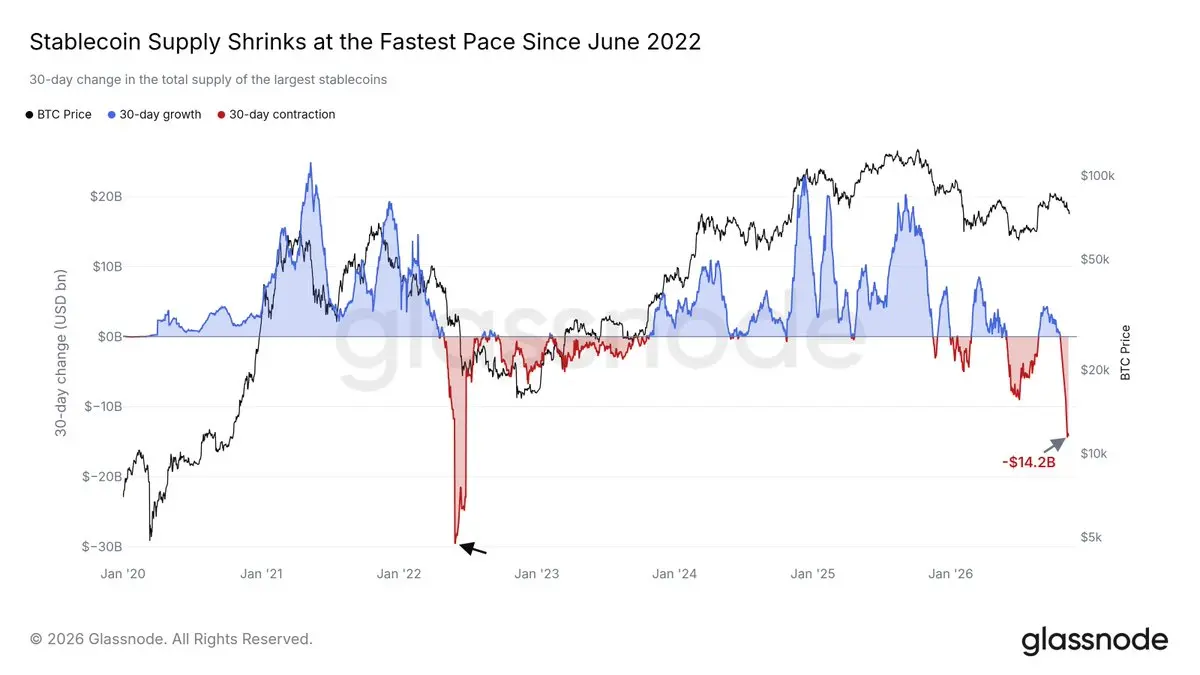
The supply of stablecoins is shrinking at the fastest rate since June 2022, ETFs are net sellers, and Bitcoin is trading at a discount on Coinbase.
On the other hand, this decline has cleared most of the long leverage near the price, with buy orders outnumbering sell orders in the order book, and two large wallet groups have begun to accumulate.
The September high is the first higher high since the historical peak in 2025, and as long as the price remains above the June low of $58.5K, this trend shift remains valid.
Recent Buyers at a Loss
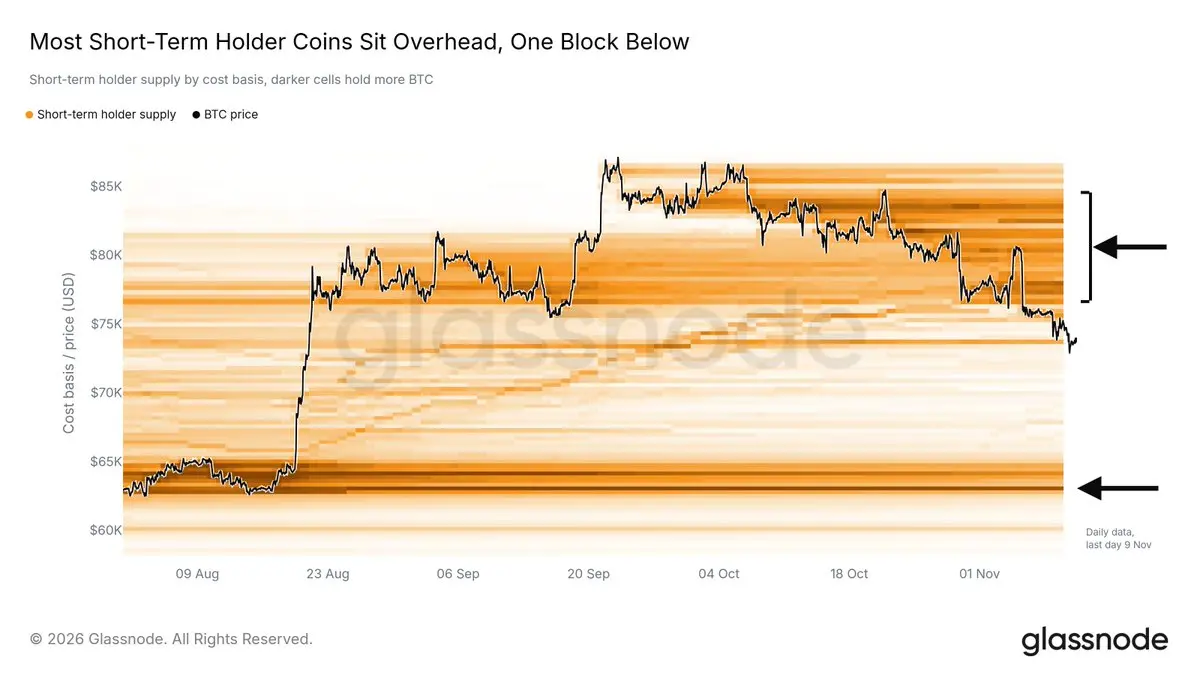
Last week, we identified the $73K to $76K range as a level to watch. Since then, Bitcoin has slipped into that range, trading close to $74K, below the short-term holder cost basis of $75.6K, which is the average price paid by investors who bought in the last 155 days. At the September high, almost all short-term holder tokens were in profit. Now about 35% are in profit, while those selling are doing so at a slight loss.
Cost Basis Distribution shows where these tokens were bought. Currently, about two-thirds are above the price, distributed across three ranges bought between August and October, up to $83.6K. Many of these holders may take advantage of a rebound to exit at breakeven. Below the price, the only dense block is between $62K and $66K, where purchases were made near the August low.
Note that the larger structure since August remains valid. The September high is the first higher high since the historical peak in 2025, and the price is still well above the June low of $58.5K. Reclaiming the True Market Mean of $77.5K would bring about half of the short-term holder tokens back into profit.
Left Behind by Stocks
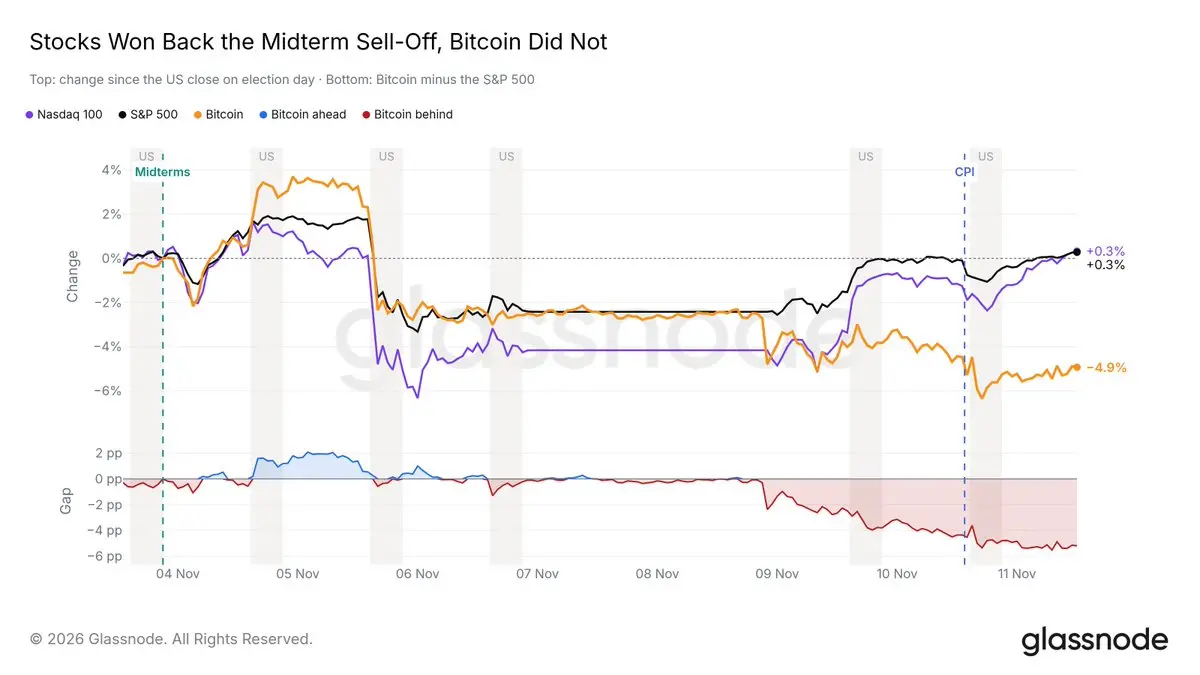
Last week we pointed out that most of Bitcoin's mid-term decline occurred before the vote. The subsequent sell-off that began on November 5 impacted both stocks and Bitcoin simultaneously. Since November 9, their paths have diverged: S&P 500 Index and Nasdaq 100 Index have recovered above the election day closing price, while Bitcoin fell again after the CPI announcement on November 10 and is currently down about 5%.
Reclaiming its election day closing price of $77.8K would bring Bitcoin back in sync with stocks.
Bond Pricing for More Rate Hikes
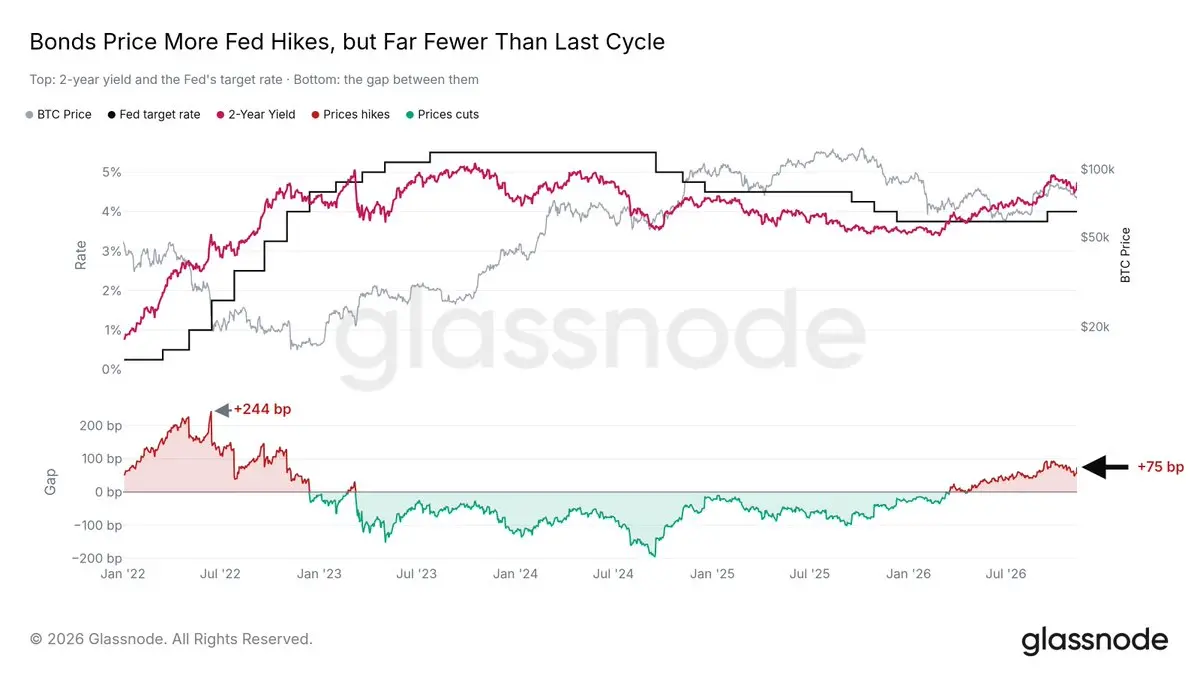
Interest rates have intensified the pressure. Two-Year Treasury Yield reflects traders' expectations for the average level of the Federal Reserve's policy rate over the next two years. Currently at 4.75%, it is 75 basis points higher than the Fed's current rate of 4%, indicating that the bond market is pricing in further rate hikes.
Note that this is far from the shocks seen in 2022. In June 2022, the same gap peaked at 244 basis points, while today's gap is about one-third of that. Since late October, the gap has also narrowed. Higher rates still pose headwinds for risk assets, but the bond market does not expect a repeat of 2022.
Stablecoin Withdrawal
Stablecoins are the cash of the crypto market: traders hold dollars on exchanges and chains before buying. In the past 30 days, total stablecoin supply has decreased by $14.2 billion, marking the fastest contraction since June 2022.
The contraction in supply means holders are redeeming stablecoins for dollars and taking that cash out of the market, leaving less fuel for a rebound. The same pressure is reflected in Tether, which is trading slightly below $1. If the 30-day change turns back to growth, it would be the first sign of new funds flowing in.
Declining U.S. Demand
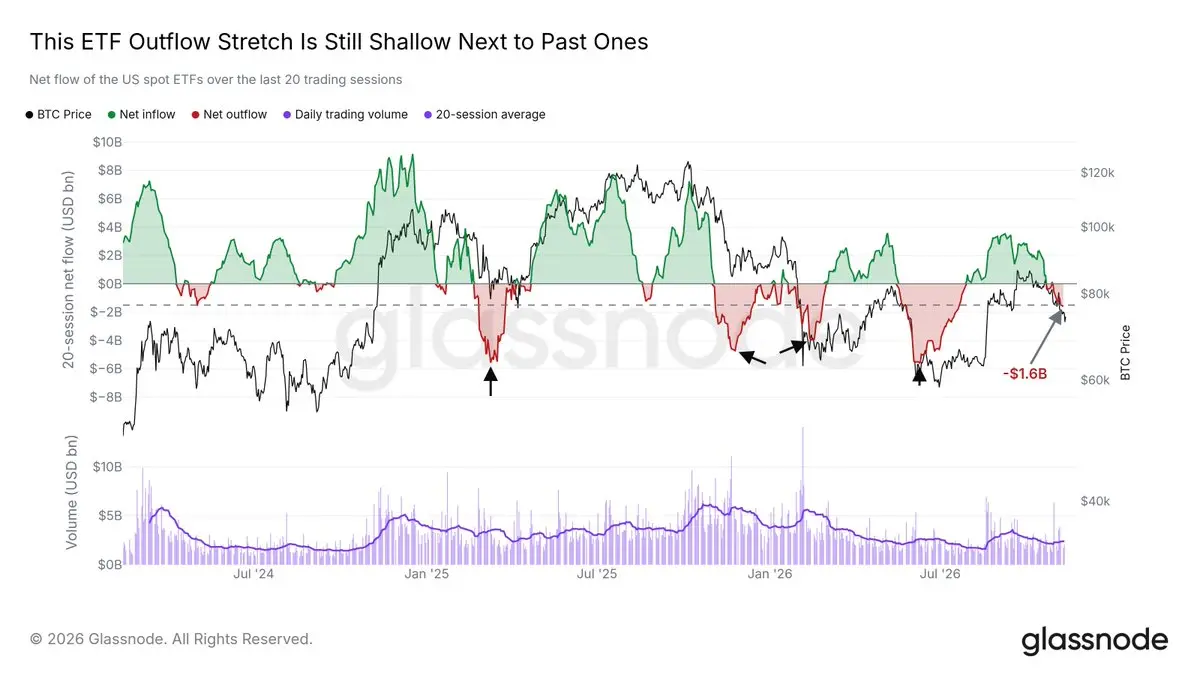
U.S. Spot ETF has turned to redemptions. Over the past 20 trading periods, these funds have seen a net outflow of $1.6 billion, and on November 9, that total crossed the $1.5 billion threshold we use to define a period of outflow.
By the standards of previous outflow periods, this one is still relatively shallow: most previous ones were much deeper. Each time, inflows only returned after Bitcoin made a low, so the return of inflows will confirm the low in hindsight.
No Premium on Coinbase
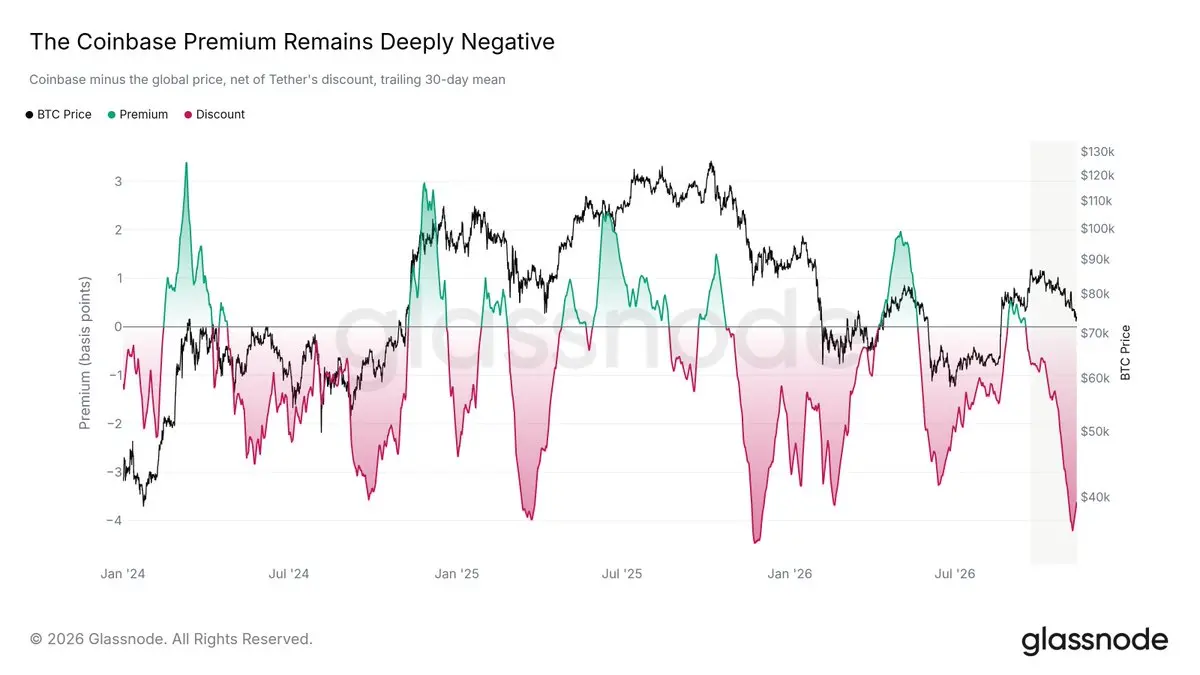
Coinbase Premium compares the price of Bitcoin on Coinbase (the main trading venue for U.S. investors) to the global price. We excluded some of the discount caused by Tether trading below $1; otherwise, the discount would appear deeper than it actually is. Based on the 30-day average, the premium has been negative throughout the entire decline since the September high, and the current discount is the deepest since February.
In past rebounds, the premium turned positive as U.S. buyers were willing to pay a premium for Bitcoin. They are not doing so now. If the premium turns positive and stays there for several weeks, it would indicate that demand from the U.S. is returning.
Thin Near Price, Heavy Below
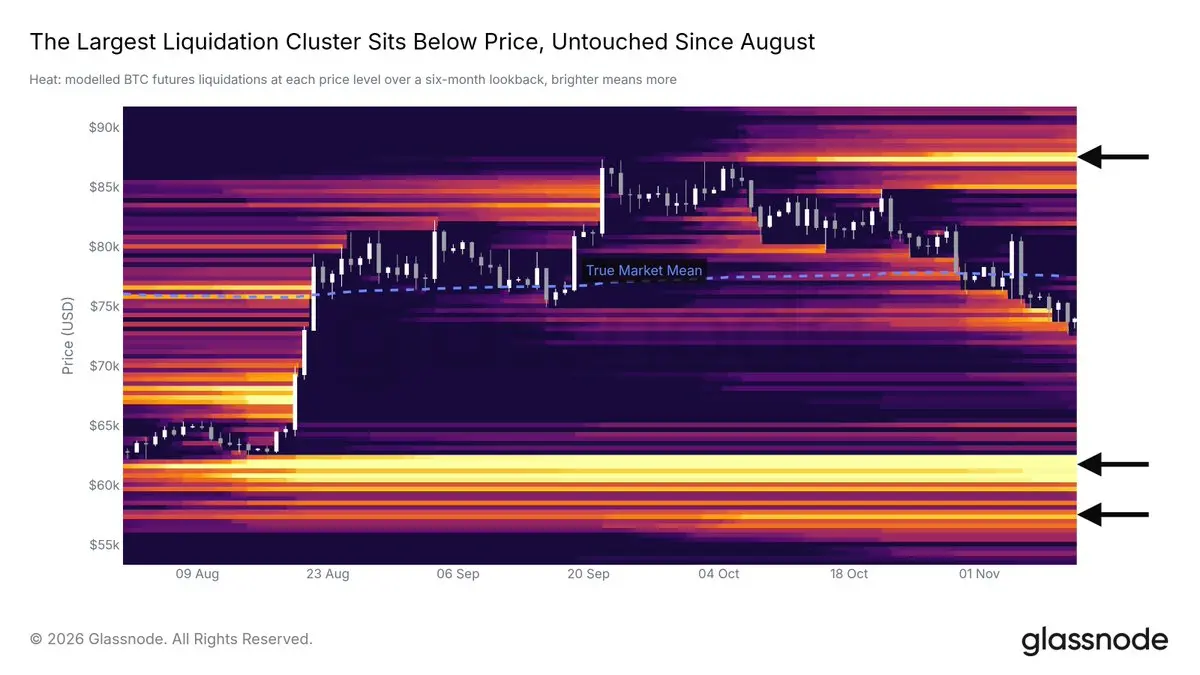
Liquidation Heatmap simulates the prices at which leveraged futures positions would be forcibly liquidated. On the positive side, the slow decline since the September high has passed through most of the long liquidation levels accumulated on the way down, as indicated by the dark areas following the candlestick chart. This has eliminated most of the fuel for forced selling near the price.
The largest cluster on the six-month chart is located far below the price, between $59.5K and $62.6K, and has not been touched since the August low. Between it and the price, the chart is relatively thin. Meanwhile, open interest has rebounded to levels seen at the September high, despite the price dropping about 15%, indicating that traders have increased short positions during the decline. If the price turns upward, these shorts will have to buy back; the largest cluster above the price is around $87.5K.
Buy Orders Below, Thin Above
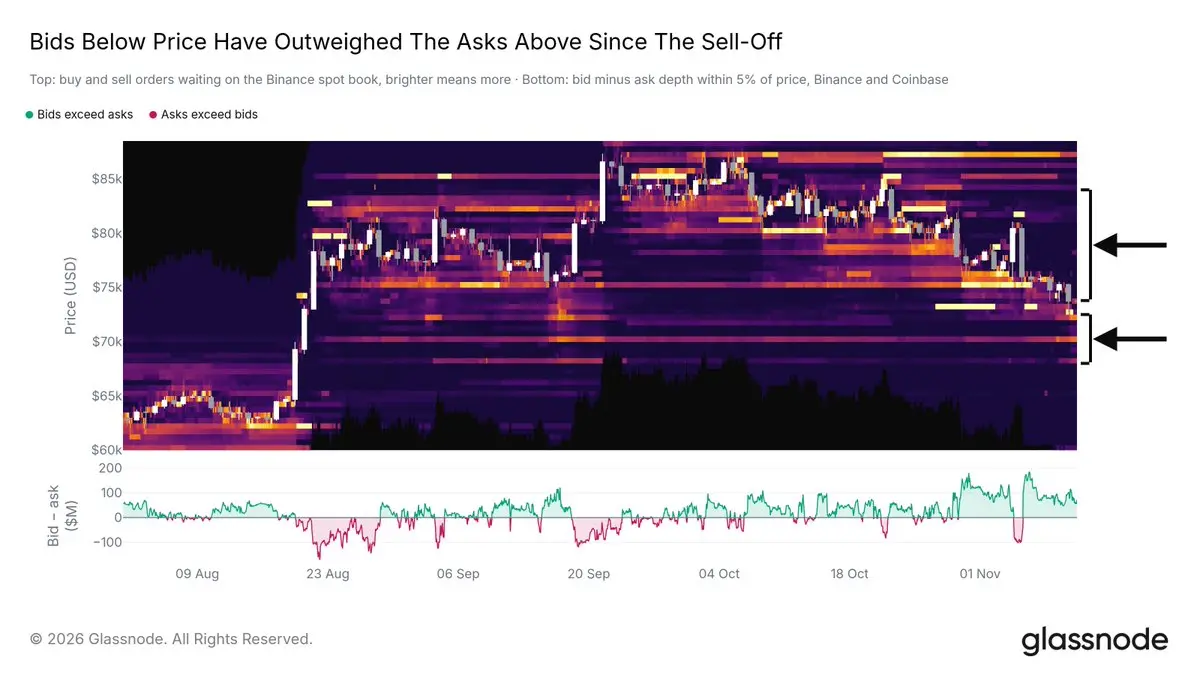
Spot Order Book shows the same trend. Since the sell-off on November 5, buy orders within 5% of the price on Binance and Coinbase have consistently outnumbered sell orders every hour. The largest buy orders are marked in the lower bracket of the chart, located in a block between $68K and $72.5K.
The upper bracket marks the opposite situation: aside from sell orders right above the price, the order book is thin up to about $84K, which is the dark area on the heatmap. Price increases will encounter very little resistance from the order book itself, but must still pass through short-term holders waiting to exit at breakeven. Note that orders can be canceled at any time; some of these buy orders were canceled during the sell-off and then re-listed.
Large Wallets Entering
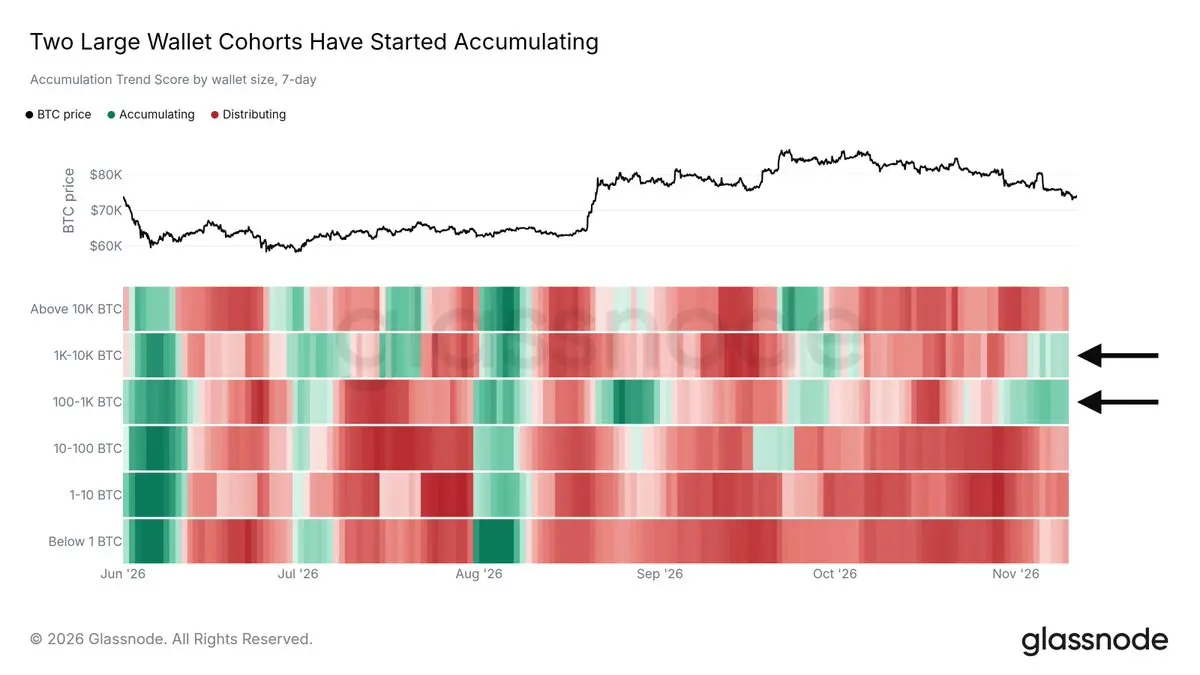
Accumulation Trend Score tracks whether each wallet group is increasing their balance (score close to 1) or decreasing their balance (close to 0), weighted by wallet size. Over the past week, two groups scored above 0.5: wallets holding 100 to 1,000 BTC, and wallets holding 1,000 to 10,000 BTC. Both have been distributing for most of October. Note that these two groups also turned to buying in late September but did not sustain it.
Every other group is still reducing their holdings, from the largest wallets holding over 10,000 BTC to wallets holding less than 1 BTC. This is early buying on dips from a narrow group. If smaller groups join in, it will indicate that buyers are returning across the market.
Conclusion
Bitcoin is undergoing a pullback with almost no new capital support: recent buyers are at a loss, it is lagging behind stocks, and stablecoins, ETFs, and U.S. buyers all show that funds are leaving. There are few optimistic reasons recently. In contrast, leverage near the price has been cleared, and two large wallet groups are buying.
For investors interpreting August as the starting point for a higher timeframe reversal, this is the area where mean reversion will begin. Recapturing the short-term holder cost basis of $75.6K will support this view. A sustained drop below $73K, the lower bound of last week's range, will point to a longer period of consolidation; while a close below the June low of $58.5K will reverse the trend change from August.
Data as of November 11, 2026, with prices and derivatives at 11:00 UTC, and order book at 09:00 UTC; ETF fund flows, stablecoin supply, cost basis, and accumulation scores as of November 9.
 Risk warning Risk warning

Popular articles





